

1. The Regime
Risk-on, resolved and consolidating — the round trip from the June defensive rotation completed, then digested.
This was the week the prior fortnight’s tension resolved. It opened with a violent confirmation — the SPY baseline ripping from Friday’s 43 all the way back to 52 in a single Monday session — and spent the rest of the week consolidating that gain in the calmest possible fashion. The baseline arc tells it cleanly: 43 (prior Fri) → 52 → 55 → 54 → 53. A rip higher to recover the entire June drawdown, an extension to a fresh high on Tuesday’s Q2 close, then two orderly one-point give-backs into the holiday. Every give-back came on positive momentum, and every fear-and-flight signal that would validate a real de-risking stayed absent: the dollar sat near the top all week on flat momentum (never once accelerating across the whole stretch), VIX was crushed hard every single session, and the safe-haven bond bid fully unwound. This is a market that resolved bullishly and then digested its gains — not one under any distribution.
The one-line takeaway: The market spent the week confirming the bottom it hinted at the prior Friday — a one-day rip back to the highs, then a quiet, orderly digestion into the holiday, with cyclicals and growth firmly in charge.
2. The Week’s Arc
Monday 6/29 — The confirmation rip. The bullish resolution the prior Friday only hinted at (baseline falling to 43 but on positive momentum) arrived emphatically: the baseline ripped to 52 (+9), recovering the entire defensive-rotation drawdown in one session. The risk complex — growth, small-caps, EM, Nasdaq — led the board higher on both strength and momentum, the dollar stayed flat, and VIX got crushed. The rotation was over; risk-on was back.
Tuesday 6/30 — Q2 closes at the high. The baseline extended to 55 on the last day of the quarter, consolidating the risk-on turn. Industrials surged to the #2 sector (from #4), lifting the Industrials-overweight book, and the growth complex took the very top of the asset board directly behind a flat dollar. SMH’s momentum went parabolic (+81), the most extreme reading of the whole stretch — which we flagged as a blow-off risk to respect, not chase. Q2 closed firmly risk-on.
Wednesday 7/1 — Q3 opens; the sector board turns fully cyclical. A benign one-point cool to 54 on positive momentum. The headline was the sector board: Financials took the #1 sector outright — a cyclical leading — which fully reset the Industrials trim wire that had been in play all week. SMH’s parabolic momentum began its reversion (+81 → +62), vindicating the do-not-chase discipline.
Thursday 7/2 — Orderly digestion into the holiday. A second one-point cool to 53, again on positive momentum, in low pre-holiday volume. Financials held #1, the biotech complex actually strengthened its rank on an otherwise cooling day, and the held cannabis position firmed back up. SMH’s reversion decelerated and looked to be finding a level. A quiet, constructive close to the short week.
What we got right this week: Reading the prior Friday’s positive-momentum-on-a-falling-baseline as a bottoming signature rather than a breakdown — Monday’s rip confirmed it within one session. Holding the Industrials overweight through the trim-wire noise rather than trimming on a one-day rank flip — the wire fully reset by Wednesday as Financials took #1 and Industrials sat firm at #3. And respecting the SMH blow-off at +81 rather than chasing it — the reversion began the very next session.
What we’re watching: Whether SMH’s strength rank bases off the blow-off reversion (47) or resumes its descent — the tell for whether the semis leadership re-engages or continues to unwind. And whether the two-day baseline drift (55 → 53) is just a pre-holiday digestion (the base case, given positive momentum throughout) or the start of something that needs the risk complex to re-accelerate to arrest. We enter the holiday with the regime firmly risk-on but the tape a touch lower-energy than the Monday–Tuesday peak.
3. The Leadership Map
🟢 Leading
Biotech (IBB / XBI) — commanded the top of the board all week and strengthened its rank into the holiday even as the broad tape cooled. The durable defensive-growth anchor of the leaders tier, improving when it counted.
Airlines (JETS) — held the board’s top cyclical-breakout relative strength every session, with momentum that stayed strong (+30s–40s) throughout. The standout cyclical breakout of the whole multi-week stretch.
The financial / rate-sensitive complex (banking, regional banks, insurance, residential REITs) — owned the top 10 all week, and by week’s end was firing under the strongest possible backdrop as Financials took the #1 sector. The banking confirmation trade — the most durable trade of the stretch — at its cleanest, with the rate-sensitive names (REITs, insurance) strengthening alongside.
🟡 Emerging
Growth / small-caps / cyclicals (growth, small-caps, Dow, Value) — took the top of the asset board this week as the risk-on rotation matured, sitting directly behind a flat dollar. The confirmed leadership engine of the new regime, though momentum cooled into the holiday consolidation.
Industrials (XLI) — climbed from #5 to the #2–#3 sector range over the week and reset the trim wire; the cyclical rotation is reinforcing the Industrials-overweight book.
🔴 Lagging
Semiconductors (SMH) — the cautionary tale of the week: parabolic momentum (+81) at Tuesday’s peak, then a two-session reversion (+81 → +62 → +51) with the strength rank slipping. The blow-off/reversion lesson live on the tape — the reason we hold, don’t chase, at extended readings.
Energy (commodity and equity alike) — dead last every session, unchanged in character from June into July. The most persistent laggard on the board.
Crypto & precious metals — the speculative and inflation-hedge corners bore the weakness all week (crypto’s momentum the worst on the board, metals uniformly negative), while equities held. The benign profile that defined the whole pullback.
📸 The Tape at Thursday’s Close (week’s final session — holiday Friday)
Where the three rankings stood at the pre-holiday close. The daily posts carry the day-to-day; this is the snapshot the weekly call is built on.
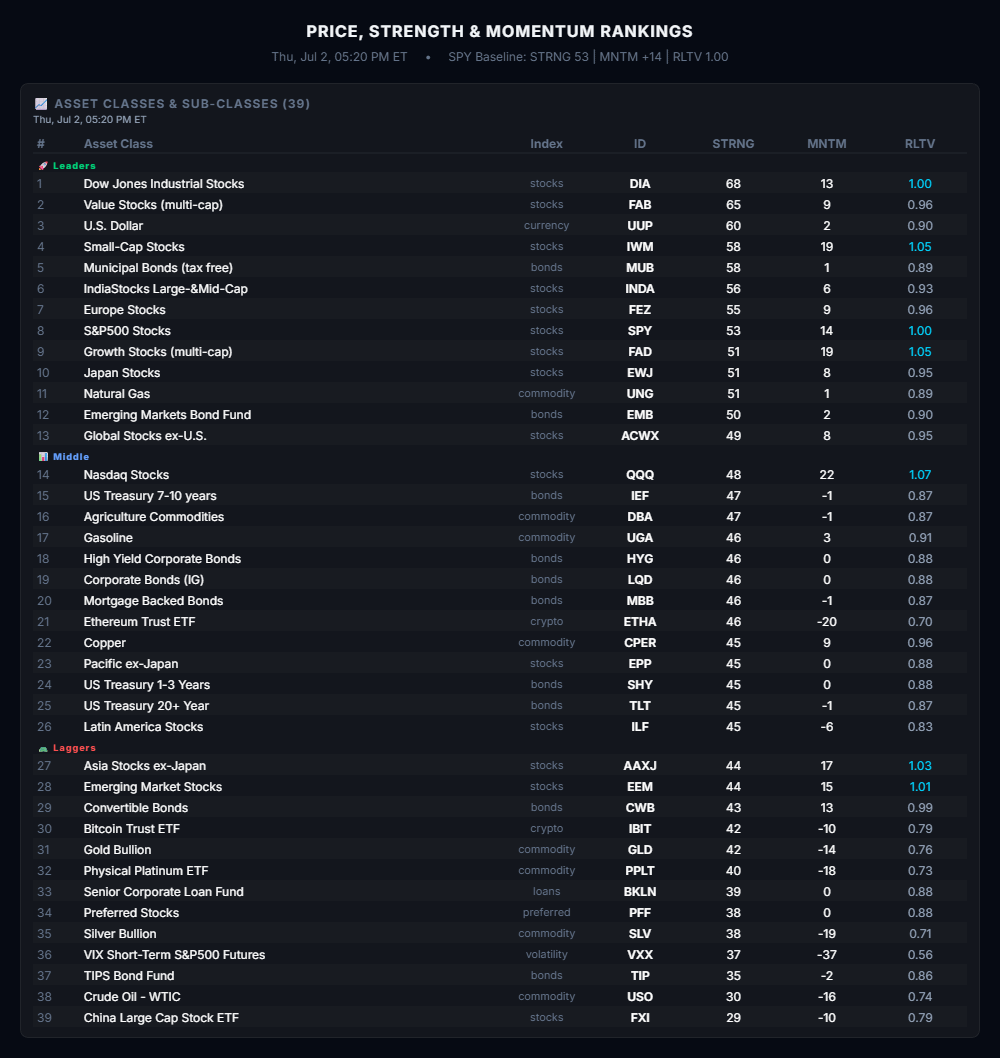
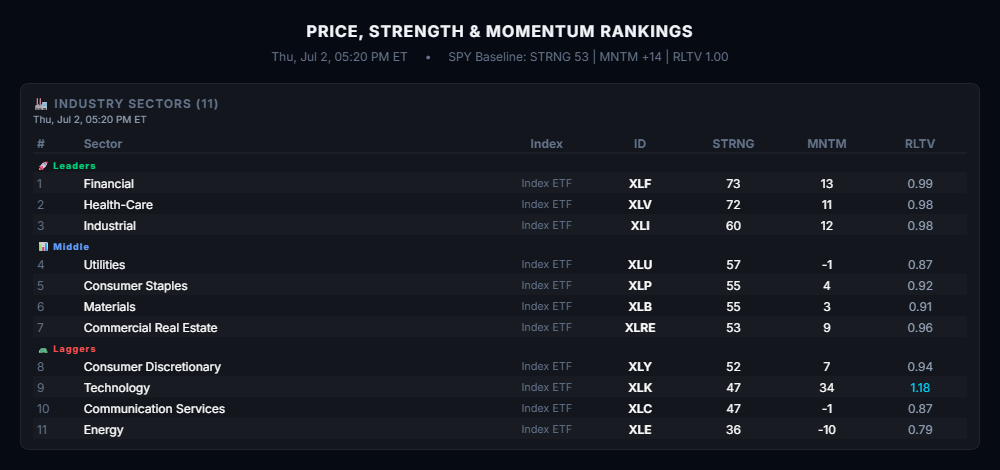
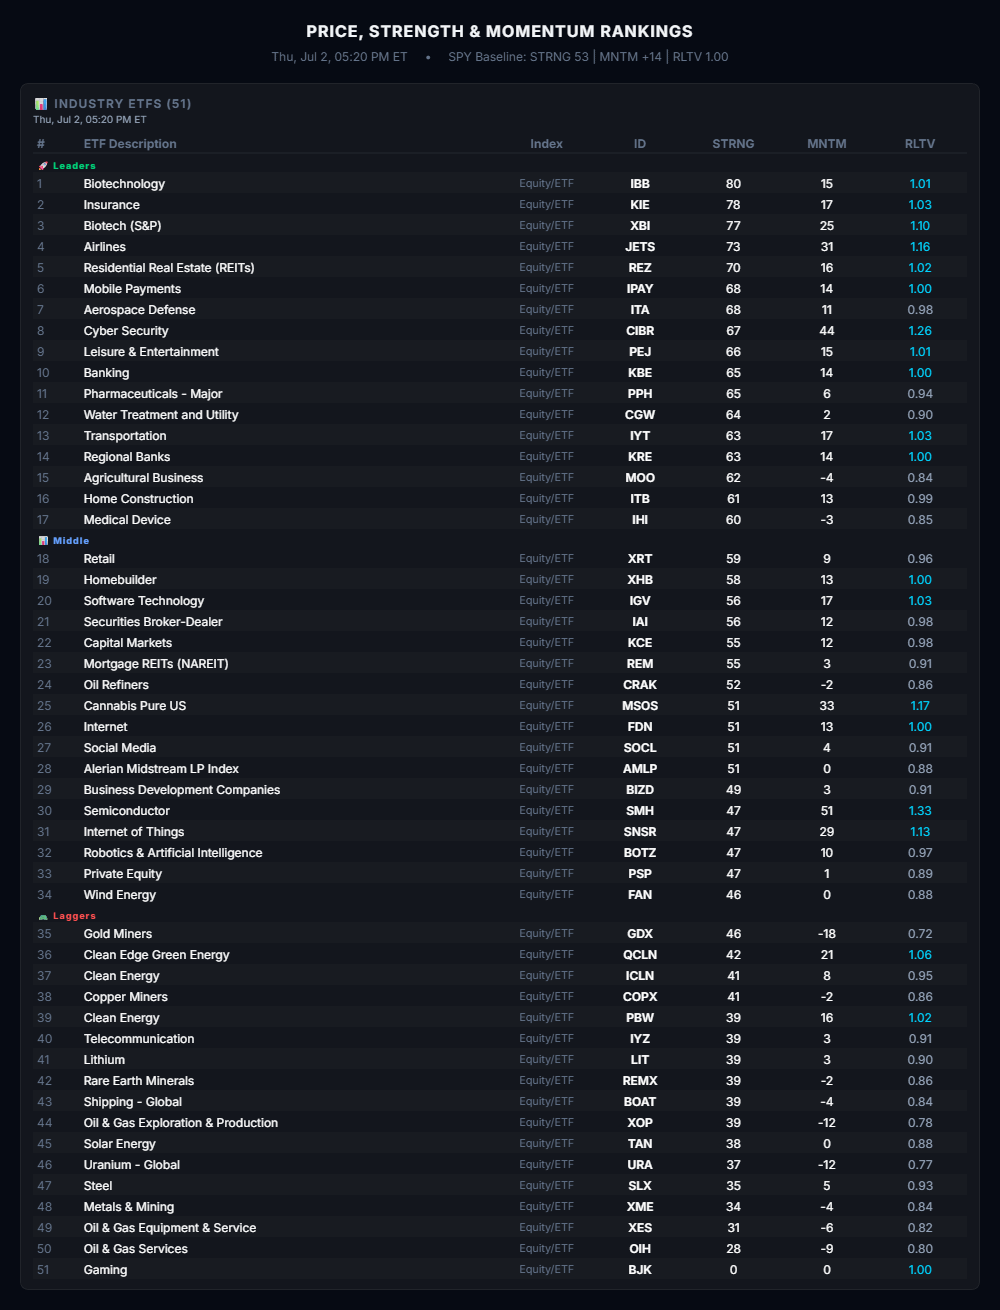
(In the Substack editor, drag each screenshot in at these three spots — don’t paste a file path, Substack uploads the image directly.)
4. The Macro Read
The “why” underneath the tape: this week was the clean resolution of a rate-driven repositioning, and the character of that resolution matters as much as the direction.
The June pullback was never a growth scare — it was a duration/rate rotation, and the tell all along was that the risk complex never actually broke while the dollar bid on flat momentum and VIX stayed crushed. This week proved the read correct in the most direct way possible: the moment the selling pressure exhausted, the baseline didn’t grind higher tentatively — it ripped back to the highs in a single session, with the speculative risk complex (growth, small-caps, EM) leading. Markets recovering from genuine distress don’t snap back that way; markets digesting a rate rotation do. The one-day round trip was the signature of a pullback that was technical, not fundamental.
The sector rotation underneath reinforces the story. Financials taking the #1 sector by week’s end is the market pricing a constructive rate backdrop — banks and rate-sensitives lead when the curve and the rate path are working for risk, not against it. The homebuilder/REIT complex holding leadership alongside banking says the same thing from the duration side. And the fact that the defensive tier (utilities, staples, health-care beyond its biotech sleeve) drifted down the board as the week progressed confirms there was no residual flight-to-safety bid — the rotation was fully into cyclicals and growth.
The one genuine caution the week surfaced was internal, not macro: SMH’s parabolic blow-off and subsequent reversion. That’s not a market-regime signal — it’s a single-name/sector excess unwinding, the recurring reminder that the hottest momentum carries the most reversion risk. It’s worth watching for whether it drags the broader tech-momentum names, but as of the holiday close it reads as an isolated blow-off correcting, not a leadership breakdown. The read into the long weekend: a resolved risk-on regime, digesting gains in an orderly fashion, with the leadership sitting exactly where a constructive rate backdrop would put it.
5. How I’m Positioned — The Pudding
The proof is in the pudding, so here’s the book at theme level.
Industrials: overweight — held through the trim-wire noise, and fully vindicated. This was the week the discipline earned its keep. My Industrials-overweight book has a hard rule: if Industrials loses the #1 sector rank to a defensive sector, I trim. That condition technically triggered the prior Friday when Health-Care took #1 — but I hold to a consecutive-confirmation standard, not a one-day flip, and the context was a cyclical resurgence, not a defensive regime taking hold. So I held the overweight. Over this week, Industrials climbed from #5 back to the #2–#3 range, and by Wednesday Financials — a cyclical — took the #1 sector outright, fully resetting the wire. Had I trimmed on that one-day flip, I’d have sold at the exact bottom and spent the week re-buying into a cyclical-led tape. The overweight is intact and well-positioned. One day should never make a portfolio decision; this week was the proof.
No financials in my book. The financial and rate-sensitive complex was the single best-led cluster on the board again this week — banking, regional banks, insurance, REITs owning the top 10, and by week’s end firing under a #1 Financials sector. I read it openly in the tape because it’s the clearest signal out there and I won’t pretend otherwise. But it’s not in my book, and I’m not chasing it mid-move. I note the strength; I stay in my lane.
Semis: market-weight, by hard-won lesson — and this week is exactly why. Semiconductors printed the most extreme momentum reading of the whole stretch at Tuesday’s Q2 close (+81), and the temptation to chase a name running that hot is precisely the trap this model has taught me to avoid. I held market-weight and explicitly flagged +81 as a level to respect, not add into. The reversion began the very next session and ran two days. Holding market-weight through the blow-off — neither chasing the peak nor panic-cutting the reversion — is the whole discipline. The hottest momentum carries the most reversion risk; this week it played out on schedule.
The cannabis position: held full-size at conviction throughout — thesis intact, position working. I’ve held this position full-size continuously — the thesis never broke, so the position never moved. Through the June soft patch I flagged the weakness honestly, but nothing ever hit the bar that would break the thesis (a decisive, sustained break below the mid-range on negative momentum), so I held. This week the position was vindicated as it re-strengthened: the strength rank firmed and the relative strength held comfortably above the market all week, with the position beating the broad tape. Holding conviction through noise — rather than flinching at a soft patch and manufacturing an exit — is what let the position be there for the recovery. That’s the discipline: the thesis determines the position, and the thesis held.
6. The Bottom Line
This week resolved the June tension decisively in favor of risk — a one-day rip back to the highs, then an orderly, positive-momentum digestion into the holiday, with cyclicals and growth firmly in charge and Financials taking the #1 sector. My Industrials overweight was vindicated by holding through the trim-wire noise (the wire fully reset by mid-week), my market-weight semis discipline was vindicated by the SMH blow-off reverting on schedule, and my full-size cannabis conviction held and worked as the position re-strengthened. Into the long weekend I’m watching one thing above all: whether the two-day baseline drift is just pre-holiday digestion — the base case, given positive momentum throughout — or the start of something that needs the risk complex to re-accelerate to arrest.
This report is a synthesis of the week’s daily Price, Strength & Momentum reads. For informational and educational purposes only; not investment advice. Positions and views are my own and may change without notice.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.