

1. THE QUICK SCAN
Overnight Tape Summary: WARSH SWORN IN AS FED CHAIR TODAY. GLOBAL BOND ROUT OVERNIGHT — JGB 30Y AT 4% FIRST TIME SINCE 1999. UK 10Y NEAR 5.14%. GERMAN 10Y +7.5 BPS. US 30Y BACK TO 5.10% (+7.0 BPS). US 10Y +7.7 BPS TO 4.56% — HIGHEST IN NEARLY A YEAR. BRENT HIT $109 INTRADAY, NOW $108.39 (+2.53%). HOT JAPAN PPI. TRUMP CONCLUDED CHINA VISIT WITH NO FIRM TRADE COMMITMENTS. METALS COORDINATED CRASH: SILVER −8.43%, PLATINUM −4.94%, COPPER −5.10%, GOLD −2.84%. ES 7,432.25 (−1.24%) GIVING BACK YESTERDAY’S WAR HIGH. NQ −1.77%. AMAT BEAT MASSIVE AMC: EPS $2.86 VS $2.68, REVENUE $7.91B BEAT, RAISED 2026 SEMI-EQUIPMENT GROWTH GUIDE TO >30% FROM >20%. AMAT +8% AMC. NVDA +4.39% PRE-MARKET — AI CARRYING THE TAPE. 34 MACRO THURSDAY CLOSE: SPY 79 / QQQ 81 / XLK 81 / SMH 77 / CIBR 78 — CYBER TOOK #1 INDUSTRY. VIX +11.30% TO 19.20. POWELL’S TERM AS CHAIR ENDS TODAY.
The handoff has arrived under fire. Kevin Warsh takes the Fed chair today — Day 78 of Operation Epic Fury — into a global sovereign-bond rout that ranks as the cleanest single cross-asset signal of the week. Overnight, JGB 30-year traded at 4% for the FIRST TIME SINCE 1999 — a structural break in the decades-long Japanese yield-repression regime. UK 10-year sat near 5.14%, German 10-year added 7.5 bps to 3.12%, and US Treasury yields climbed in tandem: 30Y +7.0 bps to 5.10% (the second sustained breach of the 5.00% crisis threshold this week), 10Y +7.7 bps to 4.56% — the highest US 10Y print in nearly a year. Mohamed El-Erian flagged the move on social media this morning: “every maturity is rising at the same time,” driven by a 3-4% surge in oil prices with Brent hitting $109 intraday, combined with a hotter-than-expected Japanese PPI release. The bond market is repricing a coordinated G7 inflation pulse simultaneously with end-of-yield-repression in Japan. Stocks are absorbing the move but giving back yesterday’s war-high gains.
The metals tape is the cleanest mechanical signal of the positioning unwind. Silver crashed −8.43% — one of the steepest single-session silver moves in years; the cumulative move from war-low (SLV RLTV 0.60 zone) to peak (war-high silver at $87+) and now back to $78.13 is a brutal +/-30% round trip in three weeks. Copper crashed −5.10% to $6.27 — the global-demand-resilience anchor of the Leaders tier breaking on the synchronized G7 yields move. Platinum crashed −4.94%, Palladium −2.35%. Gold crashed −2.84% to $4,552 — gold is normally the inflation hedge on these moves, but the dollar bid (DXY 99.17, +0.40%) and the simultaneous global-yield ramp has overwhelmed the inflation tail. The metals coordinated crash is the most violent positioning-driven liquidation of the war series; it is NOT a fundamental risk-off (correlation across the tape remains near war lows), it is the inflation/reflation positioning that built since the post-NFP rally being unwound at speed.
And the day’s tactical lifeline is AMAT. Applied Materials reported AMC last night with a powerful beat: EPS $2.86 vs the $2.68 consensus (6.7% beat), revenue $7.91 billion vs $7.69 billion consensus (and 11.4% year-over-year growth), and gross margin of 49.9%. The critical commentary was the guide: management RAISED expected semiconductor-equipment industry growth in calendar 2026 to MORE THAN 30%, up from the prior “over 20%” guide issued in February. Q3 revenue guide $8.95 billion +/− $500M with non-GAAP EPS ~$3.36 — both above Wall Street’s run-rate models. AMAT was +8% AMC. NVDA $235.74 (+4.39%) is the leading Mag 7 print pre-market on the AMAT halo + the implicit AI capex confirmation. With SMH at Thursday-close STRNG 77 / MNTM +42 / RLTV 1.30 (still in war-high tier) and CIBR Cybersecurity now ranking #1 industry at STRNG 78 (surpassing SMH for the first time this war), the AI/Tech leadership trade has fresh thematic confirmation as the global bond rout unfolds.
The cross-asset internal split is dramatic. Mag 7 mixed: NVDA +4.39%, MSFT $409.43 (+1.04%) recovered yesterday’s −0.63% drag, META $618.43 (+0.29%) marginally green; AAPL $298.21 (−0.22%), TSLA $443.30 (−0.44%), GOOG $397.17 (−0.47%), AMZN $267.22 (−1.08%) all modestly red. The pre-market tape shows AI revenue-thesis Mag 7 names absorbing the bond shock while everyone else compresses. ES at 7,432.25 (−1.24%, −93 pts) gives back the bulk of Thursday’s war-high rally but still holds approximately +8.0% above pre-war 6,881.62 — the absolute war-high premium persists. Russell 2000 −1.63%, NQ −1.77% heavier. International tape brutal: Nikkei −2.13%, DAX −2.05%, EuroStoxx 50 −1.91% — the synchronized G7 yields move has hit every equity index. The dollar bid is broad: EUR −0.49%, GBP −0.48%, NZD −1.33%, AUD −1.10%, JPY −0.24%. BTC −1.24% to $80,610. The flight is not to typical risk-off havens — gold is selling, yen is selling, bonds are selling — it is to the dollar AND to AI revenue thesis equities. That is a very specific positioning signature.
The 34 Macro Thursday-close data captured the full reflation rally the day BEFORE this morning’s bond rout collapsed it. SPY baseline rose to STRNG 79 (from Wednesday’s 76 — a +3 STRNG move, the largest single-session SPY gain of the war series). QQQ jumped to STRNG 81 (from 79). XLK Technology rose to STRNG 81 / RLTV 1.17 — within four points of the war-high 85. SMH Semiconductor to STRNG 77 / RLTV 1.30 — back toward the war-high 82. The MAJOR development of Thursday’s close: CIBR Cybersecurity TOOK THE #1 INDUSTRY POSITION at STRNG 78 / RLTV 1.10 — surpassing SMH for the first time in the entire war series, the first industry-level leadership change at the top in over a month. Mag 7 closed broadly green in the cash session (consistent with the SPY +3 STRNG jump). XLF Financials recovered from STRNG 45 to 49 (+4) — partial healing of Wednesday’s −7 crack. But XLE Energy held at STRNG 53 / RLTV 0.98 — RLTV still BELOW baseline; the Energy Phoenix stalled even on a session where oil rallied. And FXI China gave back STRNG 66 → 53 (−13) on the Trump-China visit ending with no commitments. Silver (SLV) RLTV jumped to 1.02 (above baseline) at Thursday’s close — that entire RLTV move has been violently unwound this morning with the −8.43% crash.
The Number That Matters: JGB 30-Year At 4.00% For The First Time Since 1999 — Combined With UK Gilts Near 5.14%, German 10Y +7.5 BPS, And US 30Y Back To 5.10%. The Structural Japanese Yield Repression Regime Of A Generation Is Ending In Real Time. Coordinated With A 3-4% Oil Surge (Brent $109) And Hot Japan PPI. Every Maturity Is Rising At The Same Time. This Is The Global Sovereign-Bond Cross-Asset Inflection Of The War — Warsh Inherits It On His First Day.
This is the cleanest single regime statement of the war. The Federal Reserve’s leadership transition has arrived simultaneously with the end of three decades of Japanese yield-repression and a coordinated G7 inflation-pulse repricing. Warsh’s first day as chair drops directly into a global sovereign-bond rout that no domestic policy response can address in real-time. The dollar is bid (DXY 99.17). Yields are ripping (US 10Y at 1-year high, US 30Y back above 5.00%). Metals are crashing (Silver −8.43% is the single steepest metals print of the war). Trump’s China visit ended with no trade commitments. And against this — AMAT raised 2026 semi-equipment growth guide to >30%, NVDA is +4.39% pre-market, and the AI revenue thesis is the single floor under the equity tape. The week ends not with a Warsh-handoff celebration but with a cross-asset stress test of the soft-landing thesis that has prevailed since the post-NFP rally began Friday May 8.
The Setup: Bear Steepener — Global Sovereign Bond Rout — Warsh’s First Day. AMAT Beat Provides The AI Tactical Floor. Metals Coordinated Crash. International Equities Down 2% Across The G7. Watch The 30Y, The 10Y, The Yen, And NVDA. Powell’s Chair Term Ends Today; Stays On Board.
2. OVERNIGHT SESSION RECAP
Asia — Nikkei Crashed −2.13% On Hot Japan PPI / JGB 30Y At 4%
Nikkei 61,720 (−2.13%) — the largest single-session Nikkei decline since early in the war. TOPIX 3,863 (−0.48%) much less affected, indicating the cap-weighted exporter cohort took the brunt of the damage. The catalyst is unambiguous: Japan released hotter-than-expected PPI data overnight, and the 30-year JGB traded at 4% for the FIRST TIME SINCE 1999. This is a structural end-of-yield-repression signal that the Bank of Japan has been managing toward for two years. The JPY at −0.24% essentially flat despite the dollar bid — a counter-intuitive signal that the JGB selloff is functioning more like a real-yield re-rating than a currency stress event. AAXJ Asia ex-Japan at Thursday close STRNG 67 / RLTV 1.03 — held its post-Wednesday rebound. FXI China STRNG 53 — gave back Wednesday’s +9 STRNG gain (−13) on the Trump-China visit ending without trade commitments. The Asia tape ahead of the cash open is the single most negative international signal of the morning.
Europe — Synchronized G7 Yield Surge Hits DAX / EuroStoxx
DAX 24,001 (−2.05%) and EuroStoxx 50 5,811 (−1.91%) — both indices crashed on the synchronized global yields move. UK 10-year sat near 5.14% — the highest gilt yields in over a year, reflecting both the UK GDP beat from yesterday AND the global inflation-pulse repricing. German 10-year added 7.5 bps to 3.12% — German bunds, traditionally the steadiest in Europe, are participating in the rout. EUR 1.1637 (−0.49%) absorbing the dollar bid. GBP 1.3341 (−0.48%). The European session is delivering the cleanest “global sovereign bond rout” tape — UK gilts the loudest signal, German bunds the broadest confirmation, DAX absorbing the financial-conditions tightening. EU growth thesis is now in question heading into the weekend.
US Pre-Market — Bond Rout / Risk-Off, AMAT Halo Floors Tech
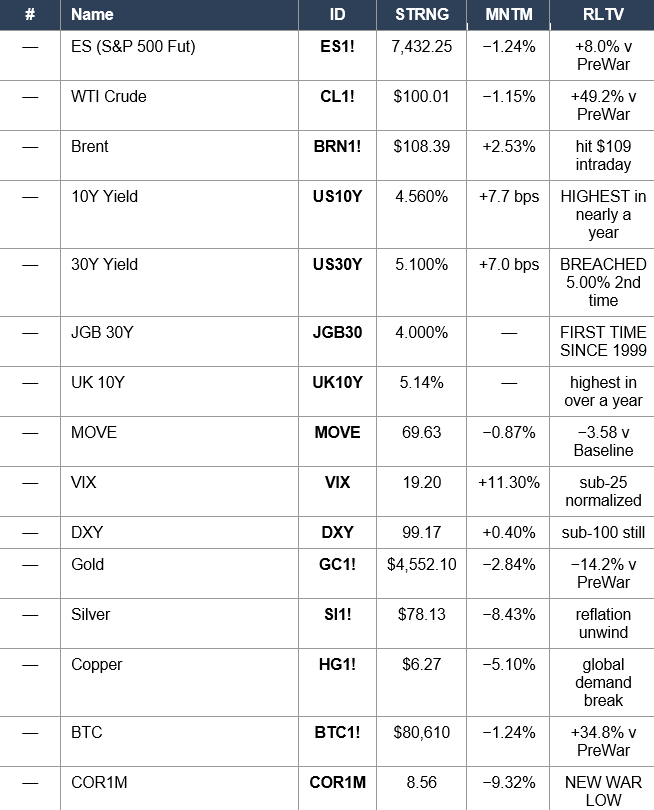
ES 7,432.25 (−1.24%, −93 pts) — the largest single-session ES pre-market drop in over two weeks. The market is giving back the bulk of Thursday’s rally but still holds approximately +8.0% above pre-war. NQ 29,162 (−1.77%) heavier on broader tech compression. RUT 2,822.50 (−1.63%) reflects the small-cap rate-sensitivity drag. Dow 49,673 (−0.96%) the lightest pull-back as defensive composition supports. Yields RIPPED across the curve: 2Y +5.8 bps to 4.073%, 5Y +7.7 bps to 4.226%, 10Y +7.7 bps to 4.560%, 30Y +7.0 bps to 5.100%. The Bear Steepener is the day’s most consequential rates signal — back to the curve configuration from Wednesday’s PPI shock, except today the 30Y is at 5.10% (Wednesday’s peak was 5.041%). Curiously, MOVE compressed −0.87% to 69.63 — rates VOL compressing even as rates LEVELS spike is the cleanest signal that this is an orderly positioning rotation, not a panic event.
Mag 7 Pre-Market — NVDA +4.39% Carries Tape, MSFT Recovers
NVDA $235.74 (+4.39%) — the leading Mag 7 print on the AMAT beat halo. AMAT raising 2026 semi-equipment growth guide to >30% from >20% is a structural confirmation of the NVDA AI capex demand thesis through Q3-Q4 2026; NVDA is functioning as the cleanest single-stock proxy for that thesis. MSFT $409.43 (+1.04%) — recovering Thursday’s −0.63% drag, the $190B capex narrative is softening on the AMAT confirmation. META $618.43 (+0.29%) marginally green. AAPL $298.21 (−0.22%), TSLA $443.30 (−0.44%), GOOG $397.17 (−0.47%) modest red. AMZN $267.22 (−1.08%) the heaviest Mag 7 decline. Aggregate weighted Mag 7 is approximately +0.4% — with NVDA carrying the entire complex single-handedly on AMAT halo. Without NVDA, the Mag 7 would be approximately −1% on the morning bond rout.
Sectors / Factors — Thursday Cash Rallied, Watch Today’s Open
The pre-market sector and factor numbers in the DYRH reflect Thursday’s closing tape rather than overnight futures — XLK +1.50%, XLE +0.76%, USMV +0.92%, MTUM +0.61%, VYM +1.03% all show the Thursday cash-session reflation rally that produced the SPY STRNG +3 jump. Today’s open will likely show the inverse: tech compressing on the bond rout (offset by NVDA strength), defensives mixed (rate-sensitive utilities and REITs the most exposed to the 30Y at 5.10%), and energy bouncing on the Brent $109 print. The cleanest factor-rotation watch into today’s open is whether MTUM Momentum (which has carried the post-NFP rally) can hold its gains, or whether the duration-driven multiple compression unwinds the momentum trade. SOXX +0.33% pre-market is modest — semis are not crashing despite the broader bond move, courtesy of AMAT.
Commodities — Brent Hit $109, WTI $100, Metals Coordinated Crash
Brent $108.39 (+2.53%) — hit $109 intraday at the European open; the petroleum complex bid is the cleanest global inflation impulse of the week. Heating Oil +2.71%, RBOB +1.58%, Natural Gas +1.55%. The reflation pulse confirmed by oil is what drove the Japanese PPI hot and the synchronized G7 bond rout. WTI $100.01 (−1.15%) somewhat counter-intuitively red — the WTI-Brent spread has widened to approximately $8 (typical wartime spreads are $2-4); this reflects WTI-specific positioning unwind alongside Brent’s structural bid. Metals are the day’s headline collapse: Silver $78.13 (−8.43%) — the single steepest silver session of the war. From war-low SLV RLTV 0.60 to peak war-high RLTV 1.02 (Thursday close), silver is now retracing 25%+ in one session. Copper $6.27 (−5.10%) crashing alongside; Copper has been the war’s most consistent global-demand-resilience signal, today’s break is structurally significant. Platinum −4.94%, Palladium −2.35%. Gold $4,552 (−2.84%) — gold should have been a haven bid into the bond rout but is selling. Softs and grains also red: Cocoa −3.99%, Cotton −3.31%, Wheat −1.60%, Soybeans −1.11%. The commodity tape is “every reflation trade unwinds at the same time.”
3. THE PRIOR DAY’S REGIME
34 Macro Price, Strength & Momentum Rankings — Daily Close, Thursday May 14. SPY Baseline: STRNG 79 | MNTM +10 | RLTV 1.00.
Asset Classes — Leaders
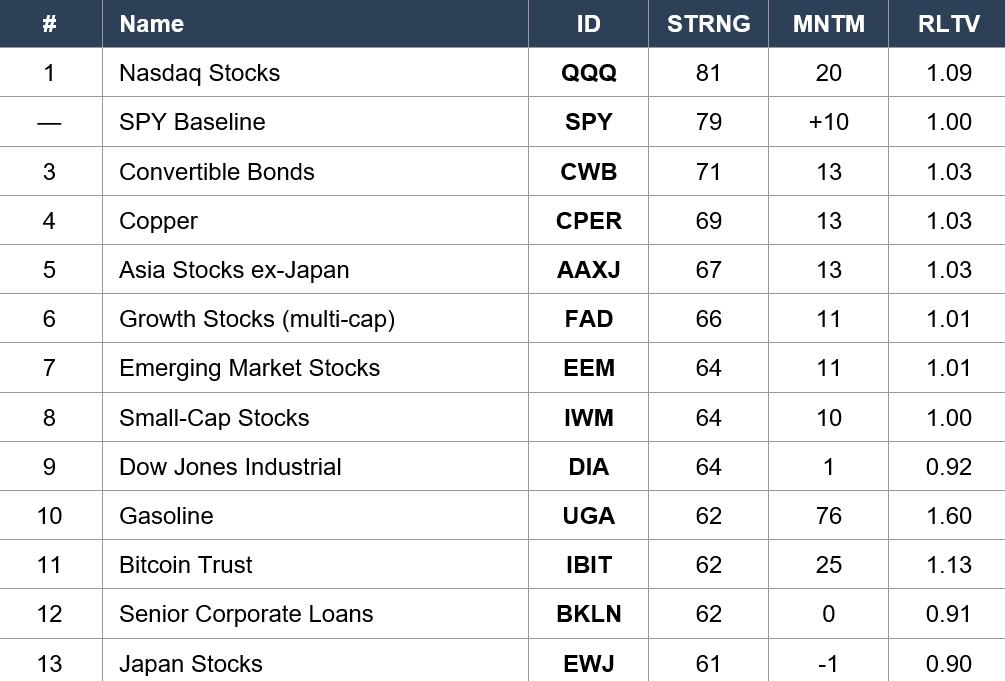
Asset Classes — Crude RLTV Re-Expanding / Silver Above Baseline / Bonds Lagging
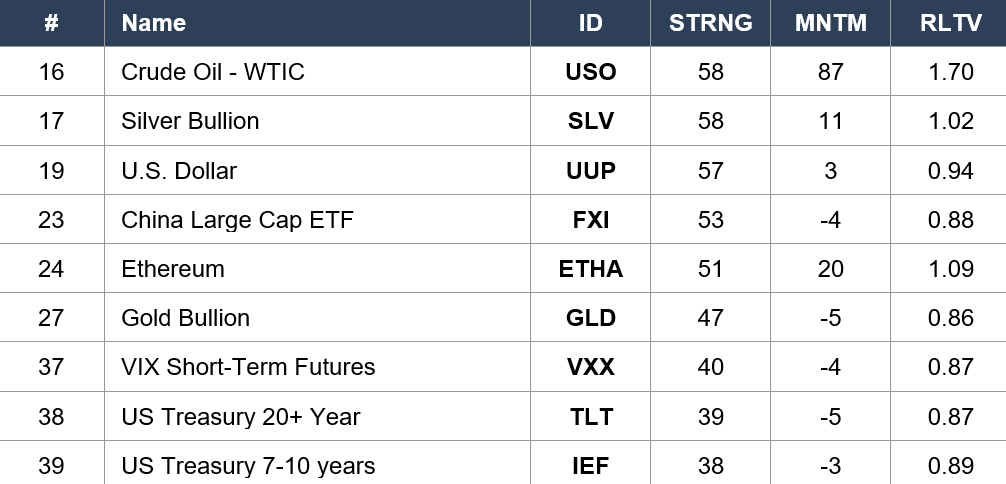
Regime signal: THURSDAY’S CLOSE WAS THE PEAK OF THE POST-NFP REFLATION RALLY — SPY baseline jumped from STRNG 76 to 79 (+3, the largest single-session SPY STRNG gain of the war series). QQQ Nasdaq surged to STRNG 81 (from 79) — the highest QQQ STRNG reading since the war-high regime. Copper (CPER) STRNG 69 / RLTV 1.03 — copper held Leaders-tier despite the +1.41% Thursday session that was unwound overnight. Asia ex-Japan (AAXJ) STRNG 67 — Asia leadership intact. Bitcoin (IBIT) jumped to STRNG 62 / RLTV 1.13 — crypto re-extending. Small-cap (IWM) recovered to STRNG 64 — Russell 2000 participation. The CRITICAL Crude / Silver development: USO Crude Oil RLTV expanded to 1.70 — re-approaching the 1.73 war-high reading. Silver (SLV) RLTV jumped to 1.02 from 0.97 — RLTV CROSSED ABOVE baseline at Thursday’s close, eliminating the war-low silver positioning completely. BOTH of these RLTV expansions have been violently unwound overnight: USO will retest 1.68, Silver will likely crash back below RLTV 0.95 on today’s −8.43% metals print. China FXI fell from STRNG 66 to 53 (−13) — Wednesday’s record FXI gain reversed completely on the Trump-China visit ending without trade commitments. VXX VIX futures at STRNG 40 / RLTV 0.87 — the fear bid has FULLY UNWOUND, consistent with the AMAT-driven AI thesis underwriting the tape.
Sector ETFs
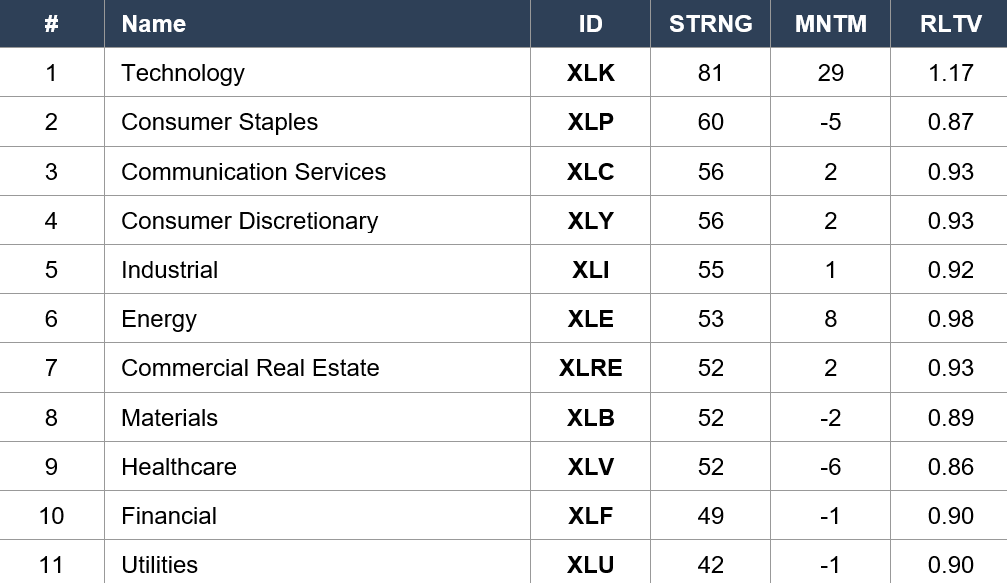
Regime signal: XLK TECHNOLOGY EXTENDED TO STRNG 81 / RLTV 1.17 — within FOUR POINTS OF THE WAR HIGH 85 from May 11. The tech leadership rebuilt completely from Wednesday’s STRNG 79 / RLTV 1.15. XLP Consumer Staples held #2 at STRNG 60 — defensives still bid in the broader Leaders rotation despite the risk-on tape. XLC Communication Services jumped to STRNG 56 (from 54) — GOOG’s +3.97% Thursday session lifting XLC. XLE Energy remained at STRNG 53 / RLTV 0.98 — RLTV STILL SUB-BASELINE despite WTI rallying and Brent above $107; the Energy Phoenix has STALLED. XLF Financials recovered from STRNG 45 to 49 (+4) — partial healing of Wednesday’s −7 crack, but financials still in the bottom half. XLU Utilities recovered to STRNG 42 (from war low 39) — defensive bid still present at the deep-laggard. XLV Health-Care at STRNG 52 — held but didn’t extend further. The sector tape captured the Thursday reflation: tech leading, defensives bid, financials healing, energy stalled. Today’s overnight bond rout will materially reshape this tape — XLU and XLRE rate-sensitives at risk on 30Y at 5.10%, XLE potentially bid on Brent $109, XLF facing duration risk.
Industry ETFs — Leaders (Cyber Took #1)
Industry ETFs — Laggers
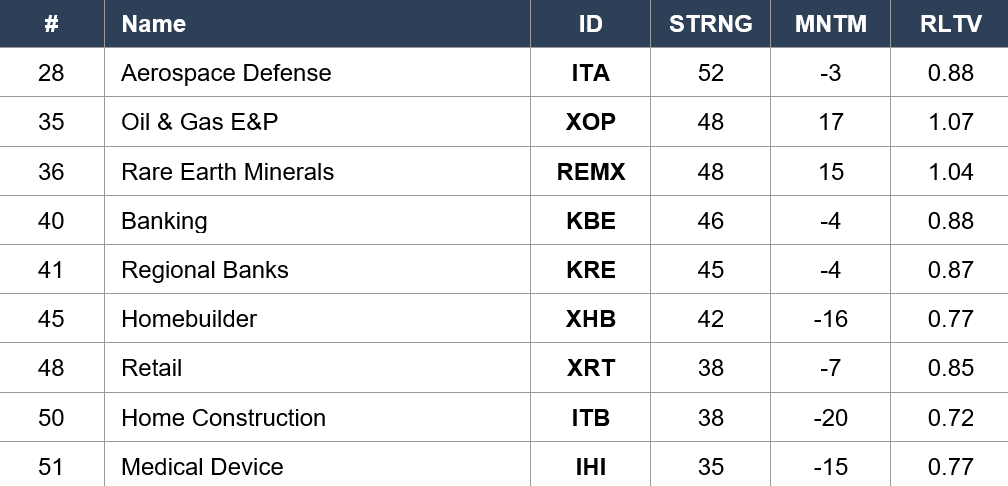
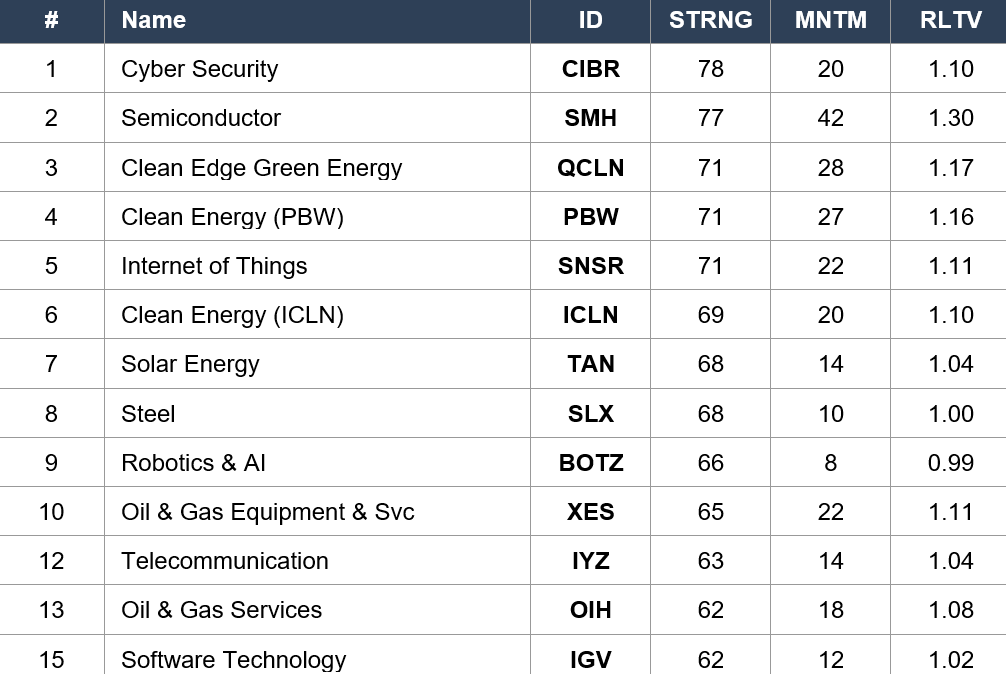
Regime signal: CIBR CYBERSECURITY TOOK THE #1 INDUSTRY POSITION FOR THE FIRST TIME IN THE WAR SERIES — STRNG 78 / RLTV 1.10. CIBR has now eclipsed SMH (STRNG 77 / RLTV 1.30) at the top of the industry ranking — this is the first leadership change at the #1 spot in over a month. The cyber bid is structural: geopolitical risk premium + AI-enabled cyber defense capex + the explosive Q1 enterprise cyber-spend trend captured in the CIBR ETF’s holdings. SMH at STRNG 77 / MNTM +42 / RLTV 1.30 — still in war-high tier ahead of AMAT earnings AMC (which subsequently beat, raised guide). The CLEAN ENERGY COMPLEX held: PBW STRNG 71, QCLN STRNG 71 (rank #3, NEW WAR HIGH for QCLN strength), ICLN STRNG 69 (#6), TAN STRNG 68 (#7), FAN at STRNG 54. SLX Steel held STRNG 68 (#8). XES Oil & Gas Equipment at STRNG 65 (#10) — energy services moving up. OIH Oil & Gas Services STRNG 62 (#13) — energy infrastructure leadership building. IGV Software jumped from STRNG 57 to 62 (rank #15) — software complex recovering. The Laggers tell the structural pain: REMX Rare Earth crashed STRNG 60 → 48 (−12) — global metals miners weakening. LIT Lithium STRNG 63 → 55 (−8 unwinding the Wed lithium rally). COPX Copper Miners 67 → 61 (−6) — copper miners giving back ahead of today’s copper −5.10% crash. ITA Defense STRNG 54 → 52 — defensive cohort softening on the Iran ceasefire stall priced. XHB Homebuilders STRNG 39 → 42 (+3) — modest recovery from war-low. ITB Home Construction STRNG 36 → 38 (+2) — also recovered modestly. KRE Regional Banks STRNG 41 → 45 (+4) — banks recovering from Wednesday’s XLF crack but still LAGGER tier. IHI Medical Devices STRNG 33 → 35 — modest healing from war low. The structural dispersion remains wide: AI/Cyber/Semis/Clean-Tech leading, while housing / retail / medtech / pharma at deep lows.
4. MORNING DATA REACTION
No US Economic Data Today — Catalysts Are International & Earnings-Driven
The DYRH calendar shows no major US economic data releases for today or the remainder of this week. The session catalysts are: (1) overnight Japan PPI (hotter than expected, driving JGB 30Y to 4% first time since 1999), (2) AMAT earnings AMC last night, (3) the global sovereign bond rout (UK gilts 5.14%, German 10Y +7.5 bps, US 30Y +7.0 bps to 5.10%), (4) the Brent oil surge to $109 intraday, and (5) Trump’s conclusion of his China visit with no firm trade commitments.
AMAT Earnings AMC — Massive Beat, 2026 Semi-Equipment Growth Guide Raised To >30%
Applied Materials reported Q2 fiscal 2026 results after market close yesterday: revenue $7.91 billion (vs $7.69B consensus, +11.4% y/y), EPS $2.86 (vs $2.68 consensus — a 6.7% beat), gross margin 49.9%, operating income $2.52B (31.9% margin). The Q3 guide is the standout: revenue $8.95 billion +/− $500M and non-GAAP EPS ~$3.36 +/− $0.20, BOTH ABOVE Wall Street’s run-rate models. The critical commentary from CEO Gary Dickerson: management RAISED expected semiconductor-equipment industry growth in calendar 2026 to MORE THAN 30%, up from the prior “over 20%” guide issued in February. Citing “the rapid global build-out of AI computing infrastructure” combined with leadership positions in leading-edge logic, DRAM, and advanced packaging. AMAT stock +8% AMC. Pre-market read: this is the structural confirmation of the AI capex cycle through 2H 2026 that NVDA, the broader SMH complex, and the AI services trade need. NVDA $235.74 (+4.39%) pre-market is the cleanest single-stock proxy for this thesis. If today’s open holds and SMH absorbs the bond move with limited damage, the AMAT halo carries the AI trade through Q3 earnings season.
Japan PPI — Hot Print Drives JGB 30Y To 4% First Time Since 1999
Japan released hotter-than-expected April PPI overnight. The data triggered an immediate JGB selloff that pushed the 30-year yield to 4% for the first time since 1999 — a structural break from the decades-long Japanese yield-repression regime that the Bank of Japan has been managing toward but had not yet reached. JPY at −0.24% essentially flat despite the dollar bid is the cleanest signal that the JGB move is being absorbed as a real-yield re-rating rather than a currency stress event. The Japan PPI / JGB 30Y at 4% combination is the proximate trigger for the synchronized G7 sovereign bond rout — capital flowing OUT of low-yielding international duration AND INTO the dollar simultaneously.
Trump-China Visit Concluded — No Firm Trade Commitments
President Trump concluded his high-stakes visit to China yesterday with no firm trade commitments announced. Pre-visit positioning had built around expectations of a tariff agreement, semiconductor export-control relaxation, and a tactical Iran-conflict de-escalation framework. None materialized. The Wednesday 34 Macro close had captured the optimistic pricing (FXI China jumped +9 STRNG to 66, the largest single-session FXI gain of the war); Thursday close fully unwound that bet (FXI back to 53, −13 STRNG). The combined message from the visit: the US-China relationship is in a holding pattern, no near-term diplomatic relief, and the oil-supply tail (Hormuz, Iran) remains contested. Bond traders are pricing this as “China relief trade is dead, oil supply risk persists, inflation pulse continues.”
Coming Up — Next Week
5. THE DYRH READ
Yield Curve Regime: Bear Steepener — Synchronized G7 Yields Surge
The curve flipped back to a Bear Steepener overnight: 2Y +5.8 bps to 4.073%, 5Y +7.7 bps to 4.226%, 10Y +7.7 bps to 4.560%, 30Y +7.0 bps to 5.100%. The 2s/30s spread expanded modestly to 102.7 bps. The Bear Steepener is the most bearish curve configuration for risk assets. Critically, this is the second Bear Steepener in three sessions (Wednesday’s was the post-PPI version peaking at 30Y 5.041%; today’s is the post-Japan-PPI / global-bond-rout version at 30Y 5.100%). The 30Y is now 10 bps above the crisis threshold — a more structural breach than Wednesday’s 4 bp print. The 10Y at 4.56% is the highest US 10Y print in nearly a year per the CNBC commentary. The synchronized G7 nature of the move (UK 10Y at 5.14%, German 10Y +7.5 bps to 3.12%, JGB 30Y at 4%) makes this a global-rates regime statement rather than a US-specific positioning event.
MOVE Index: 69.63 (−0.87%) — Compressing While Yields Rip (Unusual)
MOVE compressed −0.61 points to 69.63 — the SECOND consecutive session of rates-vol compression after the Day 74 → Day 76 expansion. The trajectory: 67.25 (war low) → 70.74 → 71.68 → 70.24 → 69.63. The MOVE is now back within striking distance of the war-low 67.25 reading, despite yields ripping +7-8 bps across the curve overnight. This MOVE-compressing-while-yields-rising configuration is structurally unusual — it typically signals that the yield move is ORDERLY and positioning-driven, not a panic re-rating. The bond market is repricing the inflation pulse as a LEVEL SHIFT rather than an expanding-risk regime. If MOVE crosses back below 68 by next week, the rates-vol absorption of the global rout will be the cleanest cross-asset bull signal for the equity tape.
S&P 500: ES 7,432.25 — Gives Back War-High Premium Modestly
ES at 7,432.25 (−1.24%, −93 pts) gives back yesterday’s war-high. The cumulative premium versus pre-war 6,881.62 is now approximately +8.0% — still a war-high regime, just not the peak. Thursday’s session closed with ES near 7,525 (the all-time war high in spot terms). The morning drawdown is structural — the 30Y at 5.10% and the global bond rout require multiple compression — but the bounded nature of the drawdown (−1.24%, not −2-3%) reflects the AMAT-NVDA-AI floor underneath. The 7,400 zone is the immediate technical level to watch; a break below 7,380 would signal the war-high regime is structurally challenged. A hold above 7,400 with NVDA leading into a strong close would confirm the bond rout is being absorbed as a one-day repositioning rather than a regime break.
Key Levels & Cumulative War Moves
Volatility & Breadth — VIX Up 11%, MOVE Compressing, COR1M New War Low
The day’s cleanest cross-asset divergence: VIX +11.30% to 19.20 (the largest single-session VIX expansion in over two weeks), but MOVE compressed −0.87% to 69.63 (the cleanest rates-vol calm signal). VIX1D +2.25% modest. VVIX −4.17% — vol-of-vol compressing. VXN −2.07%, GVZ Gold-Vol −2.90% compressing. The vol read tells the precise regime: EQUITY vol is bid on the bond shock and the AMAT-aside Mag 7 compression; RATES vol is calm because the move is orderly; CROSS-ASSET correlation continues to crash — COR1M at 8.56 is a NEW WAR LOW, the deepest stock-picker regime in the entire 78-day war. Breadth holds the constructive read: S5TH 70.10, S5FI 61.30, R2TH 51.20 — no degradation visible despite the headline drawdown. The vol + breadth + correlation read collectively says: this is a controlled positioning unwind, not a regime break.
6. THE GAME PLAN
Today: Warsh sworn in as Fed Chair. Global sovereign bond rout (JGB 30Y at 4% first since 1999, UK gilts 5.14%, US 30Y at 5.10%). Brent hit $109. Metals coordinated crash (Silver −8.43%). AMAT BEAT MASSIVE with raised 2026 guide >30%. NVDA +4.39% pre-market. ES −1.24% gives back Thursday’s war high. Powell’s chair term ends today, stays on board.
The Bull Case
AMAT delivered the structural AI capex confirmation through 2026: EPS beat, revenue beat, raised semi-equipment growth guide to >30% from >20%, Q3 guide above Wall Street models. NVDA +4.39% pre-market is the cleanest single-stock confirmation. With CIBR Cybersecurity now ranking #1 industry at STRNG 78 (eclipsing SMH for the first time in the war series) and SMH at STRNG 77 / RLTV 1.30 still in war-high tier, the AI/Cyber/Semis leadership trade has fresh thematic confirmation. MOVE compressed −0.87% to 69.63 EVEN WITH yields ripping +7-8 bps overnight — this MOVE-compressing-while-yields-rising configuration tells the cleanest possible “orderly positioning unwind, not panic” story. ES at 7,432.25 still +8.0% above pre-war — the war-high premium persists even after giving back Thursday’s peak. COR1M crashed to 8.56 — a NEW WAR LOW correlation, the deepest stock-picker regime of the entire 78-day war. 34 Macro Thursday close: SPY 79 (+3 STRNG jump, largest of the war), QQQ 81, XLK 81. XLF Financials recovered +4 STRNG from Wednesday’s crack. The metals crash unwinds the inflation/reflation overhang that has built since the post-NFP rally — paradoxically a constructive medium-term signal as it releases the duration risk. If the 30Y holds at 5.10% and doesn’t break to 5.15%+, MOVE continues compressing, and NVDA closes green on the AMAT halo, today’s bond rout becomes a one-day repositioning rather than a regime break. Warsh’s first day as chair arrives into a tape that has absorbed every shock the war has thrown at it.
The Bear Case
JGB 30-year at 4% for the FIRST TIME SINCE 1999 — a structural end of the decades-long Japanese yield-repression regime that has cascading global implications: the yen carry trade unwind, repatriation flows out of US Treasuries, and a permanent re-pricing of the global discount rate. UK 10Y at 5.14% — highest in over a year. German 10Y +7.5 bps. US 30Y at 5.10% — 10 bps above the crisis threshold and the second breach in three sessions. US 10Y at 4.56% — highest in nearly a year. The synchronized G7 sovereign bond rout is the most consequential cross-asset regime change of the entire 78-day war. Brent hit $109 intraday — oil supply tail re-engaging the inflation pulse. Trump-China visit ended with NO firm trade commitments — China relief trade dies (FXI gave back STRNG 66 → 53 / −13 in Thursday’s close). Metals coordinated crash: Silver −8.43% (single steepest of the war), Copper −5.10% (global-demand-resilience anchor breaking), Platinum −4.94%, Gold −2.84% (no haven bid even into bond rout — the dollar dominated). VIX +11.30% to 19.20 — single largest VIX expansion in two weeks. Europe crashed: DAX −2.05%, EuroStoxx −1.91%, Nikkei −2.13%. Mag 7 mixed with only NVDA carrying — without NVDA the Mag 7 is approximately −1%. XLE Energy still STRNG 53 / RLTV 0.98 sub-baseline despite Brent $109 — the Energy Phoenix has structurally stalled. Warsh inherits a global inflation pulse, a structurally higher US long-end, an FOMC stripped of Miran, an oil shock at $109 Brent, and a China relationship in stasis. His first FOMC June 16-17 is into the most challenging policy backdrop of any Fed chair transition in modern history.
Regime: Bear Steepener — Global Sovereign Bond Rout — Warsh’s First Day. The Japanese 30Y at 4% (first since 1999) is the cleanest single regime-altering signal of the war. Coordinated with UK gilts 5.14%, German 10Y +7.5 bps, US 30Y 5.10%, and Brent $109, the global inflation pulse has fully re-engaged. AMAT’s raised 2026 semi-equipment growth guide to >30% provides the AI thesis floor — NVDA carries the equity tape single-handedly. The week ends not with a Warsh-handoff celebration but with a cross-asset stress test of the soft-landing thesis at its most acute. Watch the 10Y, the 30Y, the yen, and NVDA into the close.
Watch List
Today — Warsh Sworn In As 11th Fed Chair, Powell’s Term Ends
Day 78 of Operation Epic Fury. Powell’s 8-year chair term officially ends today; Warsh sworn in. Powell remains on the Fed board until the renovation probe concludes — only the second time in nearly 80 years a Fed chair has stayed on the board. Warsh inherits: 30Y at 5.10%, 10Y at 4.56% (highest in nearly a year), MOVE compressing despite yields ripping, JGB 30Y at 4% (structural end of yield repression), Brent $109, AI capex thesis confirmed by AMAT, FOMC stripped of Miran (dovish dissent gone), and a China relationship in stasis. Warsh’s first FOMC is June 16-17. His commitments: trimmed-mean PCE replacement of headline PCE, limited Fed communications, smaller balance sheet, “regime change.” Watch for any Warsh statement at his swearing-in — historically Fed chairs say nothing on day one, but Warsh has been the most public Fed-chair-elect in modern history.
NVDA — The AI Tape Anchor On AMAT’s Raised Guide
NVDA $235.74 (+4.39%) pre-market on the AMAT halo. NVDA is the single-stock proxy for the AI capex thesis that AMAT just structurally confirmed (raised 2026 semi-equipment growth guide to >30% from >20%, Q3 guide $8.95B revenue / EPS ~$3.36 above run-rate). NVDA’s ability to hold the +4% gain through the cash session is the single highest-conviction read on whether the AI trade has decoupled from broader equity multiple compression. Watch: NVDA closes +3% or higher = AI thesis intact through Q3; NVDA fades to flat or red = AI/macro re-coupling, broader risk-off accelerates.
30Y Yield At 5.10% — Structural Crisis Threshold Breach
The 30Y has now breached 5.00% on two of the last three sessions and is at 5.10% — 10 bps above the threshold and the highest reading since Day 47-48 in late April. Combined with US 10Y at 4.56% (highest in nearly a year), the long-end of the curve is structurally repricing. Watch: 30Y holds 5.05-5.10% with MOVE staying compressed = orderly level-shift, the regime adjusts; 30Y breaks above 5.15% with MOVE expanding = full bond crisis re-engagement, equity multiple compression accelerates. The next Treasury auction calendar event is the 20-year on May 21 — that auction will be the cleanest stress test of demand at these yield levels.
JGB 30Y At 4% — Structural End Of Yield Repression
The Japanese 30-year bond yield traded at 4% for the first time since 1999 — a structural break from three decades of yield repression. The implications: (1) yen carry-trade unwind risk (any USD/JPY rally above 162 against this backdrop is now a stress signal), (2) Japanese institutional capital repatriation OUT of US Treasuries and INTO domestic JGBs (a structural demand headwind for the US long end), (3) global discount rate level-shift across all sovereign curves. Bank of Japan policy commentary into next week will be the single most consequential central bank signal. If BoJ leans hawkish (i.e., embraces the higher yields rather than pushing back), the JGB move accelerates.
Metals Crash — Reflation Positioning Unwound
Silver −8.43%, Copper −5.10%, Platinum −4.94%, Gold −2.84%, Palladium −2.35%. The coordinated metals crash unwinds the entire reflation positioning that built since the post-NFP rally (Day 71). Thursday close 34 Macro showed Silver SLV RLTV jumping to 1.02 (above baseline); today’s crash will likely push SLV RLTV back below 0.95. Copper (CPER) RLTV at 1.03 Thursday will compress toward 0.95-0.98. The metals unwind is paradoxically constructive for the rates outlook MEDIUM-TERM (releases inflation positioning) but structurally bearish for the global-demand resilience signal that copper provided. Watch GDX Gold Miners (Thursday close STRNG 51) for confirmation of the metals-equity equity break.
Energy — Brent $109 Intraday, XLE RLTV Still Sub-Baseline
Brent hit $109 intraday before settling at $108.39 (+2.53%). WTI counter-intuitively red at $100.01 (−1.15%) — the WTI-Brent spread has widened to approximately $8, reflecting WTI-specific positioning unwind alongside Brent’s structural geopolitical bid. The Thursday 34 Macro close showed XLE STRNG 53 / RLTV 0.98 — the Energy Phoenix STALLED at sub-baseline despite the oil rally. AMLP Midstream STRNG 58, XES Oil Equipment STRNG 65 — energy services/infrastructure outperforming upstream XOP (STRNG 48). Watch XLE pre-market today (DYRH showed +0.76% Thursday close); if XLE crosses above its 50-day MA on Brent $109 sustained, the Energy Phoenix finally fully re-engages.
China — FXI Gave Back Wednesday’s Rally, Trump Visit Without Commitments
FXI China fell from STRNG 66 (Wednesday close) to STRNG 53 (Thursday close) — a −13 STRNG reversal of Wednesday’s record gain. The catalyst: Trump’s China visit concluded without firm trade commitments. The post-visit positioning: US-China relationship in holding pattern, no near-term diplomatic relief, oil-supply tail (Hormuz, Iran) remains contested. BABA reports tonight — the cleanest single read on Chinese consumer / cloud / AI capex into next week. Watch BABA earnings and any post-visit US-China comments from either administration for the China trade restart signal.
Next Week — Quieter Data Week, Auction Calendar Matters
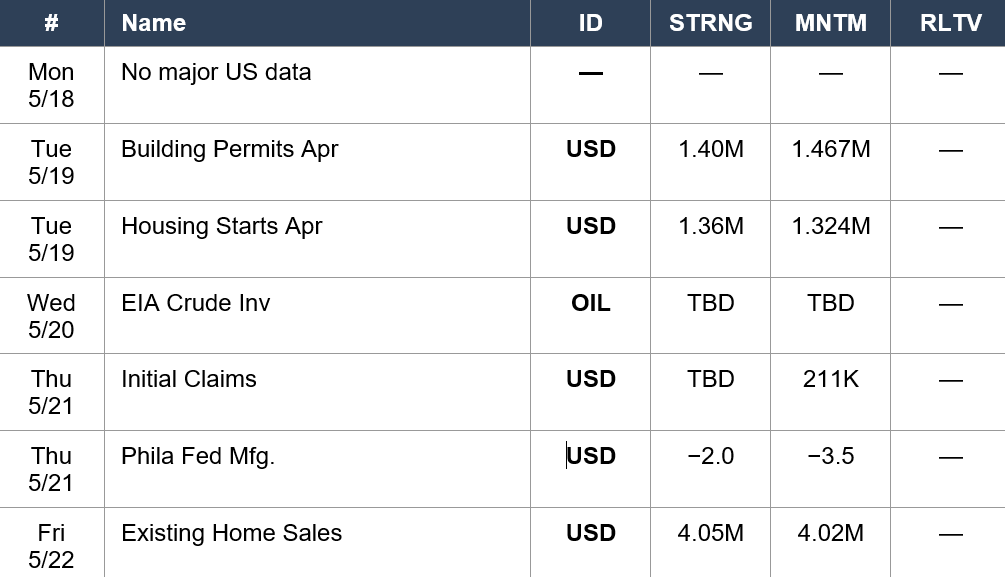
Tuesday May 19: Building Permits (1.40M cons) and Housing Starts (1.36M cons) — housing data into rate-sensitive ITB / XHB at war lows. Wednesday May 20: EIA Crude Inventories. Thursday May 21: Initial Jobless Claims (vs 211K prior) and Philly Fed Manufacturing. Friday May 22: Existing Home Sales. The 20-year Treasury auction on May 21 is the cleanest stress test of demand at these elevated yield levels — a tail at the auction would re-engage the 30Y above 5.15%. Watch BABA earnings tonight, plus any Warsh comments at the swearing-in or in his first weekend public appearances.
Morning check: Day 78. The handoff has arrived under fire. Kevin Warsh is sworn in as the 11th Fed chair today; Powell’s 8-year chair term ends. Powell stays on the Fed board until the renovation probe concludes — only the second time in nearly 80 years a Fed chair has remained on the board after stepping down. Warsh inherits the cleanest cross-asset stress test of the entire 78-day war. Overnight, the Japanese 30-year yield traded at 4% for the FIRST TIME SINCE 1999 — a structural end of three decades of yield repression. UK 10-year sat near 5.14% (highest in over a year). German 10-year added 7.5 bps to 3.12%. US 10-year +7.7 bps to 4.560% — the highest US 10Y print in nearly a year. US 30-year +7.0 bps to 5.100% — 10 bps above the crisis threshold, the second breach in three sessions. Mohamed El-Erian flagged the move this morning: “every maturity is rising at the same time.” The catalyst is a coordinated G7 inflation pulse driven by Brent hitting $109 intraday and hotter-than-expected Japanese PPI. Metals crashed in unison: Silver $78.13 (−8.43%, single steepest silver session of the war), Copper $6.27 (−5.10%, the global-demand-resilience anchor breaking), Platinum −4.94%, Palladium −2.35%, Gold −2.84% (no haven bid into the bond rout — dollar dominated). The reflation positioning that built since the post-NFP rally is being violently unwound. AMAT delivered the day’s tactical lifeline AMC last night: EPS $2.86 vs $2.68 consensus (6.7% beat), revenue $7.91B beat, and critically RAISED 2026 semi-equipment growth guide to MORE THAN 30% from the prior >20% guide. AMAT was +8% AMC. NVDA $235.74 (+4.39%) is the cleanest pre-market AI-thesis proxy. The 34 Macro Thursday close captured the peak of the post-NFP reflation: SPY baseline jumped to STRNG 79 (+3 from Wednesday’s 76, the largest single-session SPY STRNG gain of the war), QQQ to STRNG 81, XLK Technology to STRNG 81 / RLTV 1.17 (within 4 of war high 85), SMH STRNG 77. And the major Thursday-close development: CIBR Cybersecurity TOOK THE #1 INDUSTRY POSITION at STRNG 78 — the first leadership change at the top of the industry ranking in over a month, eclipsing SMH for the first time in the war series. ES at 7,432.25 (−1.24%) gives back Thursday’s war-high but still holds +8.0% above pre-war. NQ −1.77%, RUT −1.63%. Nikkei −2.13%, DAX −2.05%, EuroStoxx −1.91% — the synchronized G7 yields move has hit every equity index. Mag 7 mixed: NVDA +4.39% carries, MSFT +1.04% recovers, META +0.29% green; AAPL −0.22%, TSLA −0.44%, GOOG −0.47%, AMZN −1.08% red. VIX +11.30% to 19.20. MOVE compressed −0.87% to 69.63 — the second consecutive rates-vol compression, the cleanest signal that the bond move is ORDERLY (positioning, not panic). COR1M crashed to 8.56 — a NEW WAR LOW for correlation, the deepest stock-picker regime of the entire 78-day war. Trump-China visit ended without firm trade commitments; FXI gave back Wednesday’s +9 STRNG gain (66 → 53). Warsh’s first FOMC is June 16-17. His “regime change” agenda — trimmed-mean PCE, limited Fed comms, smaller balance sheet — arrives into the most challenging policy backdrop of any modern Fed chair transition. Markets are pricing about 1-in-3 chance of a rate HIKE by December. The week began with a war-high MOVE compression to 67.25; it ends with global sovereign bond rout and metals coordinated crash. Through every shock, the AI thesis has held — NVDA up nearly 5% on AMAT confirmation, SMH still in war-high tier, CIBR taking #1 industry. The bell rings on the most consequential single-day Fed handoff since 2018. Pressure, not panic. Regime, not reaction. The handoff is here, the bond rout is here, the AI thesis is the floor. The week ends.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.