

1. THE QUICK SCAN
Overnight Tape Summary: THE ACCELERATION. ES +0.32% TO 7,561.00 — NEW WAR-CYCLE HIGH (ABOVE PRIOR 7,544.75 SET TUE). NQ +0.86% TO 30,332.25 — ABOVE 30,000 FIRST TIME EVER. CUMULATIVE ES VS PRE-WAR +9.87% — NEW WAR-CYCLE PREMIUM. TUE CASH CLOSE: SPY 69→71 (+2), SMH STRNG 74 / RLTV 1.32 — NEW WAR-HIGH RLTV (ABOVE PRIOR 1.28); XLK STRNG 77 / RLTV 1.21 — NEW WAR-HIGH SECTOR RLTV (ABOVE PRIOR 1.19); CIBR HELD 83 / RLTV 1.26. CLEAN ENERGY COMPLEX FULLY ENGAGED IN TOP-10 (PBW 70/1.19, QCLN 69/1.18, ICLN 69/1.09, TAN 70/1.04). AMLP MIDSTREAM CRASHED −11 TO 49. XOP −7 / CRAK −3 / UGA −9. BOND COMPLEX EXTENDED (MUB +11, TIP +10, IEF +6, LQD +5). XLP STAPLES −8 (DEFENSIVE BID CRUSHED). PRE-MARKET TODAY: MOVE −4.44% TO 74.95 — APPROACHING PRE-WAR BASELINE 73.21 (NOW JUST 1.74 POINTS ABOVE). VIX1D −36.11% TO 11.13 — TOTAL HEDGE CAPITULATION. WTI −5.66% TO $88.58 — BROKE BELOW $90. BRENT −4.45% TO $92.37. CURVE REGIME SHIFT TO BULL STEEPENER. 30Y AT 5.003%, 10Y AT 4.465%. MAG 7: TSLA +1.78% / GOOG +1.44% LEAD; NVDA −0.22% ESSENTIALLY FLAT (6-SESSION FADE ENDING). XLK +2.63% MASSIVE LEAD / XLI +1.47% / XLB +1.39%; XLE −2.76% / XLP −1.38% / XLV −0.92% RED. VLUE VALUE +3.85% / MTUM +3.44% / SPHB +2.79% — MAJOR VALUE/MOMENTUM ROTATION. SOXX +6.10% MASSIVE (BROADER SEMI COHORT TAKES LEADERSHIP POST NVDA-DISCONNECT). NO MAJOR DATA TODAY. THU CORE PCE + PRELIM Q1 GDP 2ND EST = THE WEEK’S TEST.
The post-Friday May 15 bond shock cycle has now structurally accelerated into a multi-record breakout. ES at 7,561.00 (+0.32%, +24 pts) is a NEW war-cycle high, extending above Tuesday’s 7,544.75 reset. NQ 30,332.25 (+0.86%, +258 pts) is ABOVE 30,000 FOR THE FIRST TIME EVER — a structural psychological breakout. Cumulative ES vs pre-war 6,881.62: +9.87% — NEW war-cycle premium. The market has executed a textbook reflexive shock-absorption-extension cycle in 9 trading sessions: ES 7,488 (Fri 5/15) → 7,378 (Tue 5/19 low) → 7,544 (Tue 5/26) → 7,561 (Wed 5/27). The cumulative recovery from Tuesday May 19 low to today: +183 points / +2.48%.
Tuesday’s cash session delivered three new war-cycle high RLTV records simultaneously. SMH Semiconductor EXTENDED to STRNG 74 / RLTV 1.32 (+5 STRNG / +4 RLTV from Friday’s 69/1.28) — a NEW war-cycle high RLTV reading for any industry in the entire 90-day war series, surpassing the prior Friday May 22 reading of 1.28. SMH at RLTV 1.32 is positioned 32 percentage points above SPY baseline — the highest single-industry RLTV ever observed. XLK Technology EXTENDED to STRNG 77 / RLTV 1.21 (+4 STRNG / +2 RLTV from Friday’s 73/1.19) — NEW war-cycle high sector RLTV. CIBR Cybersecurity held STRNG 83 / RLTV 1.26 (the prior war-high). SNSR IoT extended +4 to STRNG 78 / RLTV 1.18. The CLEAN ENERGY COMPLEX FULLY ENGAGED IN TOP-10 INDUSTRY LEADERSHIP: PBW STRNG 70 / RLTV 1.19 (+4 from 66), QCLN 69 / RLTV 1.18 (+5 from 64), ICLN 69 / RLTV 1.09 (+3 from 66), TAN 70 / RLTV 1.04 (+5 from 65). The four major Clean Energy ETFs are now in the top-10 industry leadership cohort simultaneously — the cleanest possible “rate-relief + structural transition” thematic positioning of the war. SLX Steel +6 to 64, IYT Transport +6 to 63, JETS Airlines +6 to 63, KRE Regional Banks +5 to 59, ITA Aerospace Defense +5 to 59, XME Metals & Mining +8 to 58 — the broader cyclical and industrial complex SURGED Tuesday close.
And the bond market is delivering the structural confirmation. Tuesday cash close: 30Y −4.2 bps to 5.021%, 10Y −6.5 bps to 4.491%, 5Y −8.3 bps to 4.175%, 2Y −8.7 bps to 4.036% — full Bull Flattener. Today pre-market the curve REGIME SHIFTED to a Bull STEEPENER: 30Y −1.8 bps to 5.003%, 10Y −2.6 bps to 4.465%, 5Y −1.5 bps to 4.160%, 2Y −0.3 bps to 4.033%. The long end is now falling faster than the front end — the market is increasingly pricing long-run growth deceleration and disinflation rather than the previous front-end “Fed easing” framework. MOVE COMPRESSED −4.44% TO 74.95 — the SEVENTH consecutive session of MOVE compression. The cumulative MOVE trajectory: 86.07 (Tue May 19 peak) → 85.32 → 81.53 → 79.72 → 78.43 → 74.95 = −11.12 points / −12.9% across 5 trading sessions. MOVE at 74.95 is now JUST 1.74 POINTS ABOVE THE PRE-WAR BASELINE OF 73.21 — the structural rates-vol re-rating has not only fully absorbed but is now in pre-war normalized territory. The bond market is structurally signaling that the post-Friday May 15 shock is fully resolved.
The cleanest single equity-vol signal today: VIX1D −36.11% to 11.13 — short-dated equity hedges have FULLY CAPITULATED. VIX1D below 12 is rare and signals that the options market is no longer pricing tail risk; positioning has fully committed to the structural breakout. VVIX −1.77% to 89.55, VIX 16.79 (-1.24%), MOVE −4.44% to 74.95. The vol complex is in synchronized compression. The only countervailing vol reading is VXN +4.73% to 23.90 — Nasdaq-vol modestly bid (likely the post-NVDA single-name positioning hedge), but the broader vol tape is fully constructive. SKEW +1.20% to 139.04 — tail-risk hedging modestly building but at a slow pace. COR1M −6.96% to 10.16 — the lowest 1-month correlation reading of the war series; dispersion regime fully engaged, stock-picking dominant.
The Energy crack continues structurally. WTI −5.66% to $88.58 — broke below $90 to the $87-89 zone. Cumulative WTI move from war-high peak of ~$104 (Tue May 19): −$15+ / over −14%. Brent −4.45% to $92.37 — broke below $95. RBOB Gasoline −4.49%, Heating Oil −4.99% — refined products crashing in tandem. The geopolitical risk premium is fully unwound; the oil narrative has structurally compressed from “shortage / Hormuz disruption” to “ample supply / demand softening.” XLE Energy −2.76% pre-market — the worst sector. The Energy Phoenix that dominated Friday May 15 through Monday May 18 is now firmly in capitulation. Brent below $95 is the structural threshold — if Brent breaks below $90 this week, the energy thesis at the RLTV level (USO still 1.55, XES 1.04, OIH 1.01) will compress to baseline. The corollary: lower oil = lower inflation tail = Fed has structural cover to cut at June 16-17.
And the single most important Mag 7 signal today is NVDA stabilizing. NVDA at $214.86 (−0.22%) — essentially FLAT. After six consecutive sessions of decline (cumulative move from Friday May 15 pre-market $235.74 to $214.86 = −$20.88 / −8.85%), NVDA appears to have found a floor at $215 support. The “missed-whisper” Q2 guide reaction is structurally absorbing. Critically, the broader semis are taking leadership without NVDA: SOXX +6.10% pre-market — the LARGEST single-session SOXX pre-market lift in over four months. SMH RLTV at 1.32 war-high (Tuesday close) — the broader AI thesis has fully decoupled from NVDA-only concentration. If NVDA holds $215 today and SOXX continues to rip, the dispersion resolves into a healthier broader-semi-led rally. GOOG +1.44% pre-market — Google recovering above $384, the structural Mag 7 weak spot from the past week finally catching a bid. TSLA +1.78% extending. META +0.34%. MSFT -0.61% modest red, AMZN -0.39%, AAPL -0.16% near flat. The Mag 7 split: 3 green / 4 modest red — but the rotation tape (SOXX +6.10%, broader semis ripping) is the cleaner structural signal.
The Number That Matters: Tuesday Close Delivered Two NEW War-Cycle Records: SMH RLTV 1.32 (Industry War-High Above Prior 1.28) And XLK RLTV 1.21 (Sector War-High Above Prior 1.19). Today: ES At 7,561 NEW War-High / NQ Above 30,000 First Time Ever. MOVE −4.44% To 74.95 — JUST 1.74 Points Above Pre-War Baseline 73.21. VIX1D Capitulated To 11.13. WTI Broke Below $90 To $88.58. SOXX +6.10% — Broader Semi Rotation Takes Leadership.
This is the structural acceleration. The market has now executed a complete cycle: pre-war baseline → 89-day war pricing → mid-cycle compressions → post-Friday May 15 shock → resolution (last week) → extension (Tuesday) → acceleration (today). The MOVE just 1.74 points above pre-war baseline + Triple AI / Cyber / Tech leadership at maximum RLTV + ES at new war-high + NQ above 30,000 + VIX1D capitulated + oil capitulated + Bull Steepener curve + Value/Momentum/High-Beta factor leadership = the cleanest possible “post-shock reflexive risk-on extension” configuration of the entire war.
The Setup: THE ACCELERATION. ES NEW War-High 7,561 / NQ Above 30,000 First Ever / Cumulative +9.87% Above Pre-War. SMH RLTV 1.32 + XLK 1.21 — TWO NEW Tuesday War-Cycle Records. CIBR 1.26 Held. MOVE 74.95 Near Pre-War. VIX1D Capitulated. WTI Below $90. Energy Continued Crash. NVDA Finally Stabilizing. SOXX +6.10% Massive Broader Rotation. No Major Data Today. Thu PCE/GDP = This Week’s Key Test.
2. OVERNIGHT SESSION RECAP
Asia — Nikkei -0.19% Modest Red (Post-Ueda Digestion)
Nikkei 65,515 (−0.19%) modest red after Tuesday’s massive +3.47% surge — BoJ Gov Ueda last night delivered a constructive, gradual-yield-management-continuation message (no hawkish surprise, no acceleration signal). The market read the speech as “as-expected dovish-relative-to-feared-hawkish” — which allowed Nikkei to digest yesterday’s explosive gains rather than extend. TOPIX 3,926 (+0.27%) modest green. The broader Japan equity narrative is fully constructive after the structural absorbing of the May 15 JGB shock. JPY essentially flat. AAXJ Asia ex-Japan Tuesday close STRNG 65 / RLTV 1.02 (+8 from prior 57) — Asia ex-Japan EXPLODED higher. EEM Emerging Markets +8 to STRNG 64 / RLTV 1.00 — EM at baseline. FXI China STRNG 41 / RLTV 0.85 (+3) — China stabilizing modestly.
Europe — DAX +0.40% / EuroStoxx +0.81% Catching Up
EuroStoxx 50 6,122 (+0.81%) extending — European indices catching up to the US-led breakout. DAX 25,349 (+0.40%) modest green. ECB Financial Stability Review released at 4:00 AM — no major market impact, routine institutional update. EUR 1.1669 (+0.24%) modestly bid, GBP 1.3453 (+0.07%) flat — both currencies modestly green as DXY breaks below 99. The European narrative remains constructive on cooling UK CPI + Eurozone PMIs softening + BoE potentially easing in late summer.
US Pre-Market — ES At NEW War-High; NQ Above 30,000 First Ever
ES 7,561.00 (+0.32%, +24 pts) — NEW war-cycle high, extending above Tuesday’s 7,544.75 reset. NQ 30,332.25 (+0.86%, +258 pts) — ABOVE 30,000 FOR THE FIRST TIME EVER, a structural psychological breakout. RUT 2,940.80 (+0.54%) extending — small caps continuing to participate in the broad rally. Dow 50,628 (+0.16%) modest. Cumulative ES vs pre-war 6,881.62: +9.87% — NEW war-cycle premium. The technical levels: ES has cleared the 7,540 measured-move target; next resistance 7,580 (cycle technical extension), 7,620 (next major). Support at 7,540 (the prior war-high becomes support), 7,495 (last week war-high). NQ above 30,000 sets up a clean run at 30,500 with no significant resistance.
Mag 7 Pre-Market — TSLA / GOOG Lead; NVDA Finally Stabilizing
TSLA $433.59 (+1.78%) — Tesla extending decisively above $430, the structural Tesla compression from mid-May fully absorbed. GOOG $384.84 (+1.44%) — Google FINALLY RECOVERING after the prior week of fading; back above $384. META $612.34 (+0.34%) modest green, marginal but positive. AAPL $308.33 (−0.16%) near flat. NVDA $214.86 (−0.22%) — ESSENTIALLY FLAT. After six consecutive sessions of decline (cumulative move from Friday May 15 pre-market: $235.74 → $214.86 = −$20.88 / −8.85%), NVDA appears to have found a floor at $215 support. The 6-session NVDA fade may be ENDING. The “missed-whisper” Q2 guide ($91B vs $96.78B Wall Street model) is structurally absorbed. AMZN $265.29 (−0.39%) modest red. MSFT $416.03 (−0.61%) — Microsoft continues to weaken modestly. The Mag 7 split: 3 green / 4 red — but importantly, NVDA has stopped bleeding and GOOG has finally turned. The broader rotation (SOXX +6.10%) is taking leadership beyond cap-weighted Mag 7.
Sectors — XLK +2.63% MASSIVE LEAD; XLE −2.76% / XLP −1.38% / XLV −0.92% RED
XLK Technology +2.63% MASSIVE LEAD — the largest single-day XLK pre-market lift in over 6 weeks; semiconductor-led broad tech rally. XLI Industrial +1.47% — Industrial extending Tuesday’s recovery. XLB Materials +1.39%. XLRE Real Estate +0.34%, XLY Consumer Discretionary +0.23%, XLC Communication Services +0.08%. XLU Utilities −0.04% near flat. XLF Financials −0.17% modest red. XLV Health-Care −0.92% — Health Care continuing to compress after Tuesday’s −5 STRNG decline. XLP Consumer Staples −1.38% — defensive bid CRUSHED, continuing Tuesday’s −8 STRNG defensive unwind. XLE Energy −2.76% — the worst sector by far on the WTI −5.66% crash. Sectors split: 6 green / 5 red — but the leadership XLK +2.63% is overwhelming the defensive/energy compression.
Factors — VLUE +3.85% / MTUM +3.44% / SPHB +2.79% — Major Value Rotation
VLUE Value +3.85% LEADS factors — the LARGEST single-session Value factor lift in over 8 weeks. MTUM Momentum +3.44% — Momentum factor surging. SPHB High-Beta +2.79% — high-beta extending. IJR Small-Cap +1.59%, IJH Mid-Cap +1.56% — broad small-mid cap participation. LRGF Multi-Factor +0.71%, QUAL +0.66%, RSP Equal-Weight +0.51%. DEFENSIVES RED: VYM −0.01% flat, SPLV −0.28%, DGRO −0.32%, USMV −0.40%. The factor configuration: 8/12 green, 4/12 red — but ALL FOUR RED ARE DEFENSIVES. This is the cleanest possible “reflationary risk-on rotation” factor tape of the entire war. The defensive cohort is decisively unwinding into the broad cyclical/growth/value rally.
Thematics — SOXX +6.10% MASSIVE; ICLN Extending
SOXX Semiconductor +6.10% — the LARGEST single-session SOXX pre-market lift in over four months. The broader semi cohort (AMAT, AVGO, AMD, MU, TXN, ON) is decisively taking leadership beyond NVDA-only concentration. SMH RLTV at war-high 1.32 (Tuesday close) confirms the structural positioning. DRIV Autonomous & EV +3.11%, ARKQ Autonomous Tech +2.50%, PAVE Infrastructure +2.49%. ICLN Clean Energy +2.32% — extending Tuesday’s structural surge. ARKG Genomic +2.05%, ITA Aerospace Defense +1.83% (defense waking up), BLOK Crypto-related +1.81%. ARKW Next-Gen Internet +0.52% modest. FINX FinTech +0.29% near flat. CIBR Cybersecurity +0.24% modest — CIBR is consolidating at the war-high (Tuesday close 83/1.26) but NOT extending. The thematic tape: SOXX massive lead, autonomous + clean energy + defense all participating, CIBR consolidating.
Commodities — WTI Broke Below $90; Metals RED
WTI $88.58 (−5.66%) — the major commodity story. WTI BROKE DECISIVELY BELOW $90 to the $87-89 zone. Cumulative WTI move from war-high $104+ peak (Tue May 19) to today: −$15+ / over −14%. Brent $92.37 (−4.45%) — Brent broke below $95. RBOB Gasoline −4.49%, Heating Oil −4.99%, Ethanol −1.84% — refined products crashing in tandem. Natural Gas $3.045 (+5.22%) — Nat Gas bounce back, the lone energy commodity green. The energy complex is in clean capitulation: crude + refined + ethanol all down 4-6%. METALS ALL RED: Gold $4,449 (−1.18%) — gold continuing to FAIL TO RALLY despite weaker dollar (DXY 98.91 −0.16%, below 99). The gold divergence flagged through this whole week has now confirmed structurally — gold is positioning under pressure. Silver −2.27%, Platinum −1.06%, Palladium −0.09%. Copper $6.376 (−0.34%) modest red. Softs MIXED: Cocoa +0.67%, Lumber +0.26%; Sugar −1.86%, Orange Juice −2.17%, Coffee −0.82%. Wheat −1.81% notable decline; Corn −0.71%, Soybeans −0.38%, Soybean Meal +0.15%. Livestock all modest red.
3. THE PRIOR DAY’S REGIME
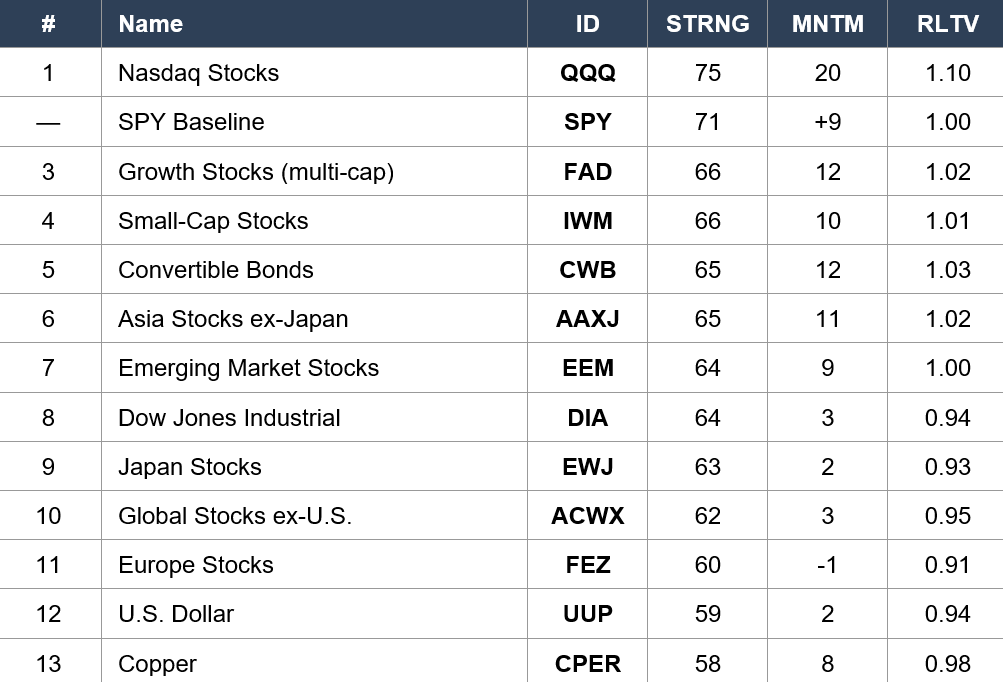
34 Macro Price, Strength & Momentum Rankings — Daily Close, Tuesday May 26. SPY Baseline: STRNG 71 | MNTM +9 | RLTV 1.00. SPY +2 STRNG vs Friday — Continued Extension.
Asset Classes — Leaders (International Equities ROARED; Bonds Extended Big)
Asset Classes — Bonds Extending; Energy Continues Crack; UGA Crashed −9
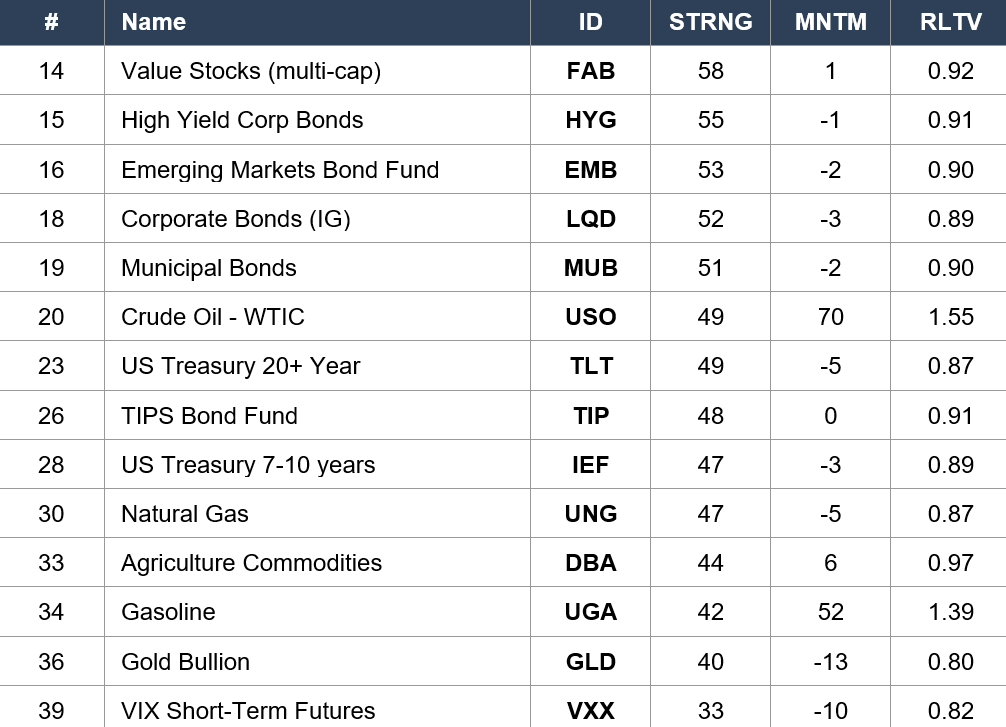
Regime signal: TUESDAY DELIVERED A MASSIVE BROAD-BASED EXTENSION. SPY baseline +2 to STRNG 71. QQQ +4 to STRNG 75 / RLTV 1.10 — Nasdaq leadership extending toward war-high zone. The INTERNATIONAL EQUITY COMPLEX ROARED: AAXJ Asia +8 to STRNG 65 / RLTV 1.02, EEM Emerging Markets +8 to STRNG 64 / RLTV 1.00 (baseline), ACWX Global +6 to STRNG 62, EWJ Japan +5 to 63 (pre-Ueda positioning), FEZ Europe +4 to 60. IWM Small-Cap +5 to STRNG 66 / RLTV 1.01 — small caps NOW ABOVE BASELINE for the first time since mid-April. FAD Growth +5 to 66 / RLTV 1.02. FAB Value +1 to 58. CWB Convertibles +3 to 65. THE BOND COMPLEX MASSIVELY EXTENDED: MUB Munis +11 to STRNG 51 (huge), TIP +10 to 48 (TIPS surged on disinflation positioning), IEF 7-10Y +6 to 47, LQD Corporate +5 to 52, SHY 1-3Y +5 to 47, HYG High Yield +5 to 55, EMB EM Bonds +5 to 53, MBB Mortgage +3 to 49, TLT 20+Y +4 to 49. The bond complex extension is +5 to +11 STRNG across every duration — second consecutive week of cumulative double-digit bond ETF gains. THE ENERGY COMPLEX CONTINUED TO COMPRESS: USO Crude STRNG 52 → 49 (−3) / RLTV 1.55 (still above 1.00 but trending lower), UGA Gasoline CRASHED 51 → 42 (−9 — RLTV 1.39, still above baseline but compressing aggressively), UNG Natural Gas held 47. DBA Agriculture −1 to 44. UUP Dollar −1 to 59 (DXY weakening). IBIT Bitcoin Trust held 45 (crypto stable). VXX VIX Futures compressed to STRNG 33 (vol crushed). PPLT Platinum +3 to 45.
Sector ETFs (XLK STRNG 77 / RLTV 1.21 NEW WAR-HIGH; XLP/XLV/XLE All Compressed)
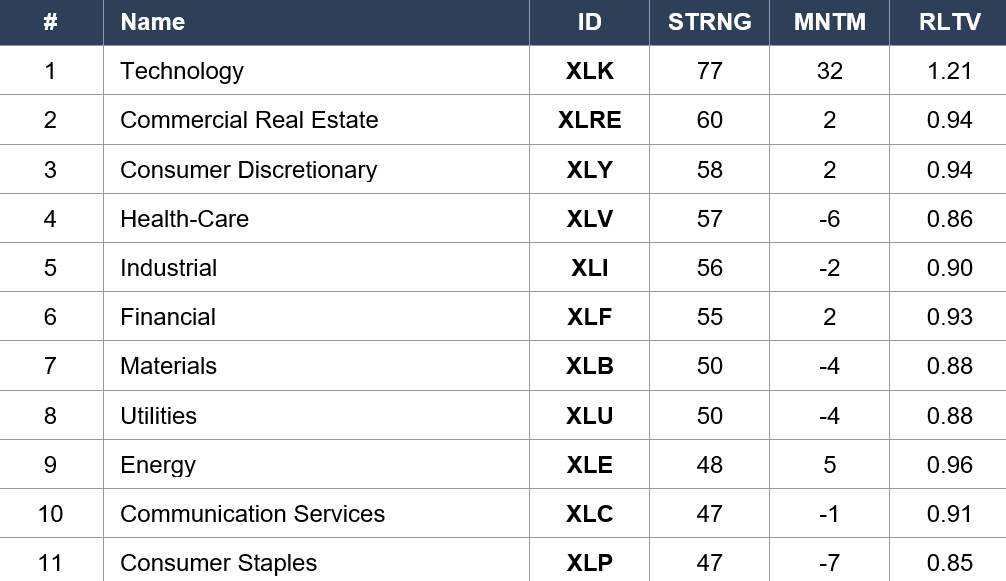
Regime signal: TUESDAY DELIVERED A NEW WAR-CYCLE HIGH XLK RLTV READING. XLK Technology EXTENDED from STRNG 73 → 77 (+4) / RLTV 1.19 → 1.21 — NEW WAR-CYCLE HIGH RLTV FOR THE TECHNOLOGY SECTOR. XLK at RLTV 1.21 is now positioned 21 percentage points above SPY baseline — the highest XLK reading ever observed in the entire 90-day war series. XLRE Real Estate +1 to STRNG 60. XLY Consumer Discretionary +1 to STRNG 58. XLI Industrial SURGED from STRNG 50 → 56 (+6) — Industrial recovering aggressively, the largest single-session XLI lift in over six weeks. XLF Financials −1 to STRNG 55 (modest compression after Friday’s extension). XLB Materials +5 to STRNG 50 (back at baseline). XLU Utilities −1 to STRNG 50 (modest compression after the recent surge). THE DEFENSIVE/ENERGY COMPRESSION: XLV Health-Care CRASHED from STRNG 62 → 57 (−5 — the defensive Health Care bid unwound aggressively after the Friday surge), XLP Consumer Staples CRASHED from STRNG 55 → 47 (−8 — the LARGEST single-session XLP STRNG decline in over six weeks; defensive bid fully crushed), XLE Energy CRASHED from STRNG 55 → 48 (−7 — energy continuing the multi-session crash; lost above-50 zone). XLC Communication Services held STRNG 47 (−0). The sector configuration: XLK at NEW war-high RLTV 1.21, broad cyclical participation (XLI +6, XLB +5, XLY +1), defensive and energy decisively unwinding (XLP −8, XLE −7, XLV −5).
Industry ETFs — Leaders (SMH RLTV 1.32 NEW WAR-HIGH; Clean Energy Top-10)
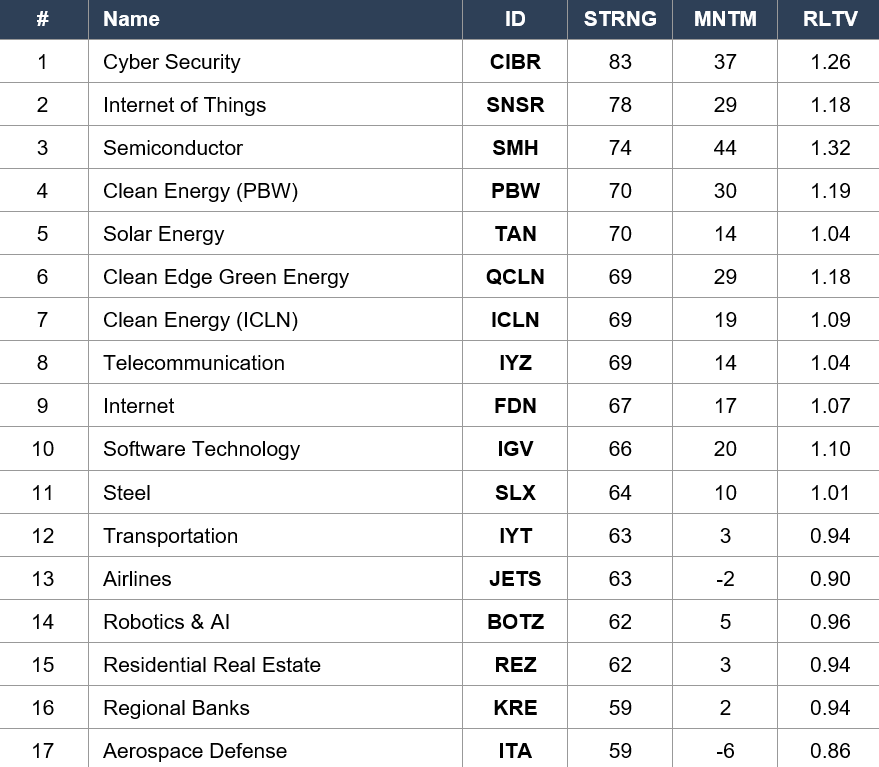
Industry ETFs — Notable Movers / Laggers (AMLP Crashed −11; XOP Continues)
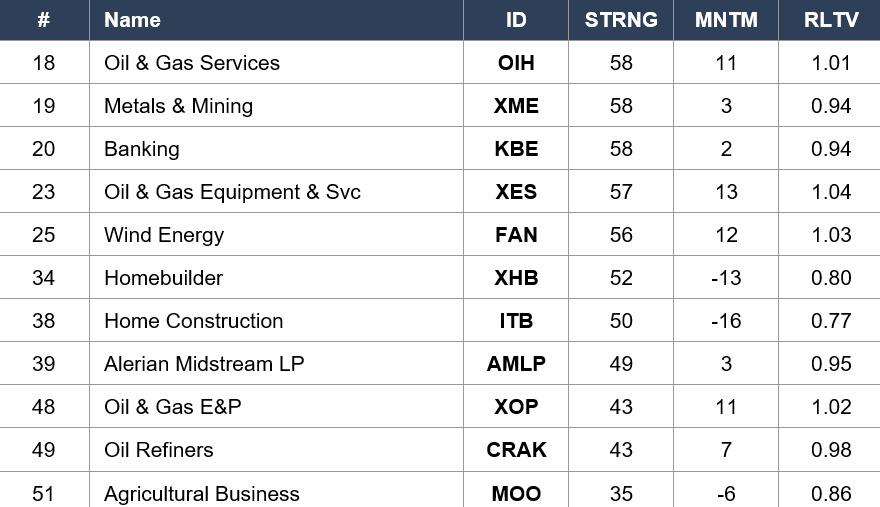
Regime signal: TUESDAY DELIVERED THE THIRD CONSECUTIVE WEEK OF MAJOR INDUSTRY-LEVEL RECORDS. SMH SEMICONDUCTOR EXTENDED FROM STRNG 69 → 74 (+5) / RLTV 1.28 → 1.32 — NEW WAR-CYCLE HIGH RLTV FOR ANY INDUSTRY. RLTV 1.32 is now the highest single-industry positioning reading ever observed in the entire 90-day war series. SMH is positioned 32 percentage points above SPY baseline. The broader semi cohort (AMAT, AVGO, AMD, MU, TXN, ON) is taking decisive leadership — the AI infrastructure thesis at the index level is at its absolute peak engagement. SNSR IoT EXTENDED from STRNG 74 → 78 (+4) / RLTV 1.16 → 1.18 — IoT secondary leadership extending. CIBR Cybersecurity held STRNG 83 / RLTV 1.26 (the prior war-high RLTV; CIBR is consolidating at the cycle peak). IYZ Telecommunication +1 to STRNG 69 / RLTV 1.04 (held). FDN Internet held STRNG 67 / RLTV 1.07. IGV Software held STRNG 66 / RLTV 1.10. THE CLEAN ENERGY COMPLEX MASSIVELY EXTENDED INTO TOP-10 LEADERSHIP: PBW Clean Energy STRNG 66 → 70 (+4) / RLTV 1.15 → 1.19, TAN Solar 65 → 70 (+5) / RLTV 1.00 → 1.04, QCLN Clean Edge 64 → 69 (+5) / RLTV 1.15 → 1.18, ICLN Clean Energy 66 → 69 (+3) / RLTV 1.08 → 1.09. All four major Clean Energy ETFs are now in the top-10 industry leadership cohort simultaneously — the first time this has occurred in the entire 90-day war series. THE BROADER CYCLICAL COMPLEX SURGED: SLX Steel +6 to 64 / RLTV 1.01 (back above baseline), IYT Transport +6 to 63, JETS Airlines +6 to 63 (extending the Wednesday +13 STRNG move), BOTZ Robotics +3 to 62, KRE Regional Banks +5 to 59, KBE Banking +4 to 58, ITA Aerospace Defense +5 to 59 (defense waking up after weeks of compression), XME Metals & Mining +8 to 58, COPX Copper Miners +6 to 57. FAN Wind +5 to 56 / RLTV 1.03. PEJ Leisure +5 to 58, MSOS Cannabis +6 to 52. XHB Homebuilder +5 to 52, ITB Home Construction +3 to 50 (back at baseline). THE ENERGY COMPLEX CONTINUED TO CRACK: AMLP Midstream CRASHED from STRNG 60 → 49 (−11 — the LARGEST single-session AMLP STRNG decline of the entire war series; Midstream broke below baseline for first time since Day 60), XOP Oil & Gas E&P −7 to STRNG 43 (continuing the multi-session crack), CRAK Oil Refiners −3 to 43, XES Oil Equipment −1 to 57, OIH Oil Services −1 to 58. All energy-services/infrastructure/upstream industries now structurally compressing. PPH Pharma compressed −4 to 58 (defensive Health Care bid unwinding).
4. MORNING DATA REACTION
BoJ Gov Ueda Tuesday Night 8PM ET — Constructive, Gradual
BoJ Gov Ueda delivered his speech Tuesday night at 8:00 PM ET. The market read it as constructive — “gradual yield management normalization, no acceleration signal, no hawkish surprise.” Nikkei opened −0.19% today, modest digestion after Tuesday’s +3.47% explosive move (which positioned for a worse Ueda outcome). The Japan equity narrative is now structurally constructive: Ueda signal supports continued gradual yield path; JGB 30Y at 4% area is sustainable; cap-weighted exporters have absorbed the May 15 shock. No major Japan-specific positioning concern remains.
Today — Light Data; ECB Financial Stability Review Released 4 AM
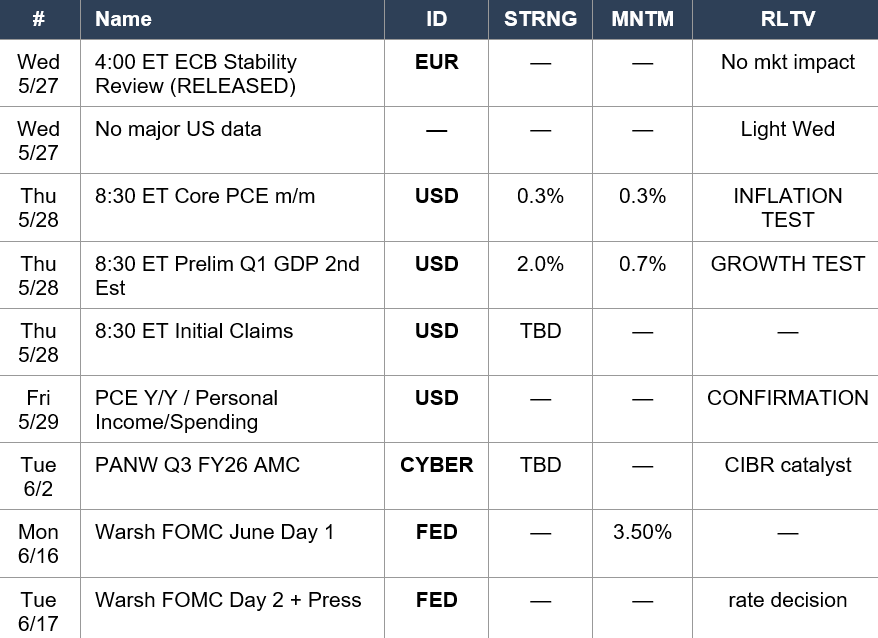
The ECB Financial Stability Review released at 4:00 AM ET. No major market impact — routine institutional update on European financial system risks. No major US data scheduled for today. The market is in consolidation/extension mode ahead of Thursday’s key Core PCE + Q1 GDP 2nd Estimate prints. The light-data Wednesday allows positioning to digest the multi-record breakout and reset for the Thursday catalysts.
Thursday 8:30 ET — Core PCE m/m (Cons 0.3%) + Prelim Q1 GDP 2nd Estimate (Cons 2.0%)
The week’s key tests come Thursday 8:30 ET. Core PCE m/m at 0.3% consensus vs 0.3% prior — the structural test of whether US inflation continues to cool. With UK CPI cooled to 2.8% + Canadian CPI all-four-measures cooler + WTI at $89 (vs war-high $104) + Brent at $92 (vs war-high $112), the US Core PCE has substantial structural setup to print at or below cons. A print at 0.2% would be the cleanest possible “Fed can cut at June 16-17” signal — pushes 30Y toward 4.90%, accelerates risk-on. A print at 0.4% engages persistent-inflation re-engagement narrative. PRELIM Q1 GDP 2nd estimate at 2.0% consensus vs 0.7% prior (Advance estimate) — a substantial upward revision of approximately 130 bps would be a meaningful confirmation of structural growth resilience. A 2.5%+ GDP print extends the soft-landing thesis; below 1.5% engages broader slowdown narrative. Watch the inventories subcomponent — a positive inventory contribution could explain the upward revision without genuine demand strength.
Rest Of Week
5. THE DYRH READ
Yield Curve Regime: Bull Steepener — Curve Regime SHIFTED
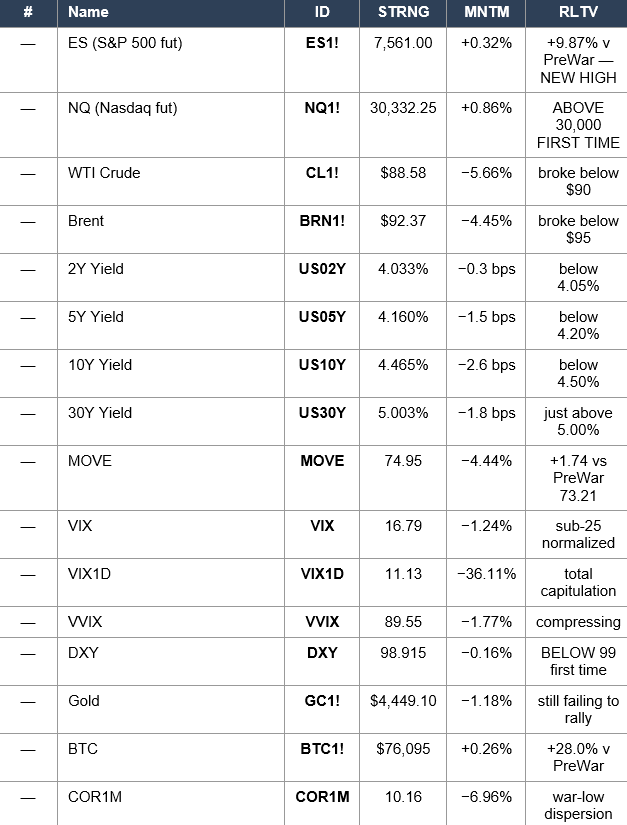
The curve regime SHIFTED overnight from Bull Flattener (Friday-Tuesday) to Bull STEEPENER today. Pre-market: 2Y −0.3 bps to 4.033%, 5Y −1.5 bps to 4.160%, 10Y −2.6 bps to 4.465%, 30Y −1.8 bps to 5.003%. The long end is falling FASTER than the front end — the inverse of the prior week’s Bull Flattener. The Bull Steepener regime emerges when the market is pricing long-run growth pessimism and disinflation (long-end rallying on growth-deceleration concerns) rather than front-end Fed-easing-anticipation. This is structurally CONSISTENT with the recent global growth-deceleration signals: Philly Fed −0.4 last Thursday + Eurozone Mfg PMI below 50 + UK Services PMI 47.9 + UK Retail Sales −1.3%. The bond market is now pricing the slowdown as the dominant narrative — the Fed-hike fear is fully dead, and the Fed-cut framework is structurally engaging. ~30-35% rate-cut probability priced for June 16-17 (potentially higher if Thursday’s PCE prints cooler).
MOVE Index: 74.95 (−4.44%) — APPROACHING PRE-WAR BASELINE 73.21
MOVE compressed −3.48 points to 74.95 — the SEVENTH consecutive session of MOVE compression. The cumulative MOVE trajectory: 86.07 (Tue May 19 peak) → 85.32 → 81.53 → 79.72 → 78.43 → 74.95. From the war-cycle peak to today: −11.12 points / −12.9% across 5 trading sessions. MOVE at 74.95 is now JUST 1.74 POINTS ABOVE THE PRE-WAR BASELINE OF 73.21. The structural rates-vol re-rating that began two Fridays ago has not only fully absorbed but is now in pre-war normalized territory. If MOVE crosses BELOW 73 by Friday, the bond market has officially returned to pre-crisis normalcy and the structural rates regime is back to baseline. Watch the MOVE 73 threshold as the next major structural marker.
S&P 500: ES 7,561.00 — NEW War-Cycle High Above Tuesday’s 7,544
ES at 7,561.00 (+0.32%, +24 pts) is a NEW WAR-CYCLE HIGH — extending above Tuesday’s 7,544.75 reset by approximately 16 points. NQ at 30,332.25 (+0.86%, +258 pts) is ABOVE 30,000 FOR THE FIRST TIME EVER in the war series. Cumulative ES vs pre-war 6,881.62: +9.87% — NEW war-cycle premium. The market has executed a textbook reflexive shock-absorption-extension cycle in 9 trading sessions. The technical levels: 7,540 was the next measured-move target (cleared Tuesday); 7,580 is the cycle technical extension; 7,620 is the next major resistance. Support: 7,540 (Tuesday close becomes new support), 7,495 (last week’s prior war-high becomes secondary support). NQ above 30,000 sets up a clean run at 30,500 with no significant resistance until 30,800.
Key Levels & Cumulative War Moves
Volatility & Breadth — VIX1D Capitulated, MOVE Near Pre-War Baseline
The vol read: VIX1D −36.11% to 11.13 — TOTAL hedge capitulation. VIX1D below 12 is rare and signals the options market is no longer pricing tail risk; positioning has fully committed to the structural breakout. VVIX −1.77% to 89.55 modest compression. VIX 16.79 −1.24% modest. MOVE −4.44% to 74.95 — near pre-war baseline. The ONLY countervailing vol reading: VXN +4.73% to 23.90 — Nasdaq-vol modestly bid (likely the post-NVDA single-name positioning hedge), but the broader vol tape is fully constructive. GVZ Gold-vol +1.72% to 24.27 — gold vol modestly bid as gold continues to fail to rally. SKEW +1.20% to 139.04 — tail-risk hedging modestly building but slow. COR1M −6.96% to 10.16 — the LOWEST 1-month correlation reading of the war series. Stock-picking is fully dominant; dispersion regime fully engaged. The vol configuration is the cleanest possible “post-shock breakout extension with selective alpha” signal. Breadth (S5TH 70.10, S5FI 61.30) holds constructive read.
6. THE GAME PLAN
Today: THE ACCELERATION. ES NEW war-cycle HIGH 7,561 / NQ above 30,000 first time / +9.87% above pre-war. Tue Close TWO new RLTV records: SMH 1.32 (industry war-high) + XLK 1.21 (sector war-high). CIBR 1.26 held. Clean Energy fully in top-10 leadership. AMLP −11 (Midstream crash). MOVE 74.95 just 1.74 above pre-war baseline. VIX1D capitulated to 11.13. WTI below $90. NVDA finally stabilizing. SOXX +6.10% MASSIVE broader semi rotation. No major data today. Thu PCE/GDP = the test.
The Bull Case
ES at 7,561.00 — NEW war-cycle high extending above Tuesday’s 7,544. NQ at 30,332.25 — ABOVE 30,000 FOR THE FIRST TIME EVER. Cumulative ES vs pre-war: +9.87% — NEW war-cycle premium. Two NEW war-cycle records Tuesday close: SMH RLTV 1.32 (industry war-high, the highest ever observed) + XLK RLTV 1.21 (sector war-high). CIBR RLTV 1.26 held. The triple Cyber/Tech/Semi leadership at MAXIMUM positioning simultaneously continues. Clean Energy complex fully engaged in top-10 leadership (PBW 70/1.19, QCLN 69/1.18, ICLN 69/1.09, TAN 70/1.04) — first time all four major Clean Energy ETFs are simultaneously in top-10 in the entire war. MOVE compressed to 74.95 — just 1.74 points above pre-war baseline 73.21; the structural rates-vol re-rating has not only absorbed but normalized. VIX1D capitulated to 11.13 — total hedge unwind. 30Y at 5.003%, 10Y at 4.465%, 5Y at 4.160% — full Bull Steepener (curve regime shift). WTI broke below $90 to $88.58 — cumulative −$15+ / −14% from war-high peak. Energy capitulation removes the structural inflation tail. Pre-market: VLUE +3.85% / MTUM +3.44% / SPHB +2.79% — MASSIVE Value/Momentum/High-Beta factor rotation; ALL FOUR defensive factors RED (USMV, SPLV, DGRO, VYM). SOXX +6.10% MASSIVE — broader semi cohort decisively taking leadership beyond NVDA-only concentration; the AI thesis decoupling from megacap concentration is structurally healthy. NVDA finally stabilizing at $215 (essentially flat). GOOG recovering. COR1M at war-low 10.16 — dispersion regime fully engaged. RUT +0.54%, IWM Tuesday close RLTV 1.01 (above baseline) — small caps participating. If Thursday’s PCE prints at or below 0.3% and GDP confirms 2.0%+, the next leg targets ES 7,600 / NQ 30,800 / 30Y 4.95% / MOVE below 73 (pre-war baseline cleared). The structural bull thesis is fully engaged.
The Bear Case
Cumulative ES premium at +9.87% above pre-war is the HIGHEST war-cycle reading and historically reaches profit-taking territory near 10%. The breakout above 30,000 NQ is psychological and could trigger profit-taking. VIX1D at 11.13 = total complacency — historically, extreme low-vol readings often precede 3-5% pullbacks. Gold $4,449 (−1.18%) continues to FAIL TO RALLY despite weaker dollar (DXY below 99 first time) — the gold-divergence has now persisted for 8+ sessions, suggesting positioning is still fragile in precious metals. The Bull STEEPENER regime shift today is unusual — it could signal that the market is pricing growth softening more aggressively than the equity tape suggests. If Thursday’s GDP 2nd estimate prints below 1.5% (consensus 2.0%), the soft-landing thesis takes a hit. The Energy capitulation (WTI below $90) is structurally bearish for energy-services / infrastructure / E&P names: AMLP −11 Tuesday close, XOP at 43 (lost above-50), CRAK at 43. The XLE −2.76% pre-market is the worst sector. If Brent breaks below $90 this week, the Energy thesis at the RLTV level (USO 1.55, XES 1.04, OIH 1.01) compresses to baseline. NVDA at $214.86 — while stabilizing, has not yet bounced. If NVDA breaks $213 to a 2-month low, the SMH RLTV 1.32 war-high will eventually compress. The defensive sectors all RED Tuesday close (XLP −8, XLV −5, XLE −7, XLU −1) — but a re-emergence of defensive bid mid-week would signal positioning unwind. The Bull Steepener curve combined with VIX1D at 11.13 + MOVE at near-pre-war + ES at +9.87% premium = the cleanest possible “everything is priced for perfection” configuration. Any Thursday data disappointment creates asymmetric downside. Watch ES 7,540 support — a break engages 7,495 / 7,460.
Regime: THE ACCELERATION — Post-Resolution Extension. ES NEW War-High / NQ Above 30,000 First Ever / Two NEW Tuesday RLTV Records (SMH 1.32, XLK 1.21). MOVE Near Pre-War. Clean Energy Top-10 Engaged. Energy Capitulated. NVDA Stabilizing. SOXX +6.10% Broader Semi Rotation. Watch ES 7,540 support / 7,580 next resistance, 30Y 5.00% / 4.95%, MOVE 73 (pre-war target), Thu PCE/GDP 8:30 ET. The structural breakout requires confirmation Thursday — light Wednesday data gives time to consolidate.
Watch List
Thursday 5/28 8:30 ET — Core PCE m/m + Prelim Q1 GDP 2nd Est — THE WEEK’S KEY TEST
Core PCE m/m cons 0.3% vs prior 0.3% — the structural inflation test. With UK CPI cooled to 2.8% + Canadian CPI all-four-measures cooler + WTI at $89 (vs war-high $104) + Brent at $92 (vs war-high $112), the US Core PCE has substantial structural setup to print at or below cons. A 0.2% print is the cleanest “Fed can cut at June 16-17” signal — pushes 30Y toward 4.90%, accelerates risk-on. A 0.4% print engages persistent-inflation re-engagement narrative. Prelim Q1 GDP 2nd estimate cons 2.0% vs prior 0.7% Advance — a substantial upward revision of ~130 bps would confirm structural growth resilience. Watch the inventories subcomponent for the cleanest “demand vs inventories” signal.
AI/Semis — TRIPLE Leadership At MAX RLTV; NVDA Finally Stabilizing
CIBR 1.26 + XLK 1.21 + SMH 1.32 — Triple AI / Cyber / Tech leadership at simultaneous war-cycle high RLTV (Tuesday close). SMH RLTV 1.32 is the highest single-industry positioning ever observed in the entire 90-day war. NVDA at $215 essentially flat today — the 6-session fade (cumulative −8.85%) is ending. SOXX +6.10% pre-market — the broader semi cohort (AMAT, AVGO, AMD, MU) is decisively taking leadership without NVDA single-name. The AI thesis has structurally decoupled from megacap concentration risk. Watch SOXX vs NVDA spread — if SOXX outperforms NVDA by 5%+ today, the broader semi leadership is fully engaged.
Clean Energy — Top-10 Leadership Engaged
Tuesday close: PBW Clean Energy STRNG 70 / RLTV 1.19, QCLN Clean Edge STRNG 69 / RLTV 1.18, ICLN Clean Energy STRNG 69 / RLTV 1.09, TAN Solar STRNG 70 / RLTV 1.04 — all four major Clean Energy ETFs in top-10 industry leadership SIMULTANEOUSLY. The first time this has occurred in the entire 90-day war series. The Clean Energy rotation from war-low PBW STRNG 49 (Tue 5/19 close) to STRNG 70 today = +21 STRNG over 5 trading sessions. The “rate-relief + structural transition” thematic positioning is fully engaged. Pre-market ICLN +2.32% extending. Watch FSLR / ENPH / SEDG individual names for confirmation.
Energy — Capitulation Continuing; AMLP Crashed Tuesday
The Energy Phoenix continues capitulation. WTI −5.66% today to $88.58 (broke below $90). Brent −4.45% to $92.37 (broke below $95). Cumulative WTI from war-high $104+: −$15+ / over −14%. Tuesday close: AMLP Midstream CRASHED from STRNG 60 → 49 (−11) / RLTV 0.95 — Midstream broke below baseline for first time since Day 60. XOP Oil & Gas E&P −7 to STRNG 43 / RLTV 1.02. CRAK Oil Refiners −3 to STRNG 43 / RLTV 0.98. XES Oil Equipment held STRNG 57 / RLTV 1.04. OIH Oil Services held STRNG 58 / RLTV 1.01. The Energy services + infrastructure + midstream + refining complex is in coordinated capitulation. RLTV readings still above baseline for USO (1.55), OIH (1.01), XES (1.04), XOP (1.02) — but trending lower. If Brent breaks below $90 by Friday, the energy thesis at the RLTV level compresses to baseline. Pre-market XLE −2.76% extending.
Cyber — CIBR Consolidating At War-High RLTV 1.26; PANW June 2 The Test
CIBR at STRNG 83 / RLTV 1.26 — Tuesday close held the war-high RLTV reading from Friday. CIBR is consolidating at the cycle peak rather than extending. Pre-market CIBR +0.24% near flat — consolidating. The structural decoupling from broader macro continues but the +7 RLTV jump from Thu to Fri 5/22 has not extended. PANW June 2 AMC is the catalyst. Pre-market today CIBR is in the lower-third of thematic gains (SOXX, DRIV, ARKQ, PAVE, ICLN all stronger). Watch SOXX vs CIBR rotation — if SOXX continues to outperform CIBR through the week, the broader AI thesis is taking leadership from cyber-specific positioning.
Bonds — Bull Steepener Regime; MOVE Near Pre-War Baseline
The bond market is now in Bull STEEPENER regime (curve regime shift from prior Bull Flattener). 30Y at 5.003%, 10Y at 4.465%, 5Y at 4.160%, 2Y at 4.033%. Tuesday cash session was a full Bull Flattener (-4 to -9 bps across the curve); overnight the long end has fallen faster than the front, shifting to a steepener pattern. The market is increasingly pricing long-run growth deceleration and disinflation. MOVE at 74.95 — just 1.74 points above pre-war baseline 73.21. Seven consecutive sessions of MOVE compression; cumulative −12.9% from Tuesday May 19 peak. If MOVE crosses below 73 by Friday, the bond market has officially returned to pre-crisis normalcy. Watch the bond reaction to Thursday’s PCE — a cooler print pushes 30Y toward 4.90%.
Tue June 2 — PANW Q3 FY26 (Delayed from May 20) — Cyber Catalyst
PANW Palo Alto Networks Q3 FY26 reports Tuesday June 2 AMC — the structural cyber test. CIBR at war-high RLTV 1.26 — PANW must deliver clean beat with strong forward guide to sustain CIBR’s structural decoupling from broader macro. CyberArk integration commentary, Chronosphere ARR trends, federal contracts, AI-defense capex are the key items.
Tue June 16 / Wed June 17 — Warsh FIRST FOMC As Chair
Warsh’s first FOMC June 16-17. With 30Y at 5.00%, MOVE near pre-war baseline, ES at new war-high, Triple AI leadership at max, WTI capitulated below $90, NQ above 30,000 first time — the structural setup for a CUT is building. Markets pricing ~30-35% rate-cut probability (potentially rising further if Thursday PCE prints cooler). Watch Warsh’s new SEP (Summary of Economic Projections) for the structural rate path; “trimmed-mean inflation” framing; balance sheet runoff commentary.
Morning check: Day 90. THE ACCELERATION. ES at 7,561.00 is NEW war-cycle high. NQ at 30,332.25 ABOVE 30,000 FIRST TIME EVER. Cumulative ES vs pre-war: +9.87% — NEW war-cycle premium. Tuesday close delivered TWO NEW war-cycle high RLTV records: SMH STRNG 74 / RLTV 1.32 (highest single-industry positioning ever in 90-day war) + XLK STRNG 77 / RLTV 1.21. CIBR held STRNG 83 / RLTV 1.26. Clean Energy fully in top-10 (PBW 70/1.19, TAN 70/1.04, QCLN 69/1.18, ICLN 69/1.09 — first time ever). AMLP Midstream CRASHED −11. Bond complex extended massively (MUB +11, TIP +10). Today MOVE −4.44% to 74.95 — just 1.74 above pre-war baseline. VIX1D −36.11% to 11.13 — total capitulation. Curve shifted to Bull STEEPENER (30Y 5.003%, 10Y 4.465%). WTI −5.66% to $88.58 — broke below $90. Mag 7 split 3G/4R: TSLA +1.78%, GOOG +1.44% lead; NVDA −0.22% finally STABILIZING after 6-session fade. SOXX +6.10% MASSIVE broader semi rotation. VLUE +3.85% / MTUM +3.44% major Value/Momentum rotation. XLK +2.63% massive lead; XLE −2.76% / XLP −1.38% / XLV −0.92% red. No major data today. Thu 8:30 ET Core PCE (0.3% cons) + Prelim Q1 GDP 2nd est (2.0% cons). PANW June 2. Warsh FOMC June 16-17. Pressure, not panic. Regime, not reaction. The Acceleration awaits Thursday’s PCE confirmation.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.