

1. THE QUICK SCAN
Overnight Tape Summary: PPI EXPLODED. CORE PPI 1.0% VS 0.3% CONSENSUS — BEAT BY 0.7%, 10X THE PRIOR MONTH. HEADLINE PPI 1.4% VS 0.5% CONSENSUS — BEAT BY 0.9%, NEARLY 3X PRIOR. THE HOTTEST SINGLE-MONTH PRODUCER-PRICES PRINT OF THE WAR SERIES. 30Y CROSSED 5.00% — NOW 5.041%, THE FIRST SUSTAINED BREACH OF THE CRISIS THRESHOLD SINCE DAY 47-48. YIELD CURVE FLIPPED FROM BEAR FLATTENER TO BEAR STEEPENER — THE MOST BEARISH CONFIGURATION FOR RISK ASSETS. MOVE 71.68 (+1.33%) CONTINUES TO EXPAND. WTI HOLDS $102.45. ES 7,420 (−0.09%) ESSENTIALLY FLAT. DEFENSIVE ROTATION ENGAGED: XLV +1.96%, XLP +1.28% LEADING; XLK −1.51%, SOXX −3.15% RED. TSLA −2.60% (REVERSING YESTERDAY’S +3.89%). USMV+SPLV BID, VLUE / SPHB / MTUM ALL RED. 34 MACRO TUESDAY CLOSE: TECH COMPRESSED (XLK 85 → 78, SMH 82 → 74, QQQ 83 → 78), DEFENSIVES ROTATED IN (XLP 51 → 57, XLV 39 → 50). XLE RLTV CROSSED ABOVE BASELINE TO 1.01. WARSH CHAIR VOTE TODAY 2:30 PM — BOARD VOTE TUESDAY PASSED 51-45 PARTY-LINE.
The data exploded. Core PPI rose 1.0% month-over-month — TEN TIMES the prior month’s 0.1% and a 0.7-point beat versus the 0.3% consensus. On an annualized basis, today’s core PPI impulse is approximately 12% — a number that does not exist in normal-cycle data, the kind of print that shows up only in supply-shock regimes. Headline PPI 1.4% beat the 0.5% consensus by 0.9 points and printed nearly 3x the prior 0.5% read. The PPI complex is the cleanest single read on the gasoline + Iran-rejection + ISM Prices Paid 84.6 pass-through that defined the last week, and the numbers are off the charts. Combined with yesterday’s hot Core CPI 0.4% / Headline YoY 3.8%, the inflation regime has now been re-engaged across BOTH the consumer-side AND the producer-side measures simultaneously. This is the hardest-to-dismiss inflation print of the entire 76-day war series — there is no “energy tail” excuse, no “base effects” excuse, no “transient” framing that absorbs a 1.0% Core PPI with a 10x m/m acceleration.
And the bond market broke. The 30Y rose 1.4 bps to 5.041% — BREACHING the 5.00% crisis threshold that has defined every bond-vol regime in this war. The 30Y last sat above 5.00% on Day 47-48 in late April during the FOMC-fracture rates crisis. Today’s breach is structurally different and more consequential: it arrived NOT during a panic event but during a methodical, data-driven repricing — first NFP last Friday, then hot CPI Tuesday, then hot PPI today. And critically, the yield curve has FLIPPED. Yesterday’s Bear Flattener (front end leading) has become today’s Bear Steepener (long end leading: 30Y +1.4 bps / 10Y +2.2 bps / 5Y +1.2 bps / 2Y +0.8 bps). The Bear Steepener is the most bearish curve configuration for risk assets — it reflects long-duration inflation pricing and term-premium expansion rather than near-term rate-cut repricing. The market is no longer debating whether Warsh holds; it is debating whether Warsh has to HIKE in his first FOMC.
MOVE expanded another +0.94 points to 71.68 (+1.33%) — a fourth consecutive session of rates-vol expansion off Monday’s 67.25 war low. MOVE remains below the 73.21 pre-war baseline, but the trajectory is unambiguous and persistent. If MOVE crosses 73 by close, the structural “rates vol has internalized the war” thesis that held for two weeks is broken. The cross-asset response is the cleanest defensive rotation of the war: XLV Healthcare +1.96% LEADING pre-market — Health-Care recovered from war-low sector position (Tuesday close STRNG 39 / RLTV 0.86) to lead the morning. XLP Consumer Staples +1.28%, XLF Financials +0.78%, XLE Energy +0.70% — defensives and cyclicals lifting. The reverse: XLK Technology −1.51%, with SOXX Semiconductor −3.15% the day’s steepest thematic decline — the AI/Semis leadership trade is finally being unwound on the duration sensitivity to a 30Y above 5.00%. Factors are equally clean: USMV Min-Vol +0.41%, SPLV Low-Vol +0.61% leading; VLUE Value −1.60%, SPHB High-Beta −1.44%, MTUM Momentum −1.12%. The USMV−SPHB spread has flipped from −2.34% Monday to +1.85% today — a 4.19-point swing in two sessions, the cleanest factor-regime inflection of the war.
The equity headline is misleadingly stable. ES at 7,420 (−0.09%) is essentially flat — the war-high premium at +7.8% above pre-war 6,881.62 is intact despite the PPI bomb. But underneath, the dispersion is extreme. NQ +0.20% green (counter-intuitive on the duration move — explained by AAPL +0.72%, META +0.69%, NVDA +0.61% catching defensive bids while TSLA −2.60% reverses yesterday’s +3.89% rally completely). Dow −0.52%, RUT −0.41%. The Mag 7 is split 3 green / 4 red with the YESTERDAY-WINNER TSLA flipping to the LEADING DRAG today, and MSFT −1.18% / AMZN −1.18% / GOOG −0.76% continuing the post-earnings capex compression. International tape mixed: Nikkei +0.41%, DAX +0.37%, EuroStoxx flat, China continues sideways. Currencies bid the dollar: DXY 98.45 (+0.26%), GBP −0.30%, EUR −0.31%, NZD −0.47% — the strong-dollar reflex on hot US data is intact. Bitcoin −1.16% to $80,055 — crypto under modest pressure but holding the $80K zone.
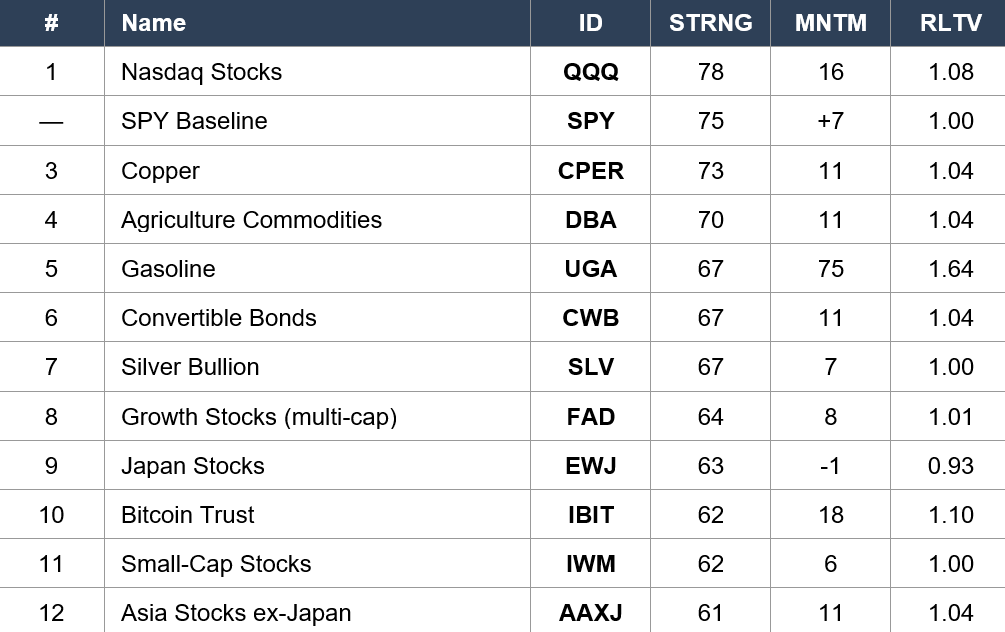
The 34 Macro Tuesday-close data shows the rotation was already underway by yesterday’s 5:20 PM print, before today’s PPI bomb. Tech leadership has materially compressed: XLK fell from STRNG 85 to 78 (−7 points), SMH fell from STRNG 82 to 74 (−8 points and a clear breach of the war-high tier), QQQ from STRNG 83 to 78 (−5 points). The defensive rotation is equally clean: XLP Staples jumped from STRNG 51 to 57 (+6, reclaiming Leaders position at #3), XLV Health-Care surged from STRNG 39 to 50 (+11 points and the largest single-session sector strength gain of the war series). XLE Energy continued to assert: STRNG 48 → 50, RLTV 1.00 → 1.01 — XLE has CROSSED ABOVE BASELINE for the first time in five sessions; the Energy Phoenix trade is officially back. Crude USO STRNG 55 → 59 with RLTV 1.67 → 1.73 — a NEW WAR HIGH for USO relative strength (RLTV). Silver (SLV) STRNG 67 / RLTV 1.00 — RLTV recovered to baseline EXACTLY, eliminating the war-low 0.60 reading completely. International equity weakness was the cleanest signal: AAXJ Asia STRNG 74 → 61 (−13!), EEM Emerging Markets STRNG 71 → 60 (−11!) — the strong-dollar / hot-CPI combination crushed international leadership.
The Number That Matters: The 30Y At 5.041% — Breached The 5.00% Crisis Threshold On A Methodical Bear Steepener Driven By Core PPI 1.0% (10x Prior, 4x Consensus). The Bond Market Has Made Its Choice. The Inflation Regime Is Re-Engaged. The Curve Configuration Is The Most Bearish For Risk Assets. The Question Is No Longer Whether Warsh Holds; It Is Whether Warsh Has To Hike.
This is a regime statement. Through two weeks the bond market’s war-low MOVE complacency told the structural-disinflation story. In 48 hours, hot Core CPI + Core PPI 1.0% + WTI above $100 + the Iran-rejection diplomatic stall have collapsed that narrative. The 30Y has crossed 5.00%, the curve has flipped to Bear Steepener (the most bearish configuration), and the cross-asset rotation into defensives is the cleanest single signal of regime change in the war series. Warsh’s Senate chair vote at 2:30 PM drops into this configuration. The board vote yesterday was 51-45 on a near-party-line basis (only Fetterman crossed) — a narrow margin that signals the hawkish lean the market has been pricing. Powell’s term ends Friday. Warsh takes over an FOMC that just released its dovish dissenter (Miran’s board term ended with Warsh’s confirmation) and is being asked to confront an inflation regime that has just visibly re-engaged on the supply side.
The Setup: Bear Steepener — PPI Explosion / 30Y Breaches 5.00% — Defensive Rotation Engaged. ES Holds The War-High Premium On The Headline; Internal Rotation Is The Cleanest Regime Inflection Of The War. Watch The 2:30 PM Warsh Chair Vote, Retail Sales Tomorrow 8:30, And AMAT Earnings Thursday AMC. Powell’s Term Ends Friday May 15.
2. OVERNIGHT SESSION RECAP
Asia — Mixed, Nikkei Bounces, Topix Heavy
Nikkei 62,775 (+0.41%) finally bounced after two days of weakness, but TOPIX 3,896 (−0.50%) was red — the cap-weight rotation continues, with broader Japan giving up ground while the tech-heavy Nikkei catches a bid. JPY −0.18% extending Tuesday’s weakness. AAXJ Asia ex-Japan at Tuesday close STRNG 61 / RLTV 1.04 — the Asia ex-Japan leadership trade has materially compressed from STRNG 74 just three sessions ago (−13 points). EEM Emerging Markets STRNG 60 / RLTV 1.02 — same pattern, the international risk complex is the cleanest casualty of the strong-dollar / hot-CPI / hot-PPI combination. China FXI STRNG 57 / RLTV 0.89 — China complex weakening incrementally.
Europe — Mixed Pre-PPI, Now Absorbing US Data
DAX 24,109 (+0.37%) caught a small bid pre-US-data on a weaker EUR (1.1724, −0.31%), and EuroStoxx 50 flat at 5,801. Europe is rangebound here: the strong dollar supports DAX export names but the hot US inflation read tightens global financial conditions through the dollar. GBP fell another −0.30% to 1.3491 — sterling has now declined approximately −1.7% in three sessions on cumulative BoE positioning. The European session is in “wait for US 8:30” mode, and the PPI bomb that just dropped means today’s European close will be defined by post-PPI flow back into Europe.
US Pre-Market — Flat Headline, Defensive Internal
ES 7,420 (−0.09%, −6.5 pts) at the same level as Tuesday’s pre-market — the cumulative two-day move is approximately zero despite hot CPI Tuesday and hot PPI Wednesday. The market’s ability to hold +7.8% above pre-war through three consecutive inflation shocks is the structural read; the internal rotation INTO defensives is the cleaner regime signal. NQ +0.20% green is counterintuitive on the duration move — explained by AAPL / META / NVDA catching defensive-quality bids against the broader semis weakness. Dow −0.52%, RUT −0.41%. Yields rose modestly across the curve: 30Y +1.4 bps to 5.041%, 10Y +2.2 bps to 4.485%, 5Y +1.2 bps to 4.138%, 2Y +0.8 bps to 4.002%. The Bear Steepener is the most consequential aspect of the morning rates tape.
Mag 7 Pre-Market — Defensive Rotation Inside The Mag 7
AAPL $294.80 (+0.72%) leading the green names — Apple catching a defensive-quality bid on the rate move (Apple’s margins-driven cash-flow profile holds up better in rising-rate regimes than the AI-capex-heavy names). META $603 (+0.69%) — Meta catching a bounce. NVDA $220.78 (+0.61%) extending — NVDA remains the AI demand-thesis anchor even as broader semis sell off. GOOG $383.82 (−0.76%) continuing the antitrust + duration drag. AMZN $265.82 (−1.18%) and MSFT $407.77 (−1.18%) absorbing the duration move. The standout reversal is TSLA $433.45 (−2.60%) — Tesla giving up most of yesterday’s +3.89% rally as the high-beta retail-momentum trade gets punished. Mag 7 is 3 green / 4 red, with TSLA the largest single-name drag.
Sectors — The Cleanest Defensive Rotation Of The War
XLV Health Care +1.96% — the day’s leading sector and the strongest XLV pre-market print of the entire 76-day war. After hitting Tuesday’s close at STRNG 39 / RLTV 0.86 (war-laggest), XLV is staging a textbook deep-laggard mean reversion. XLP Consumer Staples +1.28%, XLF Financials +0.78%, XLE Energy +0.70% (still tracking oil), XLC +0.24%, XLU +0.11%, XLRE +0.02%. The reverse: XLK Technology −1.51%, XLY Consumer Discretionary −0.90%, XLI Industrials −0.39%, XLB Materials −0.23%. The 7/11 green / 4 red split disguises the rotation: defensives (XLV, XLP, XLF, XLU) green; growth/cyclicals (XLK, XLY, XLI) red. This is the cleanest “duration-aware defensive rotation” tape of the war series.
Factors — USMV / SPLV Lead, VLUE / SPHB / MTUM Crash
SPLV Low-Vol +0.61%, USMV Min-Vol +0.41%, DGRO Dividend Growth +0.33%, VYM High-Dividend +0.10% — the defensive factor cohort leading. VLUE Value −1.60%, SPHB High-Beta −1.44%, MTUM Momentum −1.12%, IJR Small-Cap −1.14%, IJH Mid-Cap −0.62%. The USMV−SPHB spread has FLIPPED to +1.85% (Tuesday: −0.38%; Monday: −2.34%) — a 4.19-point swing in two sessions and the cleanest factor regime inflection of the entire war. Yesterday’s Value + Momentum + High-Beta co-leadership thesis is dead; today’s Min-Vol + Low-Vol + Dividend defensive thesis is fully engaged.
Thematics — Semis Crash, Defense Holds, Crypto Compressed
SOXX Semiconductor −3.15% leading red — the AI/Semis leadership trade is being unwound on the duration move. ARKW Next-Gen Internet −2.13%, DRIV Autonomous −2.21%, BLOK Crypto-related −1.75%, FINX FinTech −1.62%, ICLN Clean Energy −1.61%, ARKQ Autonomous Tech −1.24%, CIBR Cybersecurity −0.78%, PAVE Infrastructure −0.91%, ARKG Genomic −0.73%. ITA Aerospace & Defense −0.27% — the geopolitical hedge has unwound; defense names are essentially flat-to-red on the diplomatic stall having priced in. The thematic tape is the cleanest possible “high-beta / long-duration / risk-asset compression” configuration.
Commodities — Oil Holds, Metals Bid, Cocoa Crashes
WTI $102.45 (+0.26%) holding the $102 zone after yesterday’s explosion above $100. Brent $107.87 (+0.09%) flat above the century. RBOB −4.63% and Ethanol −5.14% — gasoline futures correction overnight, perhaps the cleanest signal that yesterday’s gasoline gap was over-extended. The petroleum complex is consolidating the post-Iran-rejection move. Metals are bid: Silver $86.83 (+1.44%) extending — silver now up approximately +22% from war-low levels. Copper $6.62 (+1.41%) at fresh highs — the global-demand-resilience read intact. Platinum +1.16%, Palladium +0.95%. Gold $4,685.50 (−0.03%) flat — gold is the day’s most surprising holding, NOT catching a bid on the inflation print, which suggests positioning is heavy. Cocoa −8.37% reversing Monday’s +12.15% in a classic mean-reversion pattern; Cotton −1.65%.
3. THE PRIOR DAY’S REGIME
34 Macro Price, Strength & Momentum Rankings — Daily Close, Tuesday May 12. SPY Baseline: STRNG 75 | MNTM +7 | RLTV 1.00.
Asset Classes — Leaders
Asset Classes — Crude RLTV At War High / Bonds Lagging / Vol Tail
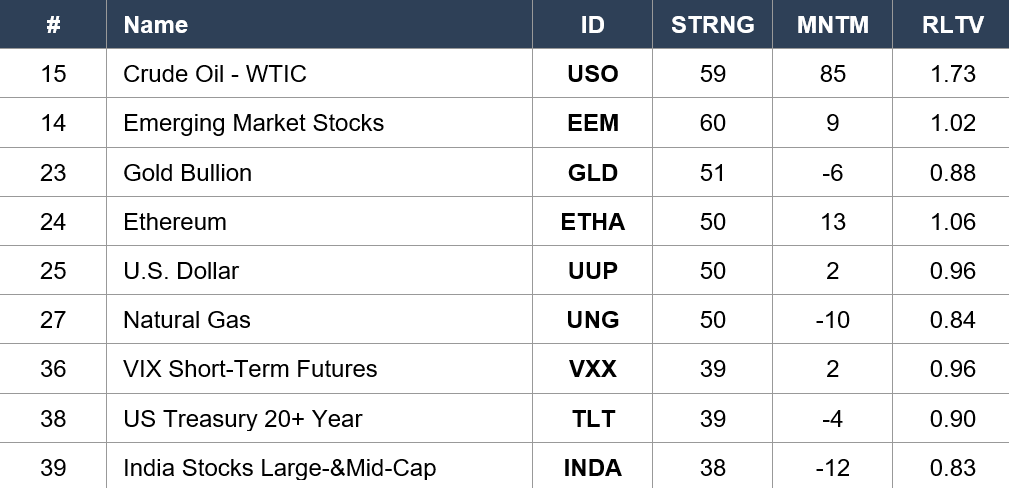
Regime signal: TUESDAY’S CLOSE TOLD THE ROTATION STORY 18 HOURS BEFORE WEDNESDAY’S PPI CONFIRMED IT. SPY baseline edged from STRNG 76 (Monday) to STRNG 75 — a one-point compression. QQQ Nasdaq compressed from STRNG 83 to 78 (−5 points) — the war-high QQQ run is over. Copper (CPER) jumped to rank #3 at STRNG 73 / RLTV 1.04 — copper has now sustained Leaders-tier for four consecutive sessions and the RLTV has expanded from 0.99 to 1.04. Agriculture (DBA) at rank #4 STRNG 70 / RLTV 1.04 — soft-commodity inflation bid persistent. UGA Gasoline rank #5 at STRNG 67 / RLTV 1.64 — gasoline strength rebuilding alongside the oil shock. Silver (SLV) rank #7 at STRNG 67 / RLTV 1.00 — RLTV recovered to BASELINE exactly. From the war-low SLV RLTV of 0.60, silver has rebuilt completely. Asia (AAXJ) fell from STRNG 74 to 61 (−13) — the strong-dollar / hot-CPI combination has crushed international leadership. The CRITICAL Crude development: USO Crude Oil RLTV expanded from 1.67 to 1.73 — a NEW WAR HIGH for USO relative strength on the front-month positioning. The bond complex remains the war’s most consistent lagger with IEF / TLT / SHY all in the bottom five. VXX at STRNG 39 / RLTV 0.96 — fear bid is creeping back as RLTV has risen from 0.88 to 0.96 in five sessions.
Sector ETFs
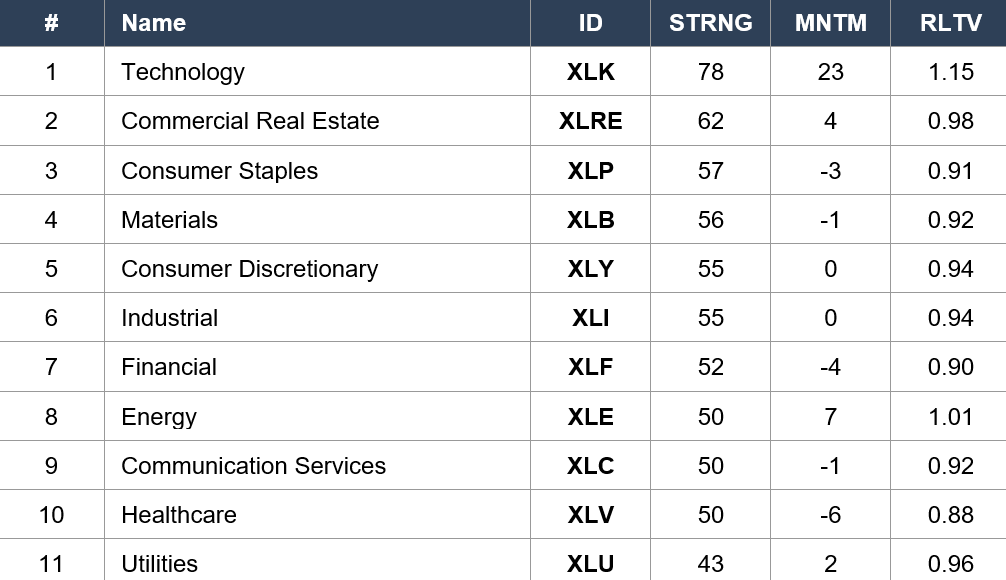
Regime signal: XLK TECHNOLOGY COMPRESSED FROM WAR HIGH BUT HELD #1 LEADERSHIP. XLK fell from Monday’s STRNG 85 / RLTV 1.16 (war high) to Tuesday’s STRNG 78 / RLTV 1.15 — a −7 STRNG move but RLTV barely budged, suggesting the broad market also weakened in proportion. The DEFENSIVE ROTATION crystallized: XLP Consumer Staples jumped from STRNG 51 to 57 (+6, reclaiming Leaders position at rank #3). XLV Health-Care surged from STRNG 39 to 50 (+11 points — the largest single-session sector strength gain of the war series), but XLV remains in the Laggers section at rank #10 — the deep-laggard mean reversion has started but XLV is still positioned for further recovery if the duration move sustains. The CRITICAL Energy development: XLE STRNG 48 → 50, RLTV 1.00 → 1.01 — XLE has CROSSED ABOVE BASELINE for the first time in five sessions. The Energy Phoenix is back. Cyclicals participated modestly: XLB STRNG 53 → 56 (+3), XLI held at STRNG 55. XLF Financials STRNG 47 → 52 (+5) — financials catching a bid as the long end backs up. XLC Communication Services held at STRNG 50 (sub-baseline), XLY Consumer Discretionary fell from STRNG 59 to 55 (−4). XLU Utilities held at STRNG 43 / RLTV 0.96 — still the LAGGEST sector. The sector tape captured the regime inflection: defensives rotating IN, growth/discretionary OUT, energy reasserting.
Industry ETFs — Leaders
Industry ETFs — Laggers
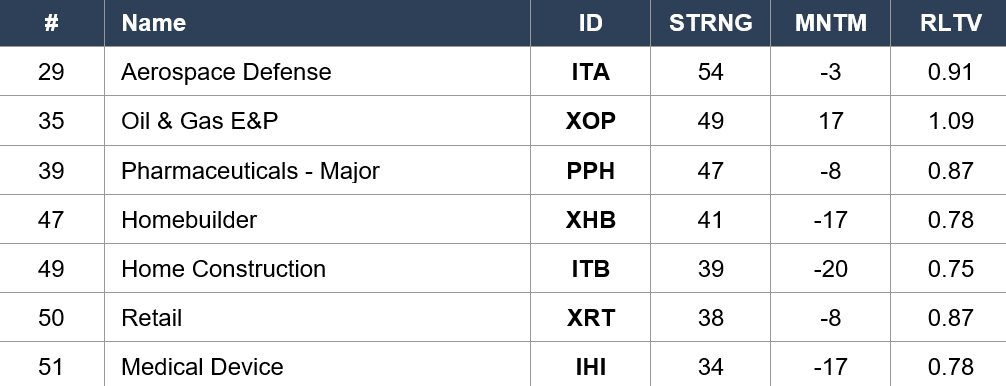
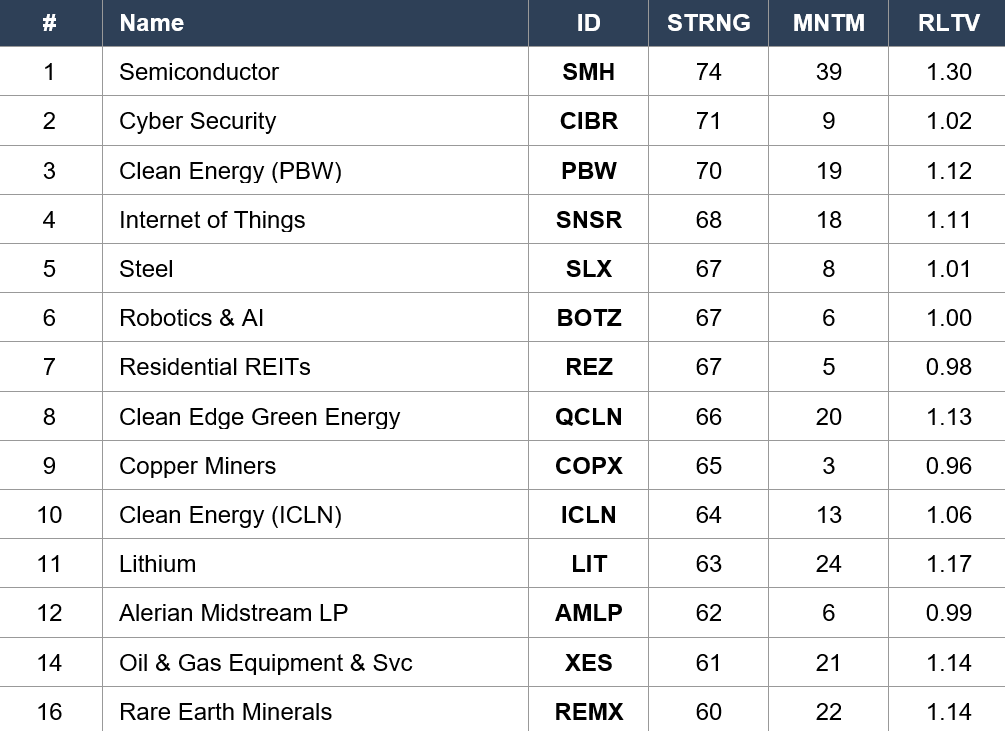
Regime signal: SMH SEMICONDUCTOR COMPRESSED MEANINGFULLY FROM WAR HIGH: STRNG 82 / RLTV 1.33 (Monday) → STRNG 74 / RLTV 1.30 (Tuesday). The −8 STRNG move is the largest single-session SMH compression in the war series — semis are absorbing the rate move ahead of AMAT earnings Thursday. CIBR Cyber Security held #2 at STRNG 71. The CLEAN ENERGY COMPLEX retained leadership but compressed at the edges: PBW STRNG 76 → 70 (−6), QCLN STRNG 72 → 66 (−6), ICLN STRNG 69 → 64 (−5), TAN STRNG 67 → 61 (−6), FAN STRNG 64 → 56 (−8) — clean energy industries compressed roughly in tandem, suggesting a thematic mean reversion rather than a structural sell-off. LIT Lithium STRNG 70 → 63. The ENERGY INFRASTRUCTURE complex caught a fresh bid: AMLP Midstream STRNG 56 → 62 (+6, rank #12), XES Oil & Gas Equipment STRNG 59 → 61 (+2, rank #14 with MNTM +21 / RLTV 1.14) — both broke into the Leaders/near-Leaders. The capital flowing INTO AMLP / XES is the cleanest “energy reflation real assets” signal — investors are choosing midstream/services pipelines as the durable energy exposure rather than the upstream cyclicality of XOP. COPX Copper Miners joined Leaders at STRNG 65 (up from 61). The Laggers tell the story: IHI Medical Devices STRNG 24 → 34 (+10) — modest recovery from the war low, but still LAGGEST. ITB Home Construction STRNG 41 → 39 / RLTV 0.75 — NEW WAR LOW for the housing complex. XOP Upstream E&P at STRNG 49 — the worst-performing energy industry despite WTI above $100. The structural dispersion of the war is at its widest: capital is concentrated in tech-still-leading-but-compressing, defensives-rotating-in, energy-infra-emerging, while housing / retail / medtech / pharma break to fresh lows.
4. MORNING DATA REACTION
Core PPI m/m — 1.0% (MASSIVE BEAT — Hot, Consensus 0.3%)
April Core PPI rose 1.0% month-over-month — a 0.7-point beat versus the 0.3% consensus and TEN TIMES the prior month’s 0.1%. On an annualized basis the core impulse is approximately 12% — a reading that does not exist in normal-cycle data. This is the kind of print that shows up only in acute supply-shock regimes. The Core PPI is the cleanest read on ISM Manufacturing Prices Paid (84.6 — highest since 2022) pass-through to actual factory-gate inflation, and the data has confirmed what the ISM survey was signaling for two months. Today’s print removes any analytical case that the inflation re-acceleration is “energy-tail only” — Core EXCLUDES energy. The 10x m/m acceleration in a single print is structurally rare and the Fed will treat it as such.
Headline PPI m/m — 1.4% (MASSIVE BEAT — Hot, Consensus 0.5%)
Headline PPI 1.4% beat consensus by 0.9 points and printed nearly 3x the prior month’s 0.5% — also a re-acceleration print. The energy and gasoline pass-through that markets had expected to MODERATE in April based on the WTI $90-95 average actually ACCELERATED. With WTI back above $100 today and Brent at $107, the May PPI is set to print even hotter. The pipeline view is unambiguous: producer-level inflation pressure is BUILDING into Q2, not fading. The market’s response to today’s print — 30Y breaching 5.00%, Bear Steepener engaging — reflects this pipeline reality.
Today 2:30 PM — Warsh Senate Chair Confirmation Vote
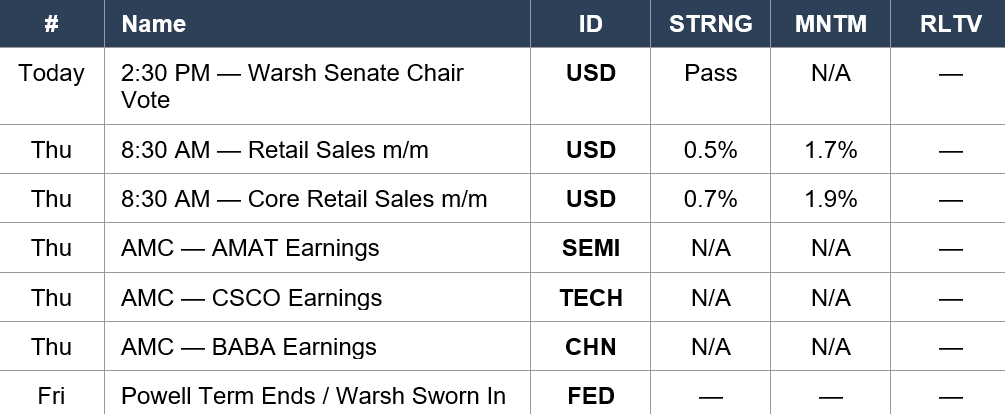
Yesterday the Senate confirmed Warsh to the Federal Reserve BOARD of Governors by a 51-45 vote on a near-party-line basis (only Sen. Fetterman crossed the aisle). The narrow, partisan margin is itself significant — every prior Fed chair confirmation has had meaningful bipartisan support; Warsh’s board vote was the most partisan in modern Fed history. Today’s 2:30 PM vote is a SEPARATE vote on Warsh as CHAIR (the 4-year chair term is distinct from the 14-year governor term). Stephen Miran’s brief board term ended with Warsh’s confirmation yesterday — the FOMC’s sole dovish dissenter has now exited. Warsh has publicly called for “regime change” at the Fed and said he believes the policy rate can be lower; markets are currently pricing about a 1-in-3 chance of a rate HIKE by December. The chair vote arrives directly into today’s 30Y-above-5.00% configuration. Watch the margin: a clean partisan passage (53-46 or similar) confirms continuity of the hawkish-lean trajectory; any dovish surprise commentary could provide modest bond-market relief. The first Warsh FOMC is June 16-17.
Coming Up Tomorrow & Friday
5. THE DYRH READ
Yield Curve Regime: Bear Steepener — The Most Bearish Configuration
The curve has FLIPPED. Yesterday’s Bear Flattener (front-end leading rate-cut repricing) is today’s Bear Steepener (long-end leading inflation/term-premium repricing): 2Y +0.8 bps to 4.002%, 5Y +1.2 bps to 4.138%, 10Y +2.2 bps to 4.485%, 30Y +1.4 bps to 5.041%. The 2s/30s spread is 103.9 bps — expanding from yesterday’s 102.2. The Bear Steepener is the curve configuration historically most associated with risk-asset multiple compression. It reflects: (1) the long end pricing higher inflation expectations and term-premium expansion, (2) the front end being capped by the Fed’s reaction function (the 2Y can’t go above where the market thinks the next cut is). With 30Y at 5.041% — BREACHING the crisis threshold — every additional basis point of long-end selling now matters more than at lower yield levels.
MOVE Index: 71.68 (+1.33%) — Fourth Consecutive Session Expanding
MOVE expanded another +0.94 points to 71.68 — a fourth consecutive session of rates-vol expansion off Monday’s 67.25 war low. The Day 74 → Day 75 → Day 76 trajectory is 67.25 → 70.74 → 71.68 — a cumulative +6.6% expansion in three sessions. MOVE remains below the 73.21 pre-war baseline (−1.53 points), but the gap has closed from −5.96 points to −1.53 points in 72 hours. If MOVE crosses 73 today, the war’s structural “rates vol has internalized the conflict” thesis breaks completely. The MOVE trajectory is now the cleanest leading indicator for whether the equity multiple expansion of the past two weeks unwinds.
S&P 500: ES 7,420 — War-High Premium Holds Through Three Inflation Shocks
ES at 7,420 (−0.09%, −6.5 pts) holds +7.8% above pre-war 6,881.62 — fractionally HIGHER than yesterday’s 7,412 close despite the PPI bomb. The cumulative ES gain from pre-war is now +538.38 points. The market’s ability to maintain the war-high premium THROUGH Tuesday’s hot CPI AND today’s PPI explosion AND the 30Y breaching 5.00% is the most resilient single behavioral signal of the war. The Tuesday-Wednesday combination (CPI Core 0.4% beat / PPI Core 1.0% beat / 30Y crosses 5.00%) was the cleanest possible “bearish-triple” — and the equity tape absorbed it with a 0.4% drawdown. The structural read is that institutional capital has decided the war and the inflation are not regime-altering risks for the equity multiple AT this premium. The question over the next 48 hours is whether that conviction is tested by the Warsh chair vote, Retail Sales tomorrow, and AMAT earnings.
Key Levels & Cumulative War Moves
Volatility & Breadth — Rates Vol Expanding, Equity Vol Compressing
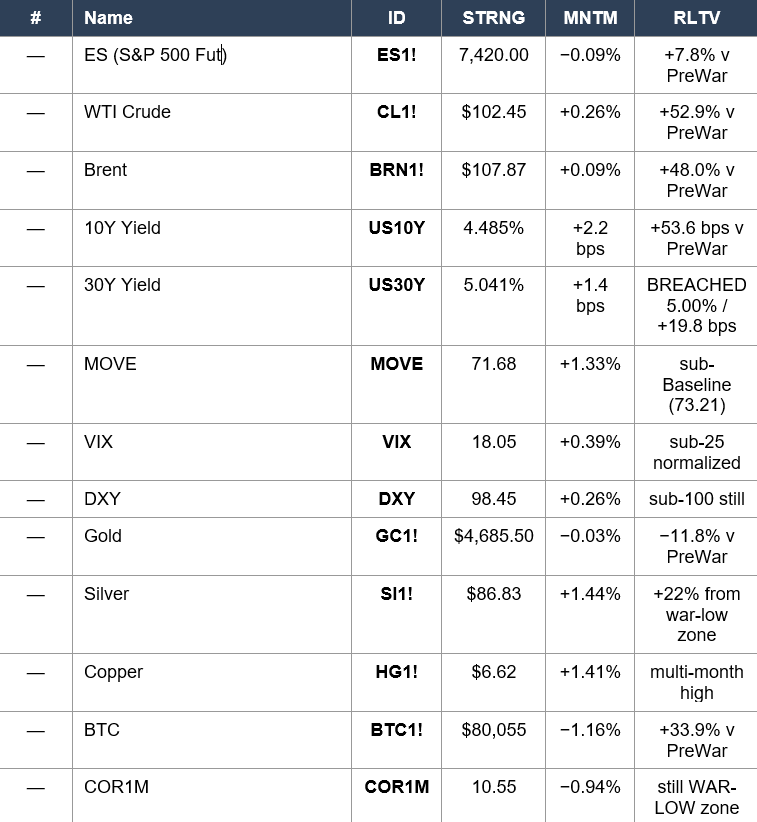
The vol complex is showing a textbook divergence: MOVE +1.33% (rates vol expanding for a fourth session), but VXN Nasdaq-vol −2.47%, VIX1D −5.82% (decaying because today’s event PPI is now released and the next pressure point is Friday Warsh swearing-in). VIX +0.39% essentially flat. VVIX +0.50% flat. GVZ Gold-Vol −1.16% compressing. The vol read tells the precise regime: the bond market is in active vol expansion (rates vol matters); the equity market is in single-name-dispersion compression (correlation low, idiosyncratic returns dominate). Breadth: S5TH 70.10, S5FI 61.30, R2TH 51.20 — unchanged from prior sessions, no breadth degradation visible. COR1M at 10.55 (−0.94%) — correlation drifted back toward the war low, confirming the cross-sector rotation is the dominant flow rather than directional macro selling.
6. THE GAME PLAN
Today: Core PPI 1.0% MASSIVE BEAT (10x prior), Headline PPI 1.4% MASSIVE BEAT (3x prior). 30Y BREACHED 5.00% to 5.041%. Bear Steepener regime engaged. Warsh Senate chair vote 2:30 PM (board vote yesterday passed 51-45 party-line). Thu: Retail Sales 8:30 + CSCO/BABA AMC + AMAT AMC. Fri: Powell’s term ends, Warsh sworn in.
The Bull Case
ES 7,420 holds +7.8% above pre-war — through Tuesday’s hot Core CPI AND today’s PPI explosion AND the 30Y breaching 5.00%, the war-high premium is intact. The market’s behavioral resilience is the cleanest single signal of structural risk-on conviction. MOVE 71.68 remains BELOW the 73.21 pre-war baseline despite four consecutive expansion sessions — rates vol has not yet broken the war’s structural disinflation framework. 34 Macro Tuesday close shows the rotation INTO defensives and Energy without breaking the tech leadership: XLK still #1 at STRNG 78 / RLTV 1.15. XLE has CROSSED ABOVE BASELINE at RLTV 1.01 — the Energy Phoenix is back. Copper (CPER) STRNG 73 / RLTV 1.04 — copper Leaders-tier for four sessions confirming global demand resilience. Silver (SLV) RLTV 1.00 baseline reclaimed; +22% from war-low zone. Bitcoin (IBIT) STRNG 62 / RLTV 1.10 still Leaders-class. AAPL +0.72%, META +0.69%, NVDA +0.61% catching defensive-quality bids pre-market — quality Mag 7 names absorbing the rate move. Defensive sectors XLV +1.96%, XLP +1.28%, XLF +0.78% leading — the rotation is occurring WITHIN the equity complex rather than out of it. If Warsh chair vote passes cleanly at 2:30 PM, Retail Sales tomorrow prints inline, and AMAT delivers a constructive AI-capex confirmation, the equity multiple holds the war-high premium into the Friday Warsh handoff.
The Bear Case
Core PPI 1.0% is 10X the prior month’s 0.1% — a single-month acceleration of an order that does not exist in normal-cycle data. Headline PPI 1.4% is nearly 3x prior. Combined with Tuesday’s Core CPI 0.4% beat and Headline YoY 3.8% (highest since 2022), the inflation regime has visibly re-engaged on BOTH the consumer-side AND the producer-side simultaneously. 30Y at 5.041% — BREACHED the 5.00% crisis threshold on a methodical Bear Steepener (the most bearish curve configuration for risk assets). MOVE up 4 consecutive sessions from war low 67.25 → 71.68 (+6.6%). Yield curve has FLIPPED from Bear Flattener to Bear Steepener. XLK Technology fell from STRNG 85 to 78 (−7) Tuesday — the war-high tech run is over. SMH Semis fell from STRNG 82 to 74 (−8). Defensive rotation engaged: USMV−SPHB spread flipped from −2.34% Monday to +1.85% today (a 4.19-point swing in two sessions). SOXX −3.15% pre-market — semis breaking. TSLA reversed yesterday’s +3.89% with a −2.60% drop today. International equity cracked: AAXJ STRNG 74 → 61 (−13), EEM STRNG 71 → 60 (−11). Warsh chair vote at 2:30 PM into a Bear Steepener with 30Y at 5.041%; the board vote was 51-45 party-line (the most partisan Fed chair confirmation vote in modern history). Miran (the FOMC dove) exits the board with Warsh’s confirmation. Markets pricing 1-in-3 chance of a rate HIKE by December. If the 30Y closes above 5.00% AND MOVE crosses 73 AND tomorrow’s Retail Sales prints hot, the bond crisis framework is fully re-engaged and the equity multiple compression accelerates. Friday’s Powell-to-Warsh transition arrives into an inflation regime that has just exploded.
Regime: Bear Steepener — PPI Explosion / 30Y Breaches 5.00% — Defensive Rotation Engaged. The day’s defining inflection is the curve flip from Bear Flattener to Bear Steepener — historically the most bearish risk-asset configuration. The bond market is now pricing structural inflation, term-premium expansion, and a Fed that may have to hike rather than cut. The equity tape has held the war-high premium through the data trio (NFP / CPI / PPI), but the internal rotation into defensives is the cleanest regime inflection of the war. Friday’s Warsh handoff arrives into the most consequential cross-asset configuration of the 76-day war: 30Y above 5.00%, MOVE bouncing toward baseline, hot inflation on both the consumer-side and producer-side, oil at $102, and an FOMC stripped of its dovish dissent.
Watch List
Today 2:30 PM — Warsh Senate Chair Confirmation Vote
Yesterday’s board vote was 51-45 party-line (only Fetterman crossed). Today’s chair vote is expected to follow a similar margin. WATCH: 53-46 or similar = clean partisan passage, no surprise; 60+ = surprise bipartisan support, modest bond-market relief; 51-49 or narrower / failure = regime-break risk. Any commentary from Warsh post-vote on his “regime change” agenda will be parsed line-by-line. With the 30Y at 5.041% during the vote, any hawkish-leaning language could push the 30Y to 5.05-5.10% on the day.
Today — 30Y Above 5.00%: Crisis Threshold Breached
The 30Y’s structural break above 5.00% is the day’s most consequential technical development. Last sustained above 5.00% on Day 47-48 in late April; today’s breach arrived methodically on data rather than panic flow. Watch for: cash session close above 5.00% confirms the regime break; intraday retest of 5.00% as support (failed retest is the most bearish read); MOVE crosses 73 to confirm rates-vol regime is broken; any Fed-speak commentary on the long end (typically silent but newsworthy if it appears).
Thursday 8:30 AM — April Retail Sales + Core Retail Sales
Headline 0.5% m/m consensus (vs 1.7% prior — significant deceleration expected). Core 0.7% (vs 1.9%). With NFP +115K, hot Core CPI 0.4%, and explosive Core PPI 1.0% in the data, retail sales becomes the consumer-resilience confirmation. A HOT retail print (above 0.7%) would compound the inflation read and push the 30Y to 5.05-5.10%. A WEAK print (below 0.2%) would signal early consumer stress and provide modest bond-market relief.
Thursday AMC — AMAT (Applied Materials) Earnings
AMAT is the cleanest single AI-capex confirmation given SMH at STRNG 74 / MNTM +39 / RLTV 1.30 — even AFTER Tuesday’s −8 STRNG compression. AMAT’s China commentary (the export-control overhang), foundry orders (TSMC capex flow-through), and DRAM/NAND visibility will define SOXX’s near-term trajectory. A beat with constructive guide reasserts the AI thesis; a miss or cautious guide accelerates the semis compression. Also tonight: CSCO (Cisco — networking/enterprise tech), BABA (Alibaba — China consumer and EM consumption).
Friday May 15 — Powell’s Term Ends, Warsh Sworn In As Chair
Day 78 of Operation Epic Fury. Powell’s 8-year chair term officially ends; Warsh sworn in (assuming today’s 2:30 PM vote passes). Powell remains on the board until the Fed renovation probe concludes (his governor term doesn’t expire until 2028) — a meaningful institutional signal of resistance to Trump-Warsh axis pressure. Warsh inherits: 30Y above 5.00%, MOVE bouncing toward baseline, hot CPI + hot PPI just released, $102 WTI, an FOMC stripped of its dovish dissenter (Miran), and a market pricing 1-in-3 chance of a rate HIKE by December. The first Warsh FOMC is June 16-17. The Friday handoff is the most consequential single Fed-leadership transition since Powell took over in 2018.
Energy — XLE RLTV Back Above Baseline, AMLP / XES Emerging
XLE Energy crossed RLTV 1.00 → 1.01 on Tuesday — the Energy Phoenix trade is officially back after four sessions sub-baseline. USO RLTV at 1.73 is a NEW WAR HIGH for Crude relative strength. AMLP Midstream STRNG 56 → 62 (+6) — energy infrastructure is the new emerging leadership. XES Oil & Gas Equipment STRNG 59 → 61 with MNTM +21 / RLTV 1.14 — services and equipment commanding strength independent of XOP upstream weakness. The energy reflation trade has clarified: midstream and services (durable, fee-based) leading; upstream cyclical (XOP) lagging. If WTI sustains $100+, this configuration extends through the Warsh FOMC.
AI/Semis — XLK Held #1 But SMH Down −8 STRNG
XLK Tuesday close STRNG 78 / RLTV 1.15 — held the #1 sector rank but compressed from Monday’s war-high 85. SMH Tuesday close STRNG 74 / MNTM +39 / RLTV 1.30 — the −8 STRNG compression is the largest single-session SMH move of the war series. SOXX −3.15% pre-market today extends the compression. AMAT Thursday AMC is the structural catalyst — a beat resets the AI thesis; a miss accelerates the semis-as-defensive-rotation-funding-source flow. Watch closely as the largest single-stock catalyst of the week.
Morning check: Day 76. The data exploded. April Core PPI printed 1.0% month-over-month — ten times the prior month’s 0.1% and a 0.7-point beat versus the 0.3% consensus. Headline PPI 1.4% beat by 0.9 points and printed nearly 3x prior. The hottest single-month producer-prices print of the entire 76-day war series, an inflation re-acceleration so structurally rare it does not exist in normal-cycle data. The bond market response was immediate and decisive: the 30Y rose to 5.041% — BREACHING the 5.00% crisis threshold for the first time since Day 47-48 in late April. The curve has FLIPPED from yesterday’s Bear Flattener to today’s Bear Steepener — historically the most bearish configuration for risk assets, reflecting long-duration inflation pricing and term-premium expansion rather than near-term cut repricing. MOVE expanded another +1.33% to 71.68 — a fourth consecutive session of rates-vol expansion from Monday’s 67.25 war low. The cumulative MOVE trajectory: 67.25 → 70.74 → 71.68 in 72 hours, the gap to the 73.21 pre-war baseline collapsed from −5.96 to −1.53 points. WTI holds $102.45 / +52.9% from pre-war. Brent $107.87. The cross-asset rotation is the cleanest defensive inflection of the war: USMV Min-Vol +0.41%, SPLV Low-Vol +0.61% lead factors; VLUE Value −1.60%, SPHB High-Beta −1.44%, MTUM Momentum −1.12% all red. USMV−SPHB spread flipped from −2.34% Monday to +1.85% today — a 4.19-point swing in two sessions. XLV Health Care +1.96% leads sectors after Tuesday’s STRNG +11 surge from the war-low zone; XLP Staples +1.28%, XLF +0.78%; XLK Technology −1.51% and SOXX Semiconductor −3.15% red. TSLA $433 (−2.60%) reversed yesterday’s entire +3.89% rally. ES at 7,420 (−0.09%) holds +7.8% above pre-war — through Tuesday’s hot Core CPI AND today’s PPI explosion AND the 30Y crossing 5.00%, the war-high premium is intact. The 34 Macro Tuesday close told the rotation story before the PPI confirmed it: XLK compressed STRNG 85 → 78, SMH STRNG 82 → 74, QQQ STRNG 83 → 78; defensives rotated in with XLP STRNG 51 → 57 and XLV STRNG 39 → 50 (the largest single-session XLV strength gain of the war). XLE Energy RLTV CROSSED ABOVE baseline to 1.01 — the Energy Phoenix is officially back. Crude USO RLTV at 1.73 is a NEW WAR HIGH. Silver SLV RLTV reclaimed baseline 1.00 (from war low 0.60). The Warsh Senate chair confirmation vote drops at 2:30 PM into a 30Y above 5.00% and a Bear Steepener regime — yesterday’s board vote passed 51-45 party-line (only Fetterman crossed, the most partisan Fed chair confirmation in modern history). Stephen Miran’s board term ended with the confirmation — the FOMC’s sole dovish dissenter has exited. Friday May 15 is Powell’s last day as chair; Warsh sworn in if confirmed today. The next 48 hours — chair vote today, Retail Sales tomorrow, AMAT earnings tomorrow AMC, Warsh handoff Friday — define whether today’s regime inflection is contained or whether the bond crisis framework re-engages. Pressure, not panic. Regime, not reaction. The data has spoken, the curve has flipped, the 30Y has broken the line, and the FOMC dove is gone. The bell is about to ring.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.