

1. THE QUICK SCAN
Overnight Tape Summary: THE OIL SHOCK. CRUDE SURGES TO $96, BRENT NEARS $100. WTI +2.68% TO $96.27 — UP ~$7 IN THREE SESSIONS; BRENT +2.39% TO $98.29; HEATING OIL +3.70% — AN ACUTE OIL SHOCK NOW THE DOMINANT MACRO STORY. ES -0.26% TO 7,604.00 (FLAT NEAR HIGHS; CUM +10.50%). NQ -0.01% TO 30,708.25 (FLAT). RUT -0.65% (PULLED BACK). ADP BEAT — 122K VS 118K CONS (PRIOR 109K) — LABOR FIRM. OIL + ADP DROVE A HAWKISH BEAR FLATTENER: YIELDS RISING (2Y +4.1BPS 4.086%, 5Y +4.9BPS 4.221%, 10Y +3.8BPS 4.491%, 30Y +2.7BPS 4.991% — NEAR 5.00%). MAG 7 WHIPSAWED AGAIN (REVERSE OF TUE): AAPL +2.90%, TSLA +1.89% UP; MSFT -4.17%, GOOG -3.81% CRASHED; NVDA -0.69% (CONSOLIDATING); AMZN -1.81%. SOXX +5.79% TO $605 — EXPLODING (BROADENING PAST NVDA INTO AMD/AVGO/MU). ICLN +3.08%, DRIV +2.31%; CIBR +0.18% FLAT (PANW DIGESTED); FINX -2.78%, ARKW -2.02%. 7 OF 11 SECTORS GREEN (BROADENING): XLU +1.86%, XLK +1.25%, XLB +1.18%, XLE +1.15%, XLI +1.04%; XLC -1.76% WORST. MTUM +2.87% LEADS FACTORS; SMALL/MID GREEN. TUESDAY CLOSE: SPY +1 TO STRNG 76 (NEW BASELINE HIGH) — ROTATION BROADENED. SMH EXPLODED +4 TO 77 / RLTV 1.45 — NEW WAR RECORD. CLEAN ENERGY ROARED BACK (PBW 1.33, QCLN 1.30). CYCLICALS/BANKS/CHINA SURGED (XLI +5, KBE +7, FXI +12). METALS PULLED BACK: GOLD -0.95%, COPPER -1.58% — HAVEN BID REVERSED. BTC -0.70% TO $66,920. MOVE +0.14% TO 73.4328 (HOLDING +0.22 ABOVE PRE-WAR, 3RD SESSION). COR1M -2.66% TO 5.86 — NEW WAR-LOW. ISM SERVICES 10AM. NFP FRIDAY — CONS 85K.
The regime has found its dominant narrative: an oil shock. WTI surged +2.68% to $96.27 overnight, with Brent +2.39% to $98.29 (nearing $100) and Heating Oil +3.70% — and crude is now up roughly $7 in three sessions (from $89 Monday morning to $96 today). What began as a reflation re-emergence Monday has accelerated into an acute oil shock, the single most important macro input on the board. The transmission was immediate: combined with this morning’s ADP beat (122K actual vs 118K consensus, prior 109K), the oil surge drove a hawkish Bear Flattener — yields rising hard across the curve (2Y +4.1 bps to 4.086%, 5Y +4.9 bps to 4.221%, 10Y +3.8 bps to 4.491%, 30Y +2.7 bps to 4.991%, back near 5.00%). Firm labor + surging oil = the disinflation/rate-cut thesis under real pressure, two days before Friday’s NFP. ES −0.26% to 7,604.00 held roughly flat near the highs (cumulative +10.50% vs pre-war); NQ −0.01% flat; RUT −0.65% pulled back.
And the Mag 7 whipsawed again — almost the exact reverse of Tuesday. Yesterday NVDA roared +6.26% while META/TSLA/AMZN crashed; today AAPL +2.90% to $315.20 and TSLA +1.89% to $423.74 bounced, while MSFT −4.17% to $441.31 and GOOG −3.81% to $358.39 crashed. MSFT gave back all of Tuesday’s +2.28% and more (the software leader is “not the rotation destination today,” per the DYRH); GOOG extended its slide below $360; NVDA −0.69% to $222.82 simply consolidated its huge Tuesday gain. Two consecutive sessions of violent, near-opposite intra-Mag-7 rotation is the defining feature of this tape — the leadership baton is changing hands daily, and no megacap can hold the bid for two sessions running. This is dispersion in its purest form: COR1M compressed again to 5.86 — a NEW war-low (below Tuesday’s 6.02), the deepest single-stock dispersion of the entire 97-day war.
But beneath the megacap churn, the tape is genuinely broadening — and the semis are exploding. SOXX Semiconductor +5.79% to $605 even as NVDA itself was red (−0.69%) — the semi rally is broadening past the cap-weight leader into the second tier (AMD, AVGO, MU), exactly the healthy signature a narrowing market needs. This extends Tuesday’s extraordinary cash-close move, where SMH printed RLTV 1.45 — a new war record by a wide margin (the prior record was 1.35; NVDA’s +6.26% drove a relative-strength extreme never seen in the war). ICLN Clean Energy +3.08%, DRIV +2.31%, PAVE +1.63% extend. At the sector level, 7 of 11 are green — the broadest tape in days: XLU Utilities +1.86% (the rate-sensitive recovering even into rising yields), XLK +1.25%, XLB Materials +1.18%, XLE Energy +1.15%, XLI Industrial +1.04% — cyclicals and tech leading, with only XLC Communication Services −1.76% (the GOOG/META drag) meaningfully red. The factor tape confirms the broadening: MTUM Momentum +2.87% leads, with SPHB High-Beta +1.79%, VYM +1.24%, VLUE +1.10%, and small/mid-caps (IJH +0.91%, IJR +0.89%) green. The rotation that looked like churn Monday is resolving into a genuine broadening — semis + cyclicals + clean energy carrying as the software-megacap leaders take profits.
The commodity tape sharpened the regime read. Where Tuesday saw reflation AND haven both bid, today is an oil-only surge: WTI $96 / Brent near $100 ripping, but metals pulled back — Gold −0.95% to $4,476.90, Copper −1.58% to $6.571, Silver −1.81%, Platinum −1.55%, Palladium −2.79%. The haven bid reversed (gold down ~$77 from Tuesday’s $4,553) and even the copper-reflation trade paused — leaving oil as the singular, isolated commodity shock. An oil-only spike (Brent near $100) without a broad metals bid is a supply/geopolitical signal more than a demand/reflation signal — consistent with the Iran/Hormuz risk premium that has shadowed the entire war. BTC −0.70% to $66,920 (below $67K, extending the crypto slide). MOVE held at 73.4328 (+0.22 above pre-war, a third consecutive session at/above pre-war — the rates-vol all-clear remains over). VIX +2.79% to 16.20; VIX1D −7.50% to 8.88 (one-day vol cratering again — intraday calm into the data). PANW reported Tuesday night and CIBR is +0.18% flat this morning — a neutral/in-line digestion (no beat-surge, no crash) that leaves the cyber complex holding its 1.32 level. The catalyst path: ISM Services PMI at 10:00 AM (consensus 53.7), Treasury Secretary Bessent speaks at 10:00 AM, and Friday’s NFP (consensus 85K) into the June 16-17 Warsh FOMC. The structural read: the index trend holds, the broadening is real, but the oil shock + firm labor + rising yields are a hawkish cluster pressuring the rate-cut path into Friday.
The Number That Matters: WTI $96.27 (+2.68%) / Brent $98.29 Near $100 — An Acute Oil Shock, Up ~$7 In Three Sessions, Now The Dominant Macro Story. Combined With The ADP Beat (122K vs 118K), It Drove A Hawkish Bear Flattener (Yields Rising, 30Y Back At 4.991%). Mag 7 Whipsawed Again (MSFT -4.17% / GOOG -3.81% Crash, AAPL +2.90% / TSLA +1.89% Bounce). But SOXX +5.79% Explodes (Semi Rally Broadening Past NVDA) And 7/11 Sectors Green — The Tape Is Broadening. Tuesday Close: SPY +1 To 76, SMH RLTV 1.45 New Record, Clean Energy Roared Back. Metals Pulled Back (Gold -0.95%). COR1M War-Low 5.86.
This is the oil-shock session. Crude near $96 with Brent threatening $100 is now the macro variable that matters most — it is driving the curve (hawkish bear-flattener), the labor read (ADP beat compounds the inflation concern), and the rate-cut path (under pressure into Friday). Beneath it, the equity tape is doing something constructive: broadening. Semis are exploding beyond NVDA (SOXX +5.79%, SMH at a 1.45 record), cyclicals and clean energy are surging, the factor tape is broad (momentum +2.87%, small/mid-caps green), and 7 of 11 sectors are bid. The megacap leadership remains in violent daily churn (MSFT/GOOG crash today after NVDA/MSFT carried yesterday), and correlation is at a record war-low — but the broadening underneath suggests the rotation is healthy distribution into more names, not a top. The swing factor is the oil shock: if Brent breaks $100 and the bear-flattener deepens into a hot NFP Friday, the +10.50% war-premium market faces its first genuine macro headwind of the breakout.
The Setup: THE OIL SHOCK. WTI +2.68% To $96.27 / Brent Near $100 (Up ~$7 In 3 Sessions) + ADP Beat 122K Drive A Hawkish Bear Flattener (Yields Rising, 30Y 4.991%). Mag 7 Whipsaws Again (MSFT -4.17% / GOOG -3.81% Crash; AAPL +2.90% / TSLA +1.89% Bounce). SOXX +5.79% Explodes (Broadening Past NVDA); 7/11 Sectors Green; MTUM +2.87% Leads. Tuesday Close: SPY +1 To 76, SMH RLTV 1.45 New Record, Clean Energy Roared Back, Cyclicals/Banks/China Surged. Metals Pulled Back (Gold -0.95%, Copper -1.58%). MOVE Holds Above Pre-War. COR1M War-Low 5.86. ISM Services 10AM. NFP Friday Cons 85K.
2. OVERNIGHT SESSION RECAP
Asia — Nikkei +1.04% To A New High; Topix -0.56%
Nikkei 68,245 (+1.04%) ripping to a NEW cycle high, crossing 68,000 — Japan re-engaging the global semis/megacap rally (the Nikkei is semis/SoftBank-heavy, and SOXX +5.79% this morning maps directly to Japanese chip names). TOPIX 3,978.50 (−0.56%) RED — the broad Topix diverging from the cap-weighted Nikkei, the same narrowing-into-megacap signature visible globally. BOJ Governor Ueda spoke at 4:30 AM (no major surprise priced). EWJ Japan Tuesday close +2 to STRNG 64 / RLTV 0.97 (recovering). AAXJ Asia ex-Japan Tuesday close +2 to STRNG 73 / RLTV 1.11 (a new war-high), and FXI China EXPLODED +12 to STRNG 52 Tuesday — the Asia/EM complex is the standout broadening leg. The Asia tape: Japan semis ripping, broad Asia/EM strengthening, the Topix lagging.
Europe — DAX -0.99%, EuroStoxx -0.72% Pulled Back
DAX 24,902 (−0.99%) and EuroStoxx 50 6,068 (−0.72%) pulled back, reversing Tuesday’s EUR-CPI-driven surge — European equities giving back gains as the global oil shock (Brent near $100) and rising yields pressured the rate-sensitive European complex. EUR 1.1606 (−0.25%) softer (dollar firm on the rate-rise, DXY +0.28% to 99.445). GBP 1.3432 (−0.27%). FEZ Europe Tuesday close +2 to STRNG 60 / RLTV 0.95 (the Tuesday strength now fading). The European pullback is the oil-shock cross-current: an oil spike toward $100 is a net negative for energy-importing Europe, reversing Monday-Tuesday’s reflation-rotation bid. Watch whether the European weakness is a one-session oil-driven pullback or the start of a broader rate-sensitivity unwind.
US Pre-Market — ES Flat Near Highs; NQ Flat; RUT -0.65% Pulled Back
ES 7,604.00 (−0.26%, −19.75 pts) — roughly flat, holding near the highs despite the oil shock and rising yields (resilience). NQ 30,708.25 (−0.01%) essentially flat, holding near Tuesday’s close around 30,712 — the Nasdaq outperforming on the semi explosion (SOXX +5.79%) offsetting the MSFT/GOOG drag. RUT 2,916.90 (−0.65%) pulled back — small-caps reversing Tuesday’s recovery (the rising-yield / oil-shock backdrop pressuring rate-sensitive small-caps; the DYRH notes “large-cap defensiveness dominating”). Dow 51,150 (−0.49%) lagging. Cumulative ES vs pre-war 6,881.62: +10.50%. The index resilience near the highs — flat despite Brent near $100, ADP beat, and 30Y back near 5.00% — is notable: the market is absorbing the oil-shock/hawkish-repricing without breaking, cushioned by the semi/cyclical broadening. Technical levels: ES support at 7,544 (Tue war-high reference), 7,500, 7,460; resistance at 7,650, 7,700. NQ support at 30,332, 30,000; resistance at 30,750, 31,000.
Mag 7 Pre-Market — Whipsaw Reverses: AAPL +2.90% / TSLA +1.89% Up; MSFT -4.17% / GOOG -3.81% Crash
THE MAG 7 WHIPSAWED AGAIN — 2 GREEN / 5 RED, the near-exact reverse of Tuesday. AAPL $315.20 (+2.90%) — bounced sharply (reversing days of weakness; the laggard catching a bid). TSLA $423.74 (+1.89%) — bounced, “relatively stable” per the DYRH after its recent slide. But the prior leaders crashed: MSFT $441.31 (−4.17%) — the worst, giving back all of Tuesday’s +2.28% and more (software “is not the rotation destination today”); GOOG $358.39 (−3.81%) — extending its slide below $360 (the worst-performing megacap of the week). NVDA $222.82 (−0.69%) — consolidating its huge +6.26% Tuesday gain (and notably underperforming SOXX +5.79%, confirming the semi rally is broadening to AMD/AVGO/MU rather than concentrating in NVDA). AMZN $256.52 (−1.81%) red; META $597.63 (−0.47%) soft. Two sessions of violent, near-opposite Mag 7 rotation (NVDA/MSFT up Tuesday → MSFT/GOOG down today; META/TSLA down Tuesday → AAPL/TSLA up today) is the defining churn of the tape. No megacap holds the bid for two sessions; the leadership baton changes hands daily. This is the engine of the COR1M war-low (5.86) — pure single-stock dispersion.
Sectors — 7 Of 11 Green (Broadening); XLU +1.86% Leads; XLC -1.76% Worst
7 OF 11 SECTORS GREEN — the broadest sector tape in days, a genuine broadening. XLU Utilities +1.86% LEADS — the rate-sensitive defensive recovering even into rising yields (a contrarian bid, or rotation into the beaten-down utility complex after Monday’s −10 STRNG crash). XLK Technology +1.25% (semis offsetting the MSFT −4.17% drag). XLB Materials +1.18%, XLE Energy +1.15%, XLI Industrial +1.04% — the cyclical complex bid on the oil shock / reflation. XLRE Real Estate +0.51% (recovering), XLF Financials +0.06% (flat). RED: XLP Consumer Staples −0.24%, XLY Consumer Discretionary −0.51%, XLV Health-Care −0.97%, XLC Communication Services −1.76% (worst) — the GOOG −3.81% + META drag crushing comm services for a second session. The sector configuration: utilities + tech + cyclicals (materials, energy, industrials) green, with only comm-services meaningfully red — a far broader, healthier tape than the 2-of-11-green narrowing of Monday-Tuesday. The breadth is improving even as the megacaps churn.
Factors — MTUM Momentum +2.87% Leads; Broad Strength; Small/Mid Green
The factor tape is broadly strong — the cleanest broadening signal. MTUM Momentum +2.87% LEADS (the momentum factor surging — its rebalance has tilted toward the semis/cyclical winners, and momentum leading a broadening tape is constructive). SPHB High-Beta +1.79% (risk-on), VYM High-Dividend +1.24% (income/value bid), VLUE Value +1.10% (cyclical-value). IJH Mid-Cap +0.91%, IJR Small-Cap +0.89% (small/mid-caps green — broadening down-cap), DGRO Dividend-Growth +0.83%, SPLV Low-Vol +0.46% (even low-vol green), RSP Equal-Weight +0.40% (equal-weight green — the breadth confirmation). LRGF +0.18%. Roughly flat: USMV −0.02%, QUAL −0.09%. The configuration — momentum + high-beta + value + dividend + small/mid all green, with equal-weight participating — is broad-based factor strength, the opposite of the narrow megacap-only tape. The MTUM +2.87% leadership is the standout: momentum surging as the leadership broadens into semis/cyclicals confirms the rotation is a genuine widening, not a defensive churn.
Thematics — SOXX +5.79% Explodes (Broadening Past NVDA); ICLN +3.08%; FINX -2.78%
SOXX Semiconductor +5.79% to $605 — EXPLODING — the single biggest thematic move, and critically, it occurred WITH NVDA red (−0.69%), meaning the semi rally is broadening past the cap-weight leader into the second tier (AMD, AVGO, MU). This is the healthy broadening signature — a semi rally that no longer depends on NVDA alone. ICLN Clean Energy +3.08% (extending Tuesday’s roar-back), DRIV Autonomous & EV +2.31%, PAVE Infrastructure +1.63%, ARKQ Autonomous +1.40% — the clean-energy/autonomous/infrastructure cohort bid. CIBR Cybersecurity +0.18% — flat (digesting PANW’s Tuesday-night report neutrally; no beat-surge, no crash; CIBR holds its 1.32 level). RED: ITA Aerospace Defense −0.69%, BLOK −1.22%, ARKW Next-Gen Internet −2.02%, ARKG Genomic −2.16%, FINX FinTech −2.78% (worst) — the internet/genomic/fintech complex pulled back (the software/growth-adjacent names taking profits alongside MSFT). The thematic tape: SOXX + clean-energy + autonomous + infrastructure bid (the broadening cohort), while internet/fintech/genomic sold (the software-adjacent profit-taking). Leadership is rotating from software-internet toward semis-cyclicals-clean energy.
Commodities — Oil Shock ($96 WTI / Brent ~$100); Metals Pulled Back; BTC Below $67K
THE OIL SHOCK IS THE STORY: WTI $96.27 (+2.68%), Brent $98.29 (+2.39%) nearing $100, Heating Oil +3.70%, RBOB +1.21% — crude up roughly $7 in three sessions, an acute and accelerating energy spike. Natural Gas $3.161 (−0.19%) flat. Ethanol +1.75%. But the rest of the commodity complex PULLED BACK — a notable divergence from Tuesday’s broad bid: Gold $4,476.90 (−0.95%) — down ~$77 from Tuesday’s $4,553 (the haven bid reversed), Copper $6.571 (−1.58%) (the reflation-metal paused), Silver −1.81%, Platinum −1.55%, Palladium −2.79% (precious + industrial metals all red). The oil-only surge — crude ripping while gold/copper fall — is a supply/geopolitical signal rather than a broad demand/reflation signal, consistent with the latent Iran/Hormuz risk premium of the war. Grains bid: Canola +2.28%, Soybean Oil +1.30%, Soybeans +0.56%. Softs mixed: Orange Juice +1.91%, Sugar +0.76%; Coffee −1.22%, Cocoa −1.73%. BTC $66,920 (−0.70%) — below $67K (extending the multi-day crypto slide from $72K). The commodity signature — isolated oil spike, metals down, crypto down — is a geopolitical-supply-shock read: the inflation tail is now an oil-price tail specifically, and an oil-only spike toward $100 is the cleanest stagflationary-risk signal of the war.
3. THE PRIOR DAY’S REGIME
34 Macro Price, Strength & Momentum Rankings — Daily Close, Tuesday June 2. SPY Baseline: STRNG 76 | MNTM +12 | RLTV 1.00. SPY +1 STRNG (New Baseline High) — The Rotation Broadened; Semis Exploded To A 1.45 Record.
Asset Classes — Leaders (SPY +1 To 76; FXI China +12; IWM Recovered)
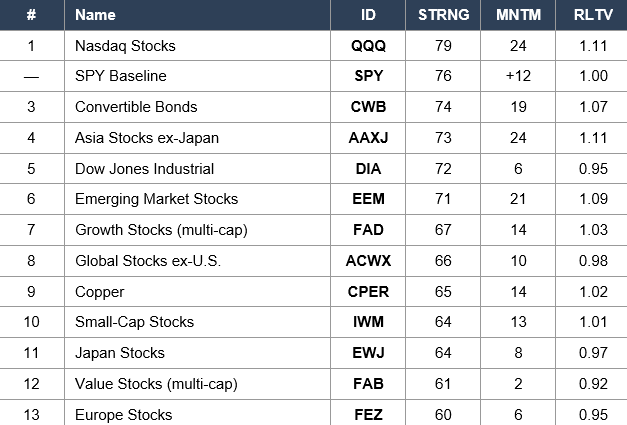
Asset Classes — Bonds Partially Recovered; Crypto Crashed (IBIT -8)
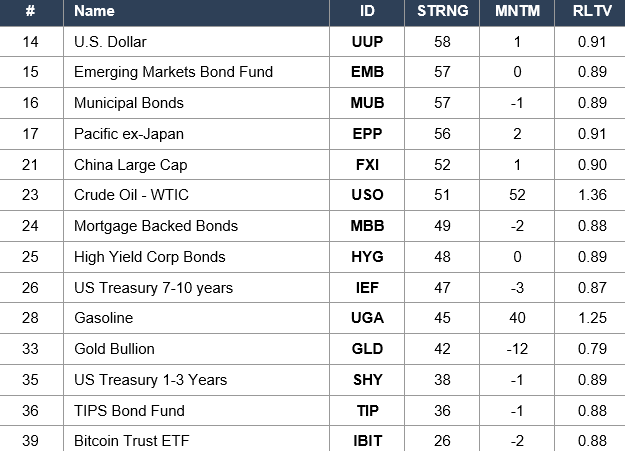
Regime signal: TUESDAY DELIVERED THE BROADENING — A NEW BASELINE HIGH WITH BREADTH IMPROVING ACROSS THE BOARD AND A SEMI EXPLOSION TO A RECORD. SPY baseline ROSE +1 to STRNG 76 (a new war-cycle baseline high). QQQ +1 to STRNG 79 / RLTV 1.11. The broadening was decisive: DIA Dow +3 to STRNG 72, FAD Growth +4 to STRNG 67 / RLTV 1.03, FAB Value +3 to 61, ACWX Global +3 to 66, EWJ Japan +2 to 64 — the broad equity complex strengthening, not just the megacaps. IWM Small-Cap RECOVERED +2 to STRNG 64 / RLTV 1.01 (back above 1.00 — the small-cap breadth repaired). THE INTERNATIONAL/EM COMPLEX SURGED: FXI China EXPLODED +12 to STRNG 52 (the single largest asset-class STRNG gain of the war), EPP Pacific +6 to 56, AAXJ Asia held STRNG 73 / RLTV 1.11 (a new war-high), EEM EM held 71 / RLTV 1.09. CPER Copper +3 to STRNG 65 / RLTV 1.02 (reflation extended). THE BOND COMPLEX PARTIALLY RECOVERED from Monday’s crash: EMB +2 to 57, MUB +2 to 57, PFF +2 to 54, TLT +1 to 53, HYG +1 to 48, IEF +1 to 47 — a stabilization bounce (though SHY held STRNG 38 and TIP held STRNG 36 — the front-end/TIPS damage from Monday persisted). GLD Gold +1 to STRNG 42 (modest recovery, before today’s −0.95% reversal). USO Crude +2 to STRNG 51 / RLTV 1.36 (the oil bid building into today’s shock). BUT CRYPTO CRASHED: IBIT Bitcoin −8 to STRNG 26, ETHA Ethereum −6 to STRNG 27 (the risk-off tell — crypto leading lower). VXX VIX Futures −2 to STRNG 31 (vol came back off into the close). The Tuesday configuration: a new high with broad participation (small-caps, value, international, China, cyclicals all up), bonds stabilizing, but crypto crashing — a constructive broadening with a risk-off undertone in crypto.
Sector ETFs (XLK RLTV 1.29 NEW High; Cyclicals Surged; XLU Recovered +9; XLC -9)
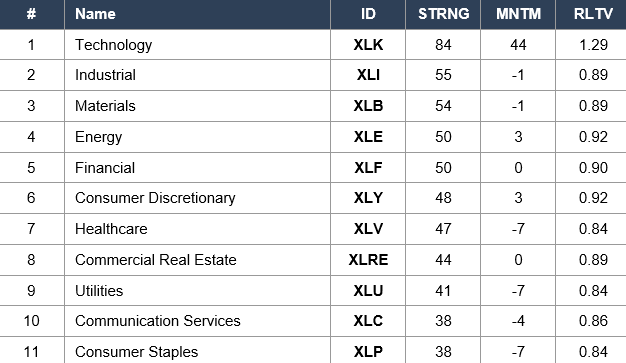
Regime signal: TUESDAY DELIVERED A NEW XLK RECORD ALONGSIDE A BROAD CYCLICAL RECOVERY — THE NARROWING BEGINNING TO BROADEN. XLK Technology EXTENDED +2 to STRNG 84 / RLTV 1.27 → 1.29 — a NEW war-cycle high RLTV (Tech now 29 percentage points above SPY baseline, extending its own record). But critically, the rest of the tape BROADENED: XLI Industrial SURGED +5 to STRNG 55, XLB Materials SURGED +5 to STRNG 54 (the cyclical complex strengthening on the reflation), XLE Energy +3 to STRNG 50 (oil bid), XLF Financials held 50, XLY Consumer Discretionary −2 to 48. XLU Utilities RECOVERED +9 to STRNG 41 (a sharp bounce off Monday’s −10 crash; the rate-sensitive repairing), XLRE Real Estate RECOVERED +3 to STRNG 44. XLV Health-Care −5 to 47 (continuing to fade), XLP Consumer Staples −1 to 38. But XLC Communication Services CRASHED −9 to STRNG 38 (the META-led comm-services unwind; now tied for the weakest sector). The Tuesday configuration: XLK at a record 1.29, but cyclicals (industrials, materials, energy) surging and the rate-sensitives (utilities, real estate) recovering — a meaningful broadening from Monday’s narrow tape, with only comm-services (META) and the defensives (health-care, staples) lagging. The leadership widened from Tech-only toward Tech-plus-cyclicals.
Industry ETFs — Leaders (SMH RLTV 1.45 NEW RECORD; Clean Energy Roared Back)
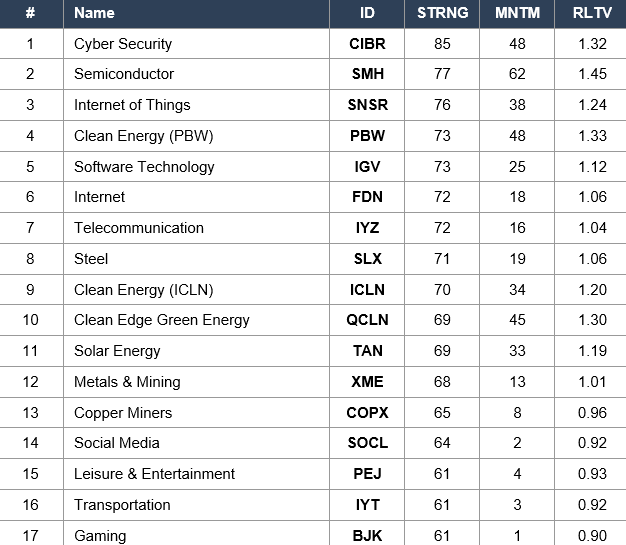
Industry ETFs — Banks/Energy/Uranium Surged; Fintech & Biotech CRASHED
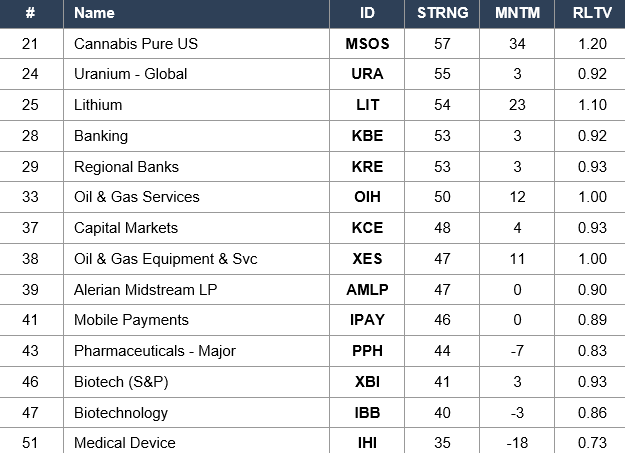
Regime signal: TUESDAY DELIVERED A SEMI EXPLOSION TO A RECORD AND A CLEAN-ENERGY/CYCLICAL ROAR-BACK — THE BROADENING MIRRORED AT THE INDUSTRY LEVEL. SMH Semiconductor EXPLODED +4 to STRNG 77 / RLTV 1.35 → 1.45 — a NEW war-cycle record by a wide margin (the prior record was 1.35; NVDA’s +6.26% drove the highest single-industry RLTV ever observed — semis at an unprecedented relative-strength extreme). CIBR Cybersecurity held STRNG 85 / RLTV 1.32 (digesting into the PANW print). THE CLEAN-ENERGY COMPLEX ROARED BACK: PBW Clean Energy +4 to STRNG 73 / RLTV 1.33 (new high), QCLN Clean Edge +5 to STRNG 69 / RLTV 1.30 (new high), ICLN +5 to STRNG 70 / RLTV 1.20, TAN Solar +2 to 69 / RLTV 1.19, SNSR IoT +5 to STRNG 76 / RLTV 1.24 — the entire clean-energy cohort surging to new/near-record RLTV. IYZ Telecom SURGED +8 to STRNG 72 / RLTV 1.04. The CYCLICAL/ENERGY complex broadened powerfully: SLX Steel +4 to STRNG 71 / RLTV 1.06, XME Metals & Mining +5 to STRNG 68 / RLTV 1.01, COPX Copper Miners +5 to 65, CRAK Oil Refiners +4 to 56, OIH Oil Services +8 to STRNG 50 / RLTV 1.00, XES Oil Equipment +8 to STRNG 47 / RLTV 1.00, AMLP Midstream +4 to 47, URA Uranium +9 to STRNG 55, REMX Rare Earth +4 to 54, LIT Lithium held 54 / RLTV 1.10. THE BANKS RECOVERED: KBE Banking +7 to STRNG 53, KRE Regional Banks +6 to STRNG 53 (reversing Monday’s crash). But the SOFTWARE/INTERNET/FINTECH/BIOTECH complex took profits: IGV Software −8 STRNG to 73, FDN Internet −8 STRNG to 72, IPAY Mobile Payments −11 to STRNG 46, XBI Biotech −11 to STRNG 41, IBB Biotech −9 to STRNG 40, KCE Capital Markets −8 to 48, PPH Pharma −4 to 44. The Tuesday configuration: semis at a 1.45 record, clean-energy/cyclicals/energy/banks/uranium broadening powerfully, but software/internet/fintech/biotech rotating out — a healthy widening of leadership into the reflation cohort, away from the software-megacap narrowing.
4. MORNING DATA REACTION
ADP BEAT 122K (Released 8:15 AM); ISM Services 10:00 AM; NFP Friday
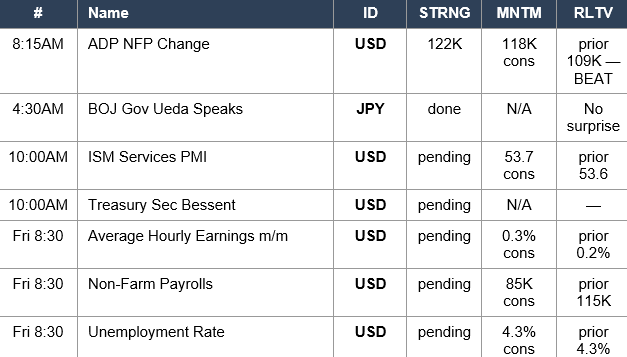
ADP Non-Farm Employment +122K — BEAT (vs 118K Cons, Prior 109K)
ADP printed at 8:15 AM: +122K actual vs +118K consensus (prior 109K) — a BEAT. Private payrolls came in firmer than expected, and the prior reading (109K) was solid — the labor market is holding up better than the market positioned for (recall Friday’s NFP consensus was CUT to 85K, implying expectations for a sharp cooling). The ADP beat is hawkish-leaning: a firm labor market reduces the urgency for Fed cuts, and it landed directly into the oil-shock backdrop, compounding the inflation/rates concern. The market response was immediate and clean — yields rose hard across the curve (2Y +4.1 bps, 5Y +4.9 bps, the bear-flattener), the dollar firmed (DXY +0.28%), and the rate-cut path was trimmed. The ADP beat is the first hard-data confirmation this week that the labor market is not cooling as fast as feared — raising the stakes for Friday’s NFP (consensus 85K): an NFP beat on top of ADP would seriously pressure the June-cut narrative, while a soft NFP would create a confusing ADP-vs-NFP divergence.
ISM Services PMI (10:00 AM) — The Growth + Prices Read Into NFP
ISM Services PMI at 10:00 AM (consensus 53.7 vs 53.6 prior — continued expansion expected). The services print is the larger read on the US economy (services dominate GDP), and its Prices-Paid subcomponent is the key inflation signal today — especially against the oil shock (Brent near $100 feeds services input costs). A hot ISM Services + hot Prices-Paid would confirm the no-landing/reflation backdrop and deepen the bear-flattener (compounding the ADP beat); a soft print would re-balance toward the cooling narrative. Treasury Secretary Bessent also speaks at 10:00 AM — watch for any commentary on the oil shock, the dollar, or Treasury issuance that could move the long end (already at 30Y 4.991%, back near 5.00%). The 10:00 AM block (ISM Services + Bessent) is the day’s key event into Friday’s NFP.
PANW Reported Tuesday Night — Digested Neutral (CIBR +0.18% Flat)
PANW (Palo Alto Networks) reported Q3 FY26 after the close Tuesday night. The cyber tape’s reaction is neutral: CIBR Cybersecurity is +0.18% (flat) this morning, holding its RLTV 1.32 level — neither the beat-driven surge toward 1.36+ nor the guide-down crash toward the Wednesday May 27 precedent (−12). The flat reaction suggests an in-line print (results roughly meeting the elevated expectations embedded in CIBR’s record positioning). With the binary now resolved neutrally, the cyber complex can consolidate its leadership without the overhang — CIBR remains the #1 industry at RLTV 1.32, but the leadership baton has clearly passed to semis (SMH 1.45) this week. Watch whether CIBR can re-accelerate or whether it cedes further ground to the broadening semi/cyclical complex.
This Week — NFP Friday (Cons 85K) Into A Hawkish Oil-Shock Backdrop
The week’s decisive catalyst is Friday’s NFP (consensus 85K, a sharp cooling vs 115K prior), Unemployment (cons 4.3%), and Average Hourly Earnings (cons 0.3% vs 0.2% prior). The setup has turned hawkish into the print: the ADP beat (122K) suggests labor is firmer than the 85K NFP consensus implies, and the oil shock (Brent near $100) is feeding inflation expectations. The risk asymmetry: an NFP beat + hot AHE on top of the oil shock would be a clear hawkish cluster, pressuring the +10.50% war-premium market and the June 16-17 rate-cut probability; a soft NFP would create an ADP-vs-NFP divergence and re-balance toward the cooling/cut narrative. With MOVE back above pre-war, the curve bear-flattening, and oil surging, the NFP lands into a market already re-pricing the easing path hawkishly — Friday is the highest-stakes print of the breakout.
5. THE DYRH READ
Yield Curve Regime: Bear Flattener — Yields Rising Hard On Oil + ADP
The curve is a Bear Flattener — yields RISING hard across the board on the oil shock + ADP beat: 2Y +4.1 bps to 4.086%, 5Y +4.9 bps to 4.221%, 10Y +3.8 bps to 4.491%, 30Y +2.7 bps to 4.991%. The front end is rising faster than the long end — a clean data-driven hawkish repricing (the ADP beat trimming cut expectations, the oil shock lifting inflation expectations). This is the SIXTH distinct curve reading in six sessions (Bull Steepener → Bull Flattener → Bear Flattener → Flattener Twist → Bull Steepener → Bear Flattener) — the curve continues to refuse a stable regime, but today’s move has clear conviction: rising yields on hard data + oil. 30Y at 4.991% is back near 5.00% (Day 4 below, now pressing the level from beneath) — a re-break above 5.00% would mark the disinflation milestone failing. The 2s/30s spread compresses to 90.5 bps. The front-end repricing (2Y +4.1 bps) is the cleanest signal: the market is trimming June-cut probability on the firm ADP + oil shock, two days before NFP. The bond market is no longer pricing a clean rate-cut cycle — it is pricing near-term inflation/rate risk.
MOVE Index: 73.43 (+0.14%) — Third Session At/Above Pre-War
MOVE held at 73.4328 (+0.14%) — now +0.22 above the pre-war baseline of 73.21, the THIRD consecutive session at or above pre-war. The nine-session compression all-clear is decisively and durably over: rates-vol has stabilized above the pre-war level rather than mean-reverting back below, confirming the inflection from compression to a sustained elevated-vol regime. From the war high of 115.02, MOVE has normalized 41.59 points, but the structural-calm backdrop that underwrote the equity melt-up (MOVE persistently sub-pre-war) is gone. Elevated and sticky rates-vol is the gravity-weight the DYRH flags — it constrains equity multiple expansion and raises the bar for the breakout to extend. The MOVE stabilization above pre-war, coinciding with the oil shock, the bear-flattener, and the ADP beat, confirms the rates regime has genuinely shifted. Watch whether MOVE accelerates higher into Friday’s NFP (a hawkish print would push it up) or holds in the low-73s.
S&P 500: ES 7,604.00 — Resilient Near Highs Despite The Oil Shock
ES at 7,604.00 (−0.26%) is holding roughly flat near the highs despite the oil shock (Brent near $100), the ADP beat, rising yields (30Y near 5.00%), and the dollar firming — a notable show of resilience. NQ 30,708.25 (−0.01%) flat, holding near Tuesday’s close, cushioned by the semi explosion (SOXX +5.79%). RUT −0.65% pulled back (small-caps the rate-sensitivity casualty). Cumulative ES vs pre-war 6,881.62: +10.50%. The index is absorbing a genuinely hawkish macro cluster (oil + firm labor + rising yields) without breaking — the semi/cyclical broadening is providing the offset to the MSFT/GOOG drag and the rate-sensitivity hit. The key question remains whether the broadening (semis past NVDA, cyclicals, clean energy, momentum factor) is durable enough to carry the index through the oil shock and Friday’s NFP, or whether a Brent break above $100 + an NFP beat tips the +10.50% premium market into its first real pullback. Technical levels: ES support at 7,544 (Tue war-high reference), 7,500, 7,460; resistance at 7,650, 7,700.
Key Levels & Cumulative War Moves
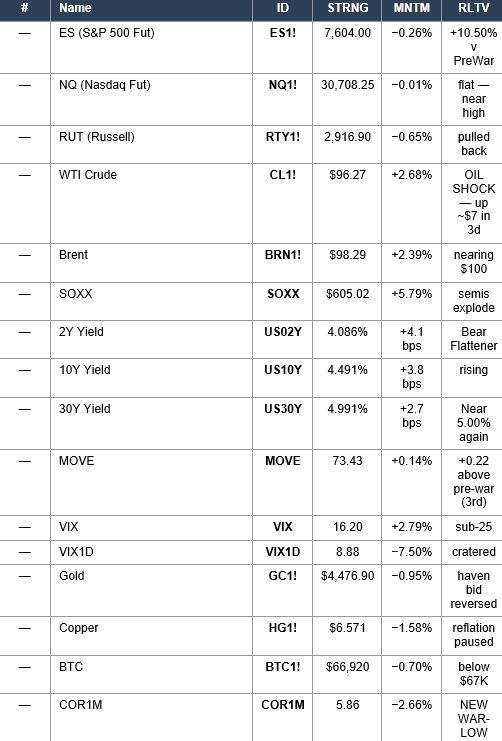
Volatility & Breadth — MOVE Sticky Above Pre-War; VIX1D Craters; COR1M War-Low
The vol complex is in a curious split. MOVE +0.14% to 73.43 — sticky above pre-war (third session), the structural signal that the rates-vol all-clear is over. VIX +2.79% to 16.20 (rising modestly, still sub-25). VXN +0.39% to 23.27 (Nasdaq-vol flat-to-higher). But VIX1D CRATERED −7.50% to 8.88 — the one-day vol collapsed to an extreme low (the third consecutive day of VIX1D compression), signaling the market sees no intraday risk even as MOVE/term-vol holds elevated; the hedging is concentrated in the medium term (Friday NFP, the oil trajectory) rather than the immediate session. VVIX −1.17% to 90.53 (vol-of-vol easing slightly). GVZ Gold-vol −4.68% to 24.44 (gold-vol compressing as gold pulls back). SKEW +0.55% to 143.24 (elevated — tail-hedges remain on). COR1M compressed to 5.86 — a NEW war-low (below Tuesday’s 6.02), the deepest single-stock dispersion of the entire war — driven by the daily Mag 7 whipsaw (MSFT −4.17% vs AAPL +2.90% today; NVDA +6.26% vs META −5.07% yesterday). The configuration — MOVE sticky-elevated + VIX1D cratering + COR1M at a record low + SKEW elevated — is a market with no intraday fear but persistent term-risk and inflation-tail hedging, churning through violent single-stock rotation. Trailing breadth (S5TH 70.10, S5FI 61.30) holds; the real-time tape (7/11 sectors green, small/mid-caps green, momentum +2.87%) is broadening.
6. THE GAME PLAN
Today: THE OIL SHOCK. WTI +2.68% to $96.27 / Brent near $100 (up ~$7 in 3 sessions) + ADP beat 122K drive a hawkish Bear Flattener (yields rising, 30Y 4.991%). Mag 7 whipsaws again (the reverse of Tuesday): MSFT −4.17% / GOOG −3.81% crash; AAPL +2.90% / TSLA +1.89% bounce; NVDA −0.69% consolidates. SOXX +5.79% explodes (broadening past NVDA into AMD/AVGO/MU); 7/11 sectors green (XLU +1.86%, XLK +1.25%, cyclicals); MTUM +2.87% leads factors; small/mid-caps green. Tuesday close: SPY +1 to 76 (new baseline high), SMH RLTV 1.45 new record, clean energy roared back (PBW 1.33, QCLN 1.30), cyclicals/banks/China surged (XLI +5, KBE +7, FXI +12). Metals pulled back (Gold −0.95%, Copper −1.58% — haven bid reversed). MOVE sticky above pre-war (3rd session). COR1M war-low 5.86. ISM Services 10AM (cons 53.7). NFP Friday cons 85K.
The Bull Case
The tape is broadening — the bullish resolution to the narrowing. SOXX +5.79% with NVDA red means the semi rally has broadened past the cap-weight leader (AMD, AVGO, MU) — the healthiest possible signature. Tuesday’s cash close confirmed the widening: SMH at a 1.45 record, clean energy roaring back (PBW 1.33, QCLN 1.30, ICLN 1.20), cyclicals surging (XLI +5, XLB +5, steel, copper miners, oil services), banks recovering (KBE +7, KRE +6), and China/international exploding (FXI +12, AAXJ 1.11). Today 7 of 11 sectors are green, small/mid-caps are green, and MTUM Momentum leads +2.87% — broad-based participation, not megacap-only. SPY made a new baseline high Tuesday (STRNG 76); ES holds +10.50% and is resilient near the highs despite the oil shock. The index is absorbing a hawkish macro cluster (oil + ADP beat + rising yields) without breaking — a sign of underlying strength. If ISM Services prints in-line and the broadening continues, the breakout extends on a wider base. A soft NFP Friday would re-engage the rate-cut path. Targets: ES 7,650 / 7,700, SOXX continuation, the broadening sustaining.
The Bear Case
The oil shock is a genuine macro threat. WTI $96 / Brent near $100, up ~$7 in three sessions, is an acute inflation/geopolitical spike — and an oil-only surge (gold −0.95%, copper −1.58% falling alongside) is a supply/geopolitical signal (Iran/Hormuz), the cleanest stagflationary-risk read of the war. Combined with the ADP beat (122K), it drove a hawkish bear-flattener: yields rising hard, 30Y back near 5.00%, the rate-cut path trimmed. MOVE is sticky above pre-war for a third session — the rates-vol all-clear that underwrote the melt-up is durably over, a structural headwind to the +10.50% premium. The Mag 7 is in violent daily whipsaw (MSFT −4.17% / GOOG −3.81% today after NVDA carried yesterday) — leadership that changes hands every session, with COR1M at a record war-low (5.86), is a churning, unstable tape where any catalyst can trigger a broad re-coupling. GOOG −3.81% and MSFT −4.17% are large megacap breaks; if the semi/cyclical broadening can’t offset continued megacap selling, the index rolls over. Crypto is leading lower (BTC below $67K, IBIT −8 Tuesday). The hawkish setup into Friday is dangerous: an NFP beat + hot AHE on top of the oil shock would be a clean hawkish cluster, and 30Y breaking 5.00% with oil near $100 would pressure the entire complex. Watch ES 7,544 — a break with oil surging and yields rising engages 7,500 / 7,460 fast.
Regime: THE OIL SHOCK — Crude Near $96 / Brent ~$100 Drives A Hawkish Bear Flattener (Yields Rising, ADP Beat 122K). Mag 7 Whipsaws Daily (MSFT/GOOG Crash Today, NVDA Carried Tuesday); COR1M War-Low 5.86. But The Tape Is Broadening — SOXX +5.79% Past NVDA, SMH 1.45 Record, Clean Energy Roared Back, 7/11 Sectors Green, MTUM +2.87% Leads. MOVE Sticky Above Pre-War (3rd Session) — The All-Clear Is Durably Over. Metals Pulled Back (Haven Reversed). Index Resilient Near Highs. Watch Brent $100 (Stagflation Tell), ISM Services 10AM (Prices), NFP Friday 85K (Hawkish Risk), 30Y 5.00%, ES 7,544 Support, The Broadening Vs The Megacap Churn.
Watch List
Oil — WTI $96 / Brent ~$100; The Dominant Macro Variable; Watch $100
The oil shock is now the macro variable that matters most. WTI +2.68% to $96.27, Brent +2.39% to $98.29 (nearing $100), up ~$7 in three sessions. Crucially, it is an oil-only spike — gold (−0.95%) and copper (−1.58%) fell alongside — marking it a supply/geopolitical signal (Iran/Hormuz risk premium) rather than a broad demand/reflation move. This is the stagflationary-risk read: rising oil + slowing-then-firm labor + rising yields. Watch Brent $100 (a break would be a psychological and inflation-expectations trigger, deepening the bear-flattener and pressuring the rate-cut path) and WTI $97-98 (the next resistance). The oil trajectory will drive the curve, the Fed-cut probability, and the equity multiple into Friday’s NFP. XLE +1.15% and the energy-equity complex (CRAK, OIH, XES, XOP) are the cyclical beneficiaries; the rate-sensitives (utilities ex-today, REITs) and the consumer are the casualties.
Semis — SOXX +5.79% Broadening Past NVDA; SMH 1.45 Record; The Bull Anchor
SOXX +5.79% to $605 with NVDA red (−0.69%) is the session’s most bullish signal: the semi rally has broadened past the cap-weight leader into AMD, AVGO, MU. This extends Tuesday’s SMH RLTV 1.45 record (the highest single-industry RLTV ever in the war). A semi rally that no longer depends on NVDA alone is the healthy broadening a narrowing market needs. Watch whether SOXX can hold the $605 breakout and whether SMH sustains the 1.45 record — a semi complex broadening to its second tier is the strongest argument that the breakout extends on a wider base. The risk: SMH at 1.45 is at an unprecedented extreme; mean-reversion from a record is sharp if the AI-capex narrative wobbles. Semis are the single most important sector to watch — the bull anchor of the broadening thesis.
Mag 7 Whipsaw — MSFT -4.17% / GOOG -3.81% Crash; The Daily Rotation Churn
The Mag 7 whipsawed again, the reverse of Tuesday: MSFT −4.17% and GOOG −3.81% crashed (after NVDA/MSFT carried Tuesday), while AAPL +2.90% and TSLA +1.89% bounced. MSFT gave back all of Tuesday’s gain (software “not the rotation destination today”); GOOG is the worst megacap of the week. NVDA −0.69% consolidated. Two sessions of violent, near-opposite rotation is the churn that drives the COR1M war-low (5.86). Watch whether the rotation stays orderly (semis/cyclicals absorb the flows, index holds — the broadening thesis) or whether the megacap selling broadens into contagion (MSFT below $440, GOOG below $355 would accelerate). The daily leadership baton-pass is the defining instability of the tape — constructive if it reflects broadening, dangerous if it reflects distribution.
Rates — Bear Flattener, 30Y Near 5.00%; MOVE Sticky Above Pre-War; ADP Beat
The rates complex turned decisively hawkish: the ADP beat (122K) + oil shock drove a Bear Flattener with yields rising hard (2Y +4.1 bps, 30Y +2.7 bps to 4.991%, back near 5.00%). MOVE is sticky above pre-war (73.43, +0.22, third session) — the rates-vol all-clear is durably over. Watch 30Y 5.00% (a re-break above marks the disinflation milestone failing — a clear hawkish signal that would pressure equity multiples), the front-end 2Y (cut-probability proxy — rising means cuts being priced out), and MOVE’s trajectory into NFP. The rates complex is the master variable: an oil-driven, ADP-confirmed hawkish repricing into a hot NFP Friday is the bearish scenario; a soft NFP that re-anchors the curve is the bullish offset.
ISM Services 10AM + Bessent — The Growth/Prices/Issuance Read
ISM Services PMI at 10:00 AM (cons 53.7) is the day’s key US growth read, and its Prices-Paid subcomponent is the inflation tell against the oil shock. A hot ISM + hot Prices-Paid deepens the bear-flattener and the hawkish setup into NFP; a soft print re-balances. Treasury Secretary Bessent speaks at 10:00 AM — watch for commentary on the oil shock, the dollar (DXY firming), or Treasury issuance that could move the long end (30Y near 5.00%). The 10:00 AM block is the bridge between the ADP beat this morning and the NFP Friday — a hot ISM Services would compound the hawkish cluster.
The Broadening — 7/11 Sectors Green / MTUM Leads / Clean Energy Roared Back
The broadening is the bull thesis, and it is gaining substance. Today: 7 of 11 sectors green (utilities, tech, materials, energy, industrials, real estate, financials), small/mid-caps green (IJH +0.91%, IJR +0.89%), MTUM Momentum leading +2.87%, equal-weight RSP green. Tuesday: clean energy roared back (PBW 1.33, QCLN 1.30, ICLN 1.20, TAN 1.19, SNSR 1.24), cyclicals surged (steel, copper miners, oil services, uranium), banks recovered (KBE +7, KRE +6), China/international exploded (FXI +12, AAXJ 1.11). Watch whether the broadening sustains a second/third session — a durable widening of leadership beyond the megacaps (into semis-second-tier, cyclicals, clean energy, small-caps) would confirm the breakout extends on a healthy base, surviving the megacap churn. A reversal back to megacap-only leadership would signal the broadening was a one-off reflation reflex. This is the swing question for the trend.
Morning check: Day 97. THE OIL SHOCK — crude surges to $96, Brent nears $100. WTI +2.68% to $96.27 (up ~$7 in three sessions from $89 Monday), Brent +2.39% to $98.29, Heating Oil +3.70% — an acute oil shock now the dominant macro story. ES −0.26% to 7,604.00 (flat near the highs; cumulative +10.50% vs pre-war 6,881.62); NQ −0.01% to 30,708.25 (flat); RUT −0.65% to 2,916.90 (pulled back); Nikkei +1.04% to 68,245 (new high); DAX −0.99%, EuroStoxx −0.72% (Europe pulled back on the oil shock). ADP printed +122K vs +118K consensus (prior 109K) — a BEAT; labor firm, hawkish-leaning. The oil + ADP combination drove a hawkish Bear Flattener — yields rising hard: 2Y +4.1 bps to 4.086%, 5Y +4.9 bps to 4.221%, 10Y +3.8 bps to 4.491%, 30Y +2.7 bps to 4.991% (back near 5.00%, the sixth distinct curve reading in six sessions). The Mag 7 whipsawed again (the reverse of Tuesday): AAPL +2.90% to $315.20, TSLA +1.89% to $423.74 UP; but MSFT −4.17% to $441.31 (gave back all of Tuesday’s gain — “not the rotation destination today”) and GOOG −3.81% to $358.39 (worst megacap of the week) CRASHED; NVDA −0.69% to $222.82 (consolidating its +6.26%, underperforming SOXX); AMZN −1.81% to $256.52; META −0.47% to $597.63. SOXX Semiconductor +5.79% to $605 — EXPLODING with NVDA red (the semi rally broadening past the cap-weight leader into AMD/AVGO/MU — the healthy signature). ICLN +3.08%, DRIV +2.31%, PAVE +1.63%, ARKQ +1.40%; CIBR +0.18% flat (PANW digested neutral — in-line, holding RLTV 1.32); FINX −2.78%, ARKW −2.02%, ARKG −2.16% (internet/fintech/genomic took profits). 7 of 11 sectors green (broadening): XLU +1.86% (leads), XLK +1.25%, XLB +1.18%, XLE +1.15%, XLI +1.04%, XLRE +0.51%, XLF +0.06%; XLC −1.76% worst (GOOG/META drag), XLV −0.97%, XLY −0.51%, XLP −0.24%. MTUM Momentum +2.87% leads factors; SPHB +1.79%, VYM +1.24%, VLUE +1.10%; IJH +0.91%, IJR +0.89% (small/mid green); RSP equal-weight +0.40% (breadth confirmation). MOVE +0.14% to 73.4328 — sticky +0.22 above pre-war (third consecutive session at/above pre-war; the nine-session compression all-clear durably over). VIX +2.79% to 16.20; VXN +0.39% to 23.27; but VIX1D −7.50% to 8.88 (cratered — no intraday fear); VVIX −1.17% to 90.53; SKEW +0.55% to 143.24 (elevated). COR1M −2.66% to 5.86 — NEW war-low (below Tuesday 6.02; deepest single-stock dispersion of the war — driven by the daily Mag 7 whipsaw). Metals PULLED BACK (haven bid reversed): Gold −0.95% to $4,476.90 (down ~$77 from Tuesday’s $4,553), Copper −1.58% to $6.571, Silver −1.81%, Platinum −1.55%, Palladium −2.79% — leaving oil as the isolated, singular spike (a supply/geopolitical signal, the stagflationary-risk read). BTC −0.70% to $66,920 (below $67K, extending the crypto slide). DXY +0.28% to 99.445 (dollar firm on the rate-rise). Tuesday cash close: SPY +1 to STRNG 76 (new baseline high) — the rotation BROADENED. SMH Semiconductor EXPLODED +4 to STRNG 77 / RLTV 1.35 → 1.45 — a NEW war record by a wide margin (NVDA’s +6.26% drove the highest single-industry RLTV ever). CIBR held 85 / RLTV 1.32. Clean energy ROARED BACK: PBW +4 to 73/1.33, QCLN +5 to 69/1.30, ICLN +5 to 70/1.20, TAN 69/1.19, SNSR +5 to 76/1.24. Cyclicals/energy surged: XLI +5 to 55, XLB +5 to 54, SLX +4 to 71/1.06, XME +5 to 68/1.01, COPX +5 to 65, CRAK +4 to 56, OIH +8 to 50/1.00, XES +8 to 47/1.00, AMLP +4 to 47, URA +9 to 55, REMX +4 to 54. Banks recovered: KBE +7 to 53, KRE +6 to 53. International surged: FXI China +12 to 52 (largest asset-class gain of the war), EPP +6 to 56, AAXJ 73/1.11 new high. XLK +2 to 84/1.29 (new high); XLU +9 to 41 (recovered); XLRE +3 to 44. IWM Small-Cap +2 to 64/1.01 (recovered above 1.00). Bonds partially recovered: EMB +2, MUB +2, PFF +2, TLT +1, HYG +1, IEF +1 (SHY held 38, TIP held 36). But software/internet/fintech/biotech took profits: IGV −8 STRNG to 73, FDN −8 STRNG to 72, IPAY −11 to 46, XBI −11 to 41, IBB −9 to 40, KCE −8 to 48; XLC −9 to 38 (META drag). Crypto crashed: IBIT −8 to 26, ETHA −6 to 27. ADP 122K BEAT (8:15AM, done); ISM Services 10:00 AM (cons 53.7 / prior 53.6) + Treasury Sec Bessent 10:00 AM; BOJ Ueda 4:30 AM (no surprise). PANW reported Tuesday night — digested neutral. This week: Fri NFP (cons 85K), Unemployment (4.3%), AHE m/m (0.3%) — into the June 16-17 Warsh FOMC; the setup has turned hawkish (ADP beat + oil shock). The narrative arc: RESOLUTION → EXTENSION → ACCELERATION → CONSOLIDATION → CONFIRMATION → NARROWING → HANDOFF → and now THE OIL SHOCK. The index trend holds (SPY new baseline high Tuesday, ES resilient +10.50%), and critically the tape is BROADENING (SOXX +5.79% past NVDA, SMH 1.45 record, clean energy roared back, cyclicals/banks/China surged, 7/11 sectors green, momentum +2.87%, small/mid-caps green) — the bullish resolution to the narrowing. But the macro turned hawkish: an oil shock (Brent near $100, an isolated supply/geopolitical spike with metals falling), a firm ADP (122K beat), a bear-flattener (30Y near 5.00%), MOVE sticky above pre-war, and the Mag 7 in violent daily whipsaw (MSFT/GOOG crashed today) with correlation at a record war-low (5.86). Watch Brent $100 (stagflation tell), ISM Services 10AM (Prices-Paid), NFP Friday 85K (hawkish risk on top of ADP), 30Y 5.00% (disinflation-milestone failing), ES 7,544 support, SOXX/SMH (the bull anchor), and the broadening (7/11 green, clean energy, cyclicals) vs the megacap churn (MSFT/GOOG). Pressure, not panic. Regime, not reaction. The oil shock is the macro now — crude near $100 drives the curve, the Fed path, and the multiple, while the equity tape broadens beneath the megacap churn. Resilient, but the hawkish cluster is building into Friday.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.