

1. THE QUICK SCAN
Overnight Tape Summary: RETAIL SALES INLINE. WARSH CONFIRMED 54-45 — SLIMMEST FED CHAIR MARGIN EVER. ES AT NEW WAR HIGH 7,493.25 (+8.9% ABOVE PRE-WAR). MOVE COMPRESSED −2.01% TO 70.24 — FIRST COMPRESSION IN FIVE SESSIONS. 30Y FELL TO 5.008% — STILL ABOVE 5.00% BUT ONLY 0.8 BPS NOW. YIELD CURVE FLIPPED TO BULL STEEPENER — THE MOST BULLISH CONFIGURATION. WTI PULLED BACK TO $100.26 (−0.75%) — RELEASING WAR-PREMIUM AFTER WEDNESDAY’S $103 PEAK. MAG 7 ROARED BACK: GOOG +3.97%, TSLA +2.73%, NVDA +2.29%, META +2.26%, AMZN +1.62%, AAPL +1.38%; ONLY MSFT −0.63%. SOXX +2.38% RECOVERING WEDNESDAY’S −3.15% PLUNGE. EUROPE RIPPED: DAX +1.43%, EUROSTOXX +1.34% ON UK GDP BEAT (0.3% VS −0.1%). 34 MACRO WEDNESDAY CLOSE: SPY 76 / QQQ 79 / XLK 79 / SMH 76 — TECH REBUILT. AMAT EARNINGS AMC TONIGHT. POWELL’S TERM ENDS TOMORROW. WARSH SWORN IN FRIDAY.
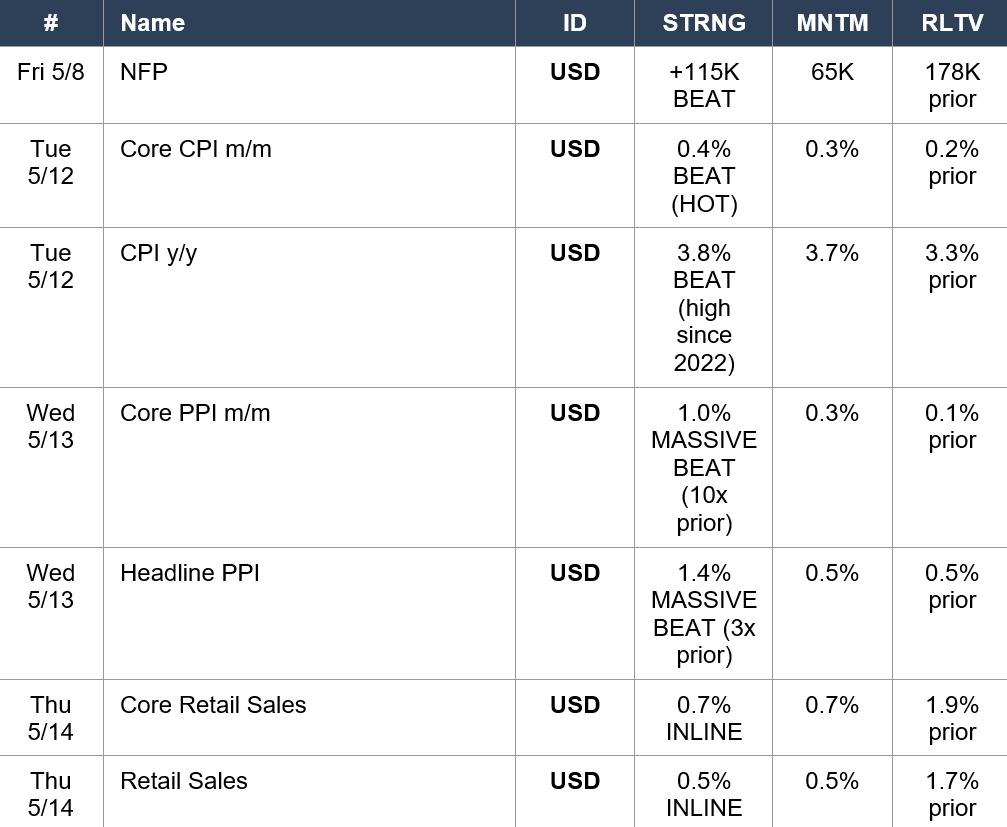
The week’s defining trio is complete and the market’s verdict is in. Retail Sales printed exactly inline: headline 0.5% m/m (vs 0.5% consensus / 1.7% prior) and Core Retail Sales 0.7% (vs 0.7% / 1.9% prior). The deceleration from March’s blowout 1.7% / 1.9% prints is sequential and orderly — the consumer is decelerating but not breaking, exactly the soft-landing read the bull case needed. Combined with Friday’s NFP +115K beat (labor resilient), Tuesday’s hot Core CPI 0.4% beat (inflation re-accelerating), and yesterday’s explosive Core PPI 1.0% beat (producer prices exploding), the week’s data tells a coherent story: the consumer is HOLDING despite the inflation impulse, the labor market is RESILIENT despite the deceleration, and the inflation pressure is REAL but the regime is not breaking. This is the cleanest possible “stagflation-lite with the labor anchor holding” framework.
And the bond market’s response is the key signal. Yields fell across the curve overnight into a clean Bull Steepener — yields falling at every tenor with the long end falling faster: 2Y −1.4 bps to 3.963%, 5Y −2.2 bps to 4.092%, 10Y −2.2 bps to 4.445%, 30Y −2.6 bps to 5.008%. The 30Y is back within 0.8 bps of the 5.00% crisis threshold and the trajectory has reversed. MORE IMPORTANTLY, MOVE compressed −2.01% to 70.24 — the FIRST COMPRESSION IN FIVE SESSIONS after the Day 74 war-low 67.25 → Day 76 expansion to 71.68. The MOVE’s ability to compress on the SAME DAY that the 30Y closed above 5.00% AND Warsh was confirmed in the slimmest margin ever is the cleanest cross-asset statement of the week: the bond market is absorbing the entire data trio. Bull Steepeners are historically the most bullish curve configuration for risk assets — they signal that the disinflation path is intact AND the cycle is durable.
Warsh was confirmed as the 11th Fed chair Wednesday afternoon in a 54-45 vote — the SLIMMEST CONFIRMATION MARGIN IN MODERN FED CHAIR HISTORY. The vote was near party-line with only Senator John Fetterman (D-PA) crossing. Senator Kirsten Gillibrand (D-NY) missed the vote. Warsh’s confirmation arrives directly into the most-divided FOMC since the early 1990s (the 8-4 May 6 vote). Stephen Miran’s board term ended with Warsh’s arrival — the FOMC’s consistent dovish dissenter is now off the board. Warsh has publicly committed to: (1) reforming inflation measurement (potentially replacing headline PCE with trimmed-mean PCE), (2) limiting Fed communications (a sharp pivot from the transparency expansion of the Powell era), (3) targeting a smaller balance sheet, and (4) a “lower” policy rate path. Powell’s chair term ends tomorrow Friday May 15; Powell will REMAIN on the board until the renovation probe concludes (his governor term doesn’t expire until 2028) — only the second time in nearly 80 years a Fed chair has stayed on the board after leaving the top role. The institutional friction is the cleanest political-economy backdrop the Fed has had in decades.
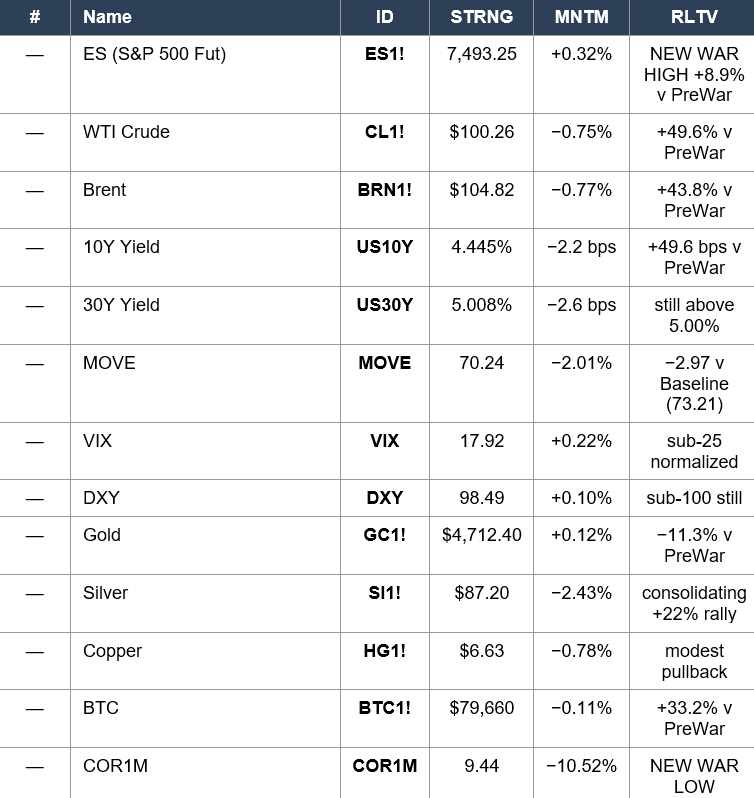
The equity tape captured the verdict before the data and the vote even arrived. ES at 7,493.25 (+0.32%, +24 pts) is a NEW WAR HIGH — the cumulative premium versus pre-war 6,881.62 is now +8.9%, the highest of the 77-day war. The market’s ability to ABSORB the data trio (hot CPI / explosive PPI / 30Y above 5.00%) AND make fresh highs is the most resilient single behavioral signal of the entire conflict. Cross-asset risk-on is broad: DAX +1.43% and EuroStoxx +1.34% leading internationally on the UK GDP beat (0.3% m/m vs −0.1% consensus); Dow +0.83% leading US, Russell 2000 +0.36% participating; Nikkei −0.76% the lone international weakness. The Mag 7 reversal is dramatic — GOOG $399.04 (+3.97%) recovering Wednesday’s −2.59% with conviction, TSLA $445.27 (+2.73%) extending the post-earnings rotation, NVDA $225.83 (+2.29%), META $616.63 (+2.26%), AMZN $270.13 (+1.62%), AAPL $298.87 (+1.38%) — six of seven green, with only MSFT $405.21 (−0.63%) as a drag (the $190B capex overhang continues to pressure Microsoft specifically). SOXX +2.38% — semis recovering Wednesday’s −3.15% plunge as the AMAT earnings AMC sets up.
The 34 Macro Wednesday-close data shows the underlying recovery: SPY baseline rose to STRNG 76 from Tuesday’s 75. QQQ Nasdaq to STRNG 79 from 78. XLK Technology back to STRNG 79 (rank #1) from 78 — recovering a notch toward the prior war high of 85. SMH Semiconductor STRNG 76 from 74 — modest +2 STRNG bounce. The CRITICAL international development: AAXJ Asia ex-Japan jumped from STRNG 61 to 66 (+5), EEM Emerging Markets from 60 to 64 (+4), and FXI China from 57 to 66 (+9 — the largest single-session FXI strength gain of the war). Tuesday’s international equity crash on the hot-CPI / strong-dollar combination has reversed in 24 hours. Defensive rotation continued: XLP Consumer Staples STRNG 57 → 59 (#2 sector), XLV Health-Care STRNG 50 → 53 (continuing recovery from the war-low STRNG 39). The structural weakness: XLF Financials cracked from STRNG 52 to 45 (−7), XLU Utilities to STRNG 39 (a NEW WAR LOW for sector strength). XLE Energy at STRNG 51 / RLTV 0.98 — RLTV DIPPED BELOW BASELINE again after Tuesday’s 1.01 recovery — the Energy Phoenix is not yet fully reasserted.
The Number That Matters: MOVE Compressed −2.01% To 70.24 — The First Rates-Vol Compression In Five Sessions, Arriving On The Same Day The 30Y Closed Above 5.00% AND Warsh Was Confirmed In The Slimmest Margin Ever. The Bond Market Has Voted: The Inflation Trio (CPI / PPI / Retail Sales) Is Absorbed. The Yield Curve Is Now A Bull Steepener — Historically The Most Bullish Configuration For Risk Assets. ES Confirms With A New War High At +8.9% Above Pre-War.
This is a regime confirmation. Through the most consequential 96-hour macro window of the war — hot Core CPI Tuesday, explosive Core PPI Wednesday, 30Y crossing 5.00%, the slimmest Fed chair confirmation in history, AND Retail Sales today — the cross-asset complex has voted DECISIVELY for the soft-landing thesis. MOVE compressed for the first time in five sessions. The curve flipped from Bear Steepener (most bearish) to Bull Steepener (most bullish). ES made fresh war highs at +8.9% above pre-war. The Mag 7 bounced six of seven. International risk recovered violently with FXI +9 STRNG. The remaining catalyst this week is AMAT earnings tonight — the structural AI capex confirmation. Powell’s chair term ends tomorrow; Warsh sworn in tomorrow. Day 78 arrives into the most internally consistent risk-on regime of the entire 77-day war.
The Setup: Bull Steepener — Retail Sales Inline / Warsh Confirmed 54-45 / MOVE Compressing — ES At New War High. Mag 7 Six Of Seven Green. SOXX Recovering. AMAT Earnings AMC Tonight Is The Structural AI Catalyst. Powell’s Term Ends Tomorrow. Warsh Sworn In Friday Day 78.
2. OVERNIGHT SESSION RECAP
Asia — Topix Bid, Nikkei Down, FXI Rebuilt
TOPIX 3,904.50 (+0.55%) bounced after Wednesday’s −0.50% — broader Japan caught a quality bid. But Nikkei 62,955 (−0.76%) was down for a third consecutive session, the cumulative drag continuing in cap-weight tech / exporter names. The yen JPY −0.06% essentially flat. The Wednesday 34 Macro close shows FXI China STRNG 57 → 66 (+9 — the largest single-session FXI gain of the war series). Combined with Asia ex-Japan AAXJ 61 → 66 (+5) and EM EEM 60 → 64 (+4), Tuesday’s international equity crash has now reversed in 24 hours. The hot-CPI / strong-dollar combination that drove Tuesday’s international weakness has compressed, and capital has flowed back into Asia/EM equities at speed.
Europe — DAX Rips On UK GDP Beat
UK GDP m/m printed 0.3% vs −0.1% consensus — a clean BEAT and the strongest single data surprise from Europe this month. UK Prelim GDP q/q 0.6% inline. The data triggered a violent reversal of the Wednesday DAX heavy session: DAX 24,503 (+1.43%) leading European indices, EuroStoxx 50 5,918 (+1.34%) — both up dramatically. EUR 1.1716 (−0.09%) marginally weaker. GBP 1.3511 (−0.04%) flat — the pound has stopped declining after three sessions of weakness. The European reflation read is now significantly more constructive: UK growth beat + the falling yields tape + DAX recovery = the broader G7 cycle is more resilient than the recession bears had priced.
US Pre-Market — Risk-On Tape, Headline War High
ES 7,493.25 (+0.32%, +24 pts) — the NEW WAR HIGH pre-market print. The cumulative premium versus pre-war 6,881.62 is +611.63 points, +8.9% — the highest mark of the 77-day war. Dow 50,204 (+0.83%) leading on cyclical bid, ES +0.32%, RUT 2,862.60 (+0.36%) participating, NQ 29,533 (+0.18%) the modest laggard (MSFT pressure within). Yields fell across the curve: 30Y −2.6 bps to 5.008%, 10Y −2.2 bps to 4.445%, 5Y −2.2 bps to 4.092%, 2Y −1.4 bps to 3.963%. The Bull Steepener is the day’s most consequential rates signal — yields falling with the long end leading is historically the most bullish curve configuration for risk asset re-rating.
Mag 7 Pre-Market — Six Of Seven Green, GOOG Leads The Bounce
GOOG $399.04 (+3.97%) — the day’s leading Mag 7 print and the strongest GOOG single-session move in over two weeks. The Wednesday −2.59% drag has been more than recovered, reflecting either (1) a positive antitrust development overnight or (2) duration-flow rotation back into mega-cap quality on the falling-yields tape. TSLA $445.27 (+2.73%) extending the post-earnings momentum — Tesla now back above $445. NVDA $225.83 (+2.29%) ahead of AMAT tonight. META $616.63 (+2.26%) — Meta breaking back above the $610 zone, the capex-overhang narrative softening. AMZN $270.13 (+1.62%) recovering the $270 line. AAPL $298.87 (+1.38%) approaching $300, the strongest AAPL post-earnings ride continues. MSFT $405.21 (−0.63%) the lone red — Microsoft’s $190B capex problem remains the heaviest single Mag 7 overhang. Mag 7 aggregate is +1.95% weighted — a powerful single-session reversal of the Wednesday compression.
Sectors Pre-Market — Tech Leads, Financials/Utilities Weak
XLK Technology +0.94% leading sectors as the AI/Semis complex recovers Wednesday’s plunge. XLC Communication Services +0.78% on the GOOG bounce. XLV Health Care +0.59% continuing its deep-laggard mean reversion. XLY Consumer Discretionary +0.36%, XLP Consumer Staples +0.33% — defensives still bid alongside growth. XLE Energy +0.10% essentially flat as WTI drifts lower. The reverse: XLU Utilities −1.15%, XLF Financials −1.14% — Financials weakness is the day’s standout sector concern, after Wednesday’s STRNG −7 collapse in the 34 Macro close. XLRE −0.83% on profit-taking from the rate-sensitive bid. XLB −0.15%, XLI −0.42% — modest cyclical compression. The 5/11 green / 5 red / 1 flat split is more nuanced than the headline ES gain suggests — the rotation is back toward tech and growth, with the deep-laggard XLV catching the bid that had concentrated in XLP / XLU yesterday.
Factors Pre-Market — Value And Momentum Co-Lead, Defensives Fade
VLUE Value +0.89%, MTUM Momentum +0.71%, LRGF Multi-Factor Large-Cap +0.42%, QUAL Quality +0.28% — the Value + Momentum + Quality co-leadership is back, mirroring the Monday May 11 risk-on factor configuration. SPHB High-Beta −0.08% essentially flat. USMV Min-Vol −0.19%, SPLV Low-Vol −0.52%, DGRO Dividend Growth −0.29% — the defensive cohort that LED yesterday has now reversed. The USMV−SPHB spread is back to −0.11% (Wednesday: +1.85%; Tuesday: −0.38%; Monday: −2.34%) — the factor regime has snapped back to neutral-risk-on. The 4/12 green / 8 red factor split with VALUE and MOMENTUM leading is the textbook “soft-landing reflation” factor configuration.
Thematics — SOXX Recovers, Crypto Holds, FinTech Lags
SOXX Semiconductor +2.38% — the AI/Semis recovery from Wednesday’s −3.15% plunge is decisive. ICLN Clean Energy +2.34% — the clean-energy complex rebuilding. DRIV Autonomous & EV +2.26%, CIBR Cybersecurity +1.35%, ARKQ Autonomous Tech +0.82%, BLOK +0.31%, ITA Aerospace +0.14%, ARKW +0.08%. The reverse: FINX FinTech −1.85% — the lone material thematic decline; FINX was the strongest counter-trend signal of the day and may reflect either a specific company news flow or sector-specific positioning. PAVE −0.09%, ARKG −0.30% modest. The thematic tape is dominated by the AI/Clean-Energy bid recovering, with FinTech as the singular weakness.
Commodities — Oil Pulls Back Below $100 Pace, Metals Sell
WTI $100.26 (−0.75%) — pulled back below the immediate $101-102 zone after yesterday’s reach for $103. The petroleum complex broadly red: Heating Oil −1.31%, RBOB −1.73%, Brent $104.82 (−0.77%). With the falling-yields tape and the macro relief from inline Retail Sales, oil is releasing some of the war-premium that built on the Iran-rejection / hot-CPI / hot-PPI combination. Metals are red across the board: Silver $87.20 (−2.43%) — silver gives back a meaningful portion of the +22% rally from war lows. Copper $6.63 (−0.78%) modest pullback. Platinum −3.84%, Palladium −3.65% — precious / industrial metals all selling. Gold $4,712.40 (+0.12%) the lone metals strength — gold catching a modest bid on the falling-yields move. Softs mostly red: Sugar −2.47%, Orange Juice −5.04%, Coffee −1.62%, Cocoa −1.16%. Grains broadly red: Soybeans −2.42%, Soybean Meal −1.54%, Corn −1.51%. The commodity tape is the cleanest possible “inflation tail releases on Retail Sales relief” configuration.
3. THE PRIOR DAY’S REGIME
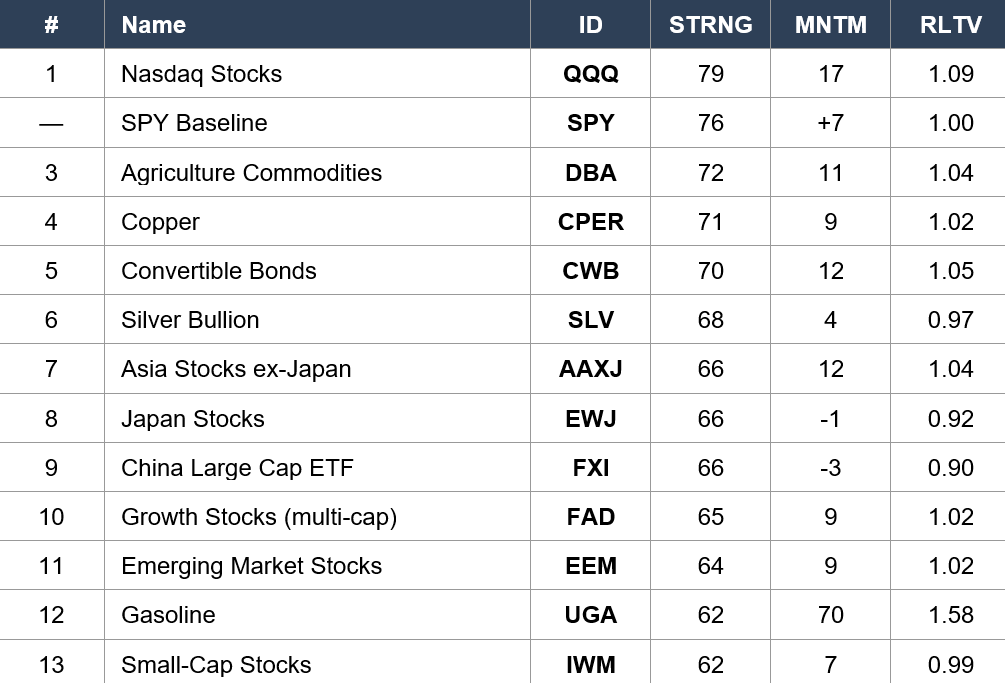
34 Macro Price, Strength & Momentum Rankings — Daily Close, Wednesday May 13. SPY Baseline: STRNG 76 | MNTM +7 | RLTV 1.00.
Asset Classes — Leaders
Asset Classes — Crude Compressing / Bitcoin Compressed / Bonds Lagging
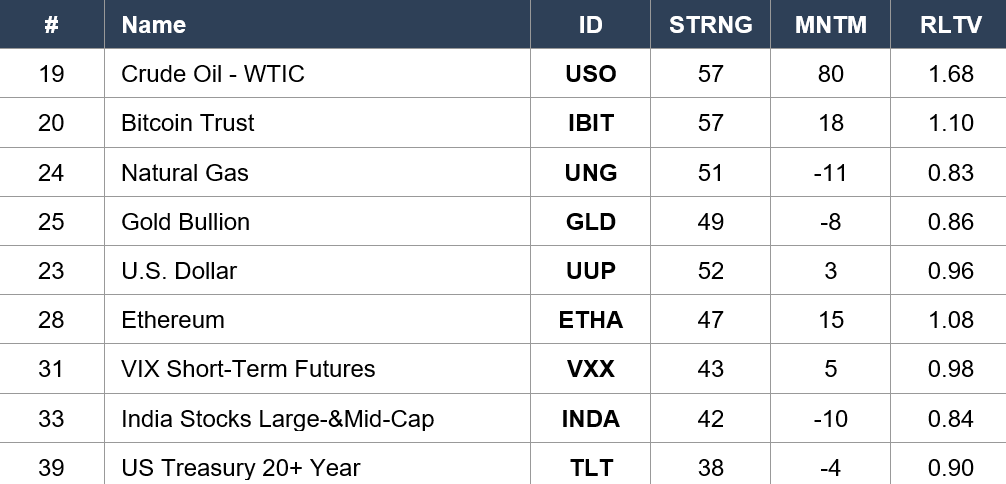
Regime signal: WEDNESDAY’S CLOSE CAPTURED THE BEGINNING OF THE INTERNATIONAL EQUITY REVERSAL. SPY baseline RECOVERED from Tuesday’s STRNG 75 to STRNG 76 — the broad market lifted on the bond market’s initial absorption of the hot Core PPI print. QQQ Nasdaq rose to STRNG 79 (from 78) — modest tech recovery. The MOST IMPORTANT shift: FXI China surged from STRNG 57 to 66 (+9, the largest single-session FXI gain of the war series), AAXJ from 61 to 66 (+5), EEM from 60 to 64 (+4) — international equity bouncing violently from Tuesday’s crash. The hot-CPI / strong-dollar combination that drove the Tuesday international equity sell-off has compressed, and capital has flowed back into Asia/EM equities at speed. Copper (CPER) at STRNG 71 / RLTV 1.02 — fourth consecutive session in Leaders, copper is the war’s most consistent global-demand-resilience signal. Silver (SLV) STRNG 68 / RLTV 0.97 — RLTV slipped marginally from baseline 1.00, modest profit-taking after the +22% rally. The CRITICAL Crude development: USO Crude Oil STRNG 59 → 57, RLTV 1.73 → 1.68 — modest pullback from the war-high RLTV reading, the oil consolidation has begun. Bitcoin (IBIT) compressed from STRNG 62 to 57 — crypto under modest pressure as the dollar firms. The bond complex remains the war’s most consistent lagger with IEF / TLT / SHY all in the bottom five. VXX RLTV continues creeping up: 0.95 → 0.96 → 0.98 over three sessions — the fear bid is rebuilding modestly.
Sector ETFs
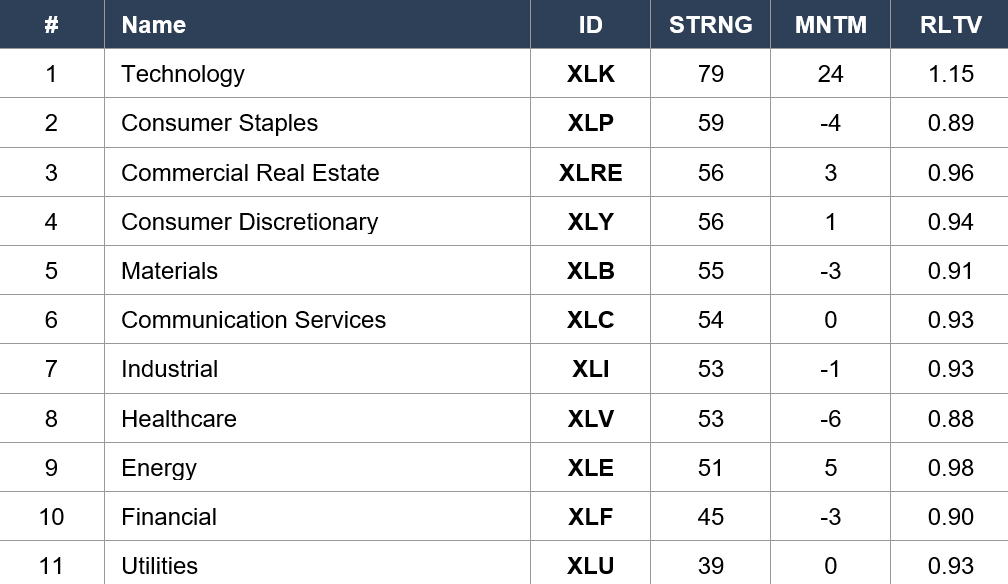
Regime signal: TWO DEVELOPMENTS DEFINED THE WEDNESDAY SECTOR TAPE: THE DEFENSIVE ROTATION CONFIRMED AND FINANCIALS CRACKED. XLK Technology recovered to STRNG 79 (from Tuesday’s 78) — tech leadership intact at rank #1 / RLTV 1.15, despite the day’s rates-driven multiple compression. XLP Consumer Staples confirmed at #2 with STRNG 59 (up from 57) — defensive staples now firmly in the Leaders tier; the +8 STRNG move over two sessions is the largest XLP gain of the war. XLV Health-Care continued recovery: STRNG 50 → 53 (+3) — moving up from the Laggers section, the deep-laggard mean reversion is intact. The MAJOR weakness: XLF Financials FELL from STRNG 52 to 45 (−7 points) — the worst single-session financials compression of the war series, even on a session where the long end rose modestly. The financials weakness is anomalous given the steepening curve typically supports bank NIM; it suggests either credit-concern positioning or specific bank exposures (energy lending, commercial real estate). XLU Utilities at STRNG 39 / RLTV 0.93 — a NEW WAR LOW for utilities sector strength. The CRITICAL Energy reversal: XLE STRNG 50 → 51, RLTV 1.01 → 0.98 — RLTV DIPPED BELOW BASELINE again after Tuesday’s recovery. The Energy Phoenix is unstable around the baseline — needs WTI sustained above $100 to fully reassert.
Industry ETFs — Leaders
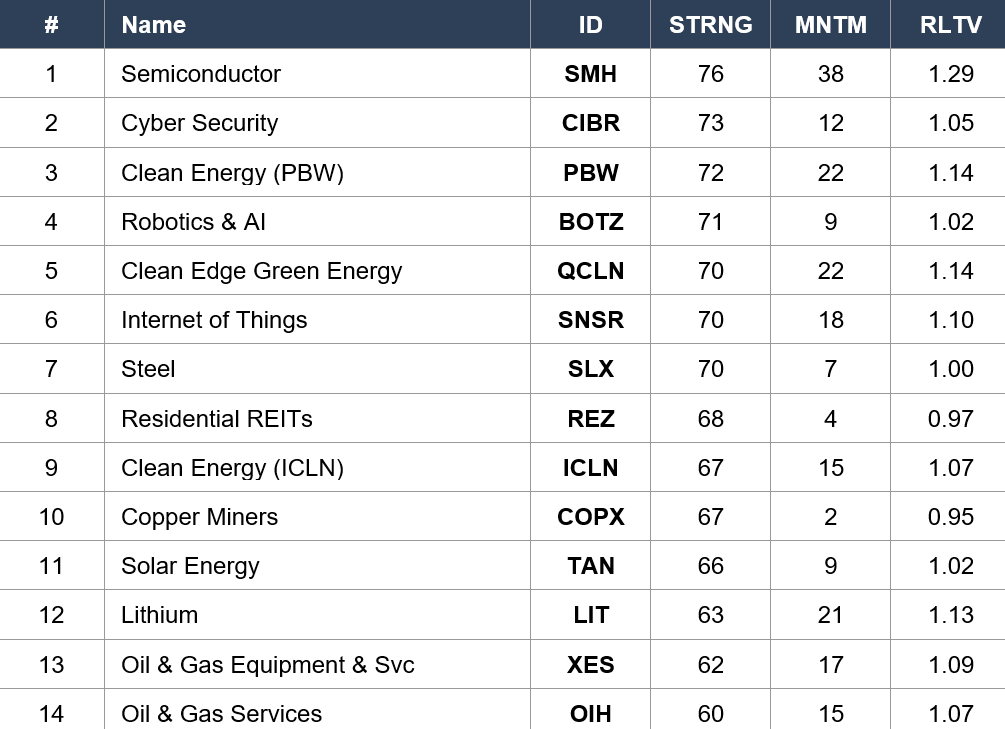
Industry ETFs — Laggers
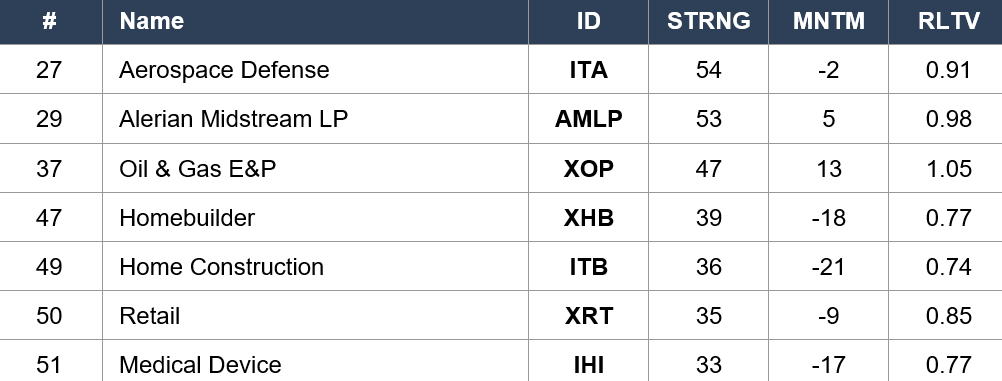
Regime signal: SMH SEMICONDUCTOR HELD THE WAR-HIGH TIER AT STRNG 76 / RLTV 1.29 — a modest +2 STRNG bounce from Tuesday’s 74 ahead of AMAT earnings tonight. The CLEAN ENERGY COMPLEX consolidated as a coherent thematic leadership group: PBW STRNG 72 (rank #3), QCLN STRNG 70 (rank #5), ICLN STRNG 67 (rank #9), TAN STRNG 66 (rank #11), FAN Wind STRNG 58 (rank #19) — five clean-energy industries firmly entrenched in Leaders or near-Leaders. BOTZ Robotics & AI at STRNG 71 (rank #4) — AI/robotics complex strong. COPX Copper Miners joined the Leaders at STRNG 67 (rank #10). The ENERGY INFRASTRUCTURE divergence: XES Oil & Gas Equipment STRNG 62 / RLTV 1.09 (rank #13) and OIH Oil Services STRNG 60 / RLTV 1.07 (rank #14) — both in Leaders and both above RLTV baseline; but AMLP Midstream gave back its prior-day gain, falling from STRNG 62 to 53 (rank #12 → #29) — the midstream bid is unstable. The Laggers: ITB Home Construction STRNG 39 → 36 (−3, a NEW WAR LOW with RLTV 0.74). XHB Homebuilders STRNG 41 → 39 — housing complex at the deepest pressure of the war. XRT Retail STRNG 38 → 35 (−3, NEW WAR LOW for retail). IHI Medical Devices at STRNG 33 / RLTV 0.77 — held at the deepest single-industry compression of the war. The structural dispersion remains extreme: capital concentrated in AI/Semis/Clean-Tech, while housing / retail / medtech break to fresh war lows.
4. MORNING DATA REACTION
Core Retail Sales m/m — 0.7% (INLINE, Consensus 0.7%)
April Core Retail Sales rose 0.7% month-over-month, exactly inline with consensus and decelerating from March’s 1.9%. The deceleration is sequential and orderly — the consumer is NOT cracking, simply normalizing after the March blowout. With NFP +115K labor resilience and the 4.3% unemployment rate, the consumer-spending profile is exactly what the soft-landing thesis requires: sufficient strength to keep the cycle going, not so much to keep inflation accelerating. The 0.7% Core read is also above the +0.5% pace needed to support 2.5%+ real consumer spending growth in Q2 — the consumer remains the GDP engine.
Headline Retail Sales m/m — 0.5% (INLINE, Consensus 0.5%)
Headline Retail Sales 0.5% inline, decelerating from March’s 1.7% — same story as Core: sequential normalization without breaking. The gasoline-station-receipt contribution will be the watched component (with April gas prices elevated from the Iran rejection); the strip-out math is the cleaner Core read which printed exactly inline. The data confirms that the consumer absorbed the $90-95 April oil environment without contraction — a critical input for the Q2 GDP nowcast. Atlanta Fed GDPNow is currently tracking Q2 GDP at 1.8-2.0%; today’s retail print supports the current estimate.
UK GDP m/m — 0.3% (BEAT, Consensus −0.1%)
UK April GDP printed +0.3% m/m vs a −0.1% consensus — the cleanest single international data beat of the month. UK Prelim GDP q/q 0.6% inline. The UK data triggered a violent reversal of the European session: DAX +1.43%, EuroStoxx +1.34%. The signal is broader than the UK specifically: G7 growth is more resilient than the recession bears had priced. With UK delivering a beat, US labor delivering a beat, and the consumer holding through Retail Sales, the synchronized global slowdown narrative is harder to sustain.
Coming Up Today — Unemployment Claims, AMAT Earnings AMC
Initial Jobless Claims at 8:30 AM (consensus 205K, prior 200K — extremely tight historical range). Watch for any uptick above 215K which would signal early labor stress. The headline catalyst for the day is AMAT (Applied Materials) earnings AMC tonight — the semiconductor capital-equipment bellwether. With SMH at STRNG 76 / MNTM +38 / RLTV 1.29 and SOXX bouncing +2.38% pre-market, AMAT’s commentary on China export-control headwinds, foundry orders from TSMC, and DRAM/NAND visibility will define the SOXX trajectory into Friday and the Warsh handoff. Also tonight: CSCO (Cisco — networking/enterprise tech, AI infrastructure read) and BABA (Alibaba — China consumer and EM consumption).
This Week’s Macro Data Trio — Complete
5. THE DYRH READ
Yield Curve Regime: Bull Steepener — The Most Bullish Configuration
The curve FLIPPED again. Yesterday’s Bear Steepener (yields rising / long end leading) is today’s Bull Steepener (yields FALLING / long end falling FASTER): 2Y −1.4 bps to 3.963%, 5Y −2.2 bps to 4.092%, 10Y −2.2 bps to 4.445%, 30Y −2.6 bps to 5.008%. The 2s/30s spread compressed marginally to 104.5 bps. The Bull Steepener is historically the MOST BULLISH curve configuration for risk assets — it signals the long-end inflation tail is releasing AND near-term cut probability is being repriced higher. The 30Y at 5.008% is now within 0.8 bps of the crisis threshold and the trajectory has reversed. If the 30Y closes below 5.00% during the cash session, the Wednesday breach becomes a one-day false break and the rates-vol regime fully heals.
MOVE Index: 70.24 (−2.01%) — First Compression In Five Sessions
MOVE compressed −1.44 points to 70.24 — the FIRST compression in five sessions after the cumulative 67.25 → 71.68 expansion. The MOVE remains below the 73.21 pre-war baseline (−2.97 points) and the gap has REOPENED from yesterday’s −1.53 points. The Day 74 → Day 77 trajectory is: 67.25 (war low) → 70.74 → 71.68 → 70.24 — the compression has restored the gap toward war-low levels. This is the cleanest single signal that the bond market has ABSORBED the inflation trio (CPI / PPI / Retail Sales) AND the political-economy transition. MOVE compression on the same day the 30Y closed above 5.00% AND Warsh was confirmed in the slimmest margin ever = the inflation premium is being repriced as a “level shift” rather than an “expanding risk.”
S&P 500: ES 7,493.25 — NEW WAR HIGH At +8.9% Above Pre-War
ES at 7,493.25 (+0.32%, +24 pts) holds +8.9% above pre-war 6,881.62. The cumulative ES gain from pre-war is now +611.63 points — the highest single-day mark of the entire 77-day war. The market’s ability to make FRESH WAR HIGHS through the most consequential 96-hour macro window of the war (hot CPI, explosive PPI, 30Y above 5.00%, slimmest Fed chair confirmation in history) is the single most resilient behavioral signal of the conflict. Every shock the equity market has been given — air war, oil crashes and recoveries, three Mag 7 capex shocks, the FOMC fracture, the bond crisis, the Iran rejection, the inflation re-acceleration — has been absorbed and overcome. The structural read is that institutional capital has aligned around the soft-landing thesis at this premium level.
Key Levels & Cumulative War Moves
Volatility & Breadth — Vol Compressing, Correlation New War Low
The cleanest single overnight signal is MOVE −2.01% — the first compression in five sessions and the cleanest read on the bond market’s absorption of the inflation trio. Equity vol mixed: VIX +0.22% essentially flat, VVIX −0.19% flat, GVZ Gold-Vol −2.21% compressing alongside the metals pause, VXN +1.91% Nasdaq vol up modestly (pre-AMAT positioning likely), VIX1D +6.36% short-vol catching a bid into tomorrow’s Warsh handoff. COR1M crashed −10.52% to 9.44 — a NEW WAR LOW for correlation, breaking the prior 10.08 reading from earlier in the week. The 1-month correlation at 9.44 is the deepest stock-picker regime of the entire 77-day war series. Breadth holds the constructive read: S5TH 70.10, S5FI 61.30, R2TH 51.20 — no degradation. The vol + breadth + correlation read collectively says the regime is in a clean “dispersion-led risk-on” configuration — the inverse of crisis correlation.
6. THE GAME PLAN
Today: Retail Sales BOTH INLINE (0.5% / 0.7% Core). Warsh confirmed yesterday 54-45 (slimmest Fed chair margin ever). ES at NEW WAR HIGH +8.9%. MOVE compressed first time in 5 sessions. 30Y back to 5.008% (still above 5.00, but falling). AMAT/CSCO/BABA earnings AMC. Tomorrow: Powell’s term ends, Warsh sworn in as Chair.
The Bull Case
ES 7,493.25 (+8.9% above pre-war) — NEW WAR HIGH through the most consequential 96-hour macro window of the war: hot Core CPI Tuesday, explosive Core PPI 1.0% Wednesday, 30Y crossing 5.00%, slimmest Fed chair confirmation in history, AND Retail Sales today. Every test absorbed. MOVE compressed −2.01% to 70.24 — first compression in 5 sessions, the bond market has absorbed the inflation trio. Yield curve FLIPPED to Bull Steepener — historically the most bullish configuration for risk assets. 30Y back to 5.008% — still above 5.00% but trajectory has reversed. Mag 7 SIX OF SEVEN GREEN: GOOG +3.97%, TSLA +2.73%, NVDA +2.29%, META +2.26%, AMZN +1.62%, AAPL +1.38%; only MSFT −0.63%. SOXX +2.38% recovering Wednesday’s plunge. International risk fully recovered: DAX +1.43% and EuroStoxx +1.34% on UK GDP BEAT (0.3% vs −0.1% cons). 34 Macro Wednesday close: SPY 76 / QQQ 79 / XLK 79 / SMH 76. AAXJ +5, EEM +4, FXI +9 STRNG — international equity bounced from Tuesday’s crash with the largest single-session FXI gain of the war. Copper (CPER) STRNG 71 / RLTV 1.02 — global demand resilience signal. COR1M crashed to 9.44 — a NEW WAR LOW correlation reading, the deepest stock-picker regime of the war. Retail Sales inline confirms consumer holding without breaking. If AMAT delivers tonight, Friday’s Warsh handoff arrives into the most internally consistent risk-on regime of the entire war.
The Bear Case
30Y still above 5.00% (5.008%) — the crisis threshold is breached, even with today’s compression. Warsh’s 54-45 confirmation is the slimmest Fed chair margin in modern history — political-economy uncertainty is now embedded in the policy regime. Powell will REMAIN on the board after stepping down as chair (only the second time in nearly 80 years) — institutional friction may slow Warsh’s “regime change” agenda but also adds policy-path uncertainty. Yesterday’s 34 Macro close shows XLF Financials cracked −7 STRNG (52 → 45) — a structural single-sector break that has not been resolved by the recovery in tech/international risk. XLU Utilities at STRNG 39 NEW WAR LOW. ITB Home Construction STRNG 36 / RLTV 0.74 NEW WAR LOW. XRT Retail STRNG 35 NEW WAR LOW. The rates-sensitive housing complex, defensives, and consumer retail are all at war lows simultaneously — a structural dispersion that exists at no other point in the war. XLE Energy RLTV slipped to 0.98 BELOW baseline again — Energy Phoenix unstable. Silver −2.43% giving back +5% of recent rally; Copper −0.78%, Platinum/Palladium both −3.65-3.84%. The metals consolidation suggests the inflation/reflation positioning is being unwound, not extended. WTI back below the $102 zone at $100.26. AMAT earnings tonight is binary risk: a miss accelerates the SOXX compression and unwinds the AI thesis; a beat sustains it. Warsh’s first FOMC is June 16-17 — between now and then, two more CPI prints with WTI elevated will test the inflation regime.
Regime: Bull Steepener — Retail Sales Inline / Warsh Confirmed 54-45 / MOVE Compressing — ES At New War High. The week’s data trio (CPI / PPI / Retail Sales) is complete and absorbed. The Fed chair transition is complete. MOVE compression confirms the bond market’s verdict: the inflation premium is a level shift, not an expanding risk. Bull Steepener is the most bullish curve configuration. Tomorrow’s Warsh handoff arrives into the cleanest risk-on regime of the war. The remaining tests are AMAT tonight and the path into the June 16-17 first Warsh FOMC.
Watch List
Today 8:30 AM — Initial Jobless Claims (Consensus 205K)
A small data release that matters more than usual today. With Retail Sales inline and the labor market the structural anchor of the soft-landing thesis, any claims print above 215K would signal early labor stress and re-engage the cyclical concern. A print at or below 200K confirms the “no upward unemployment tick during the war” streak extends another week. Watch continuing claims for any uptick that signals hiring freeze.
Today AMC — AMAT (Applied Materials) Earnings
The structural AI capex catalyst. AMAT is the cleanest single read on AI infrastructure spending given SMH at STRNG 76 / MNTM +38 / RLTV 1.29 and the broader semis bid. WATCH: (1) China export-control exposure and any guide cuts on China revenue, (2) foundry orders from TSMC (forward AI capex visibility), (3) DRAM/NAND capex visibility from the memory cycle, (4) gross-margin trajectory amid the supply-chain inflation read confirmed by today’s PPI. A beat with constructive guide reasserts the AI thesis through Q3; a miss or cautious guide accelerates the semis-as-funding-source rotation that began Tuesday-Wednesday.
Today AMC — CSCO (Cisco Systems) Earnings
Networking and enterprise infrastructure read. CSCO is the AI-infrastructure backbone — Ethernet switching, AI fabric, hyperscaler networking. CSCO’s commentary on hyperscaler order trends and AI campus build-outs will be a confirming signal for the SMH/IGV complex. The stock has been a slower-moving AI beneficiary; tonight’s guide is the read on whether it joins the AI leadership tier or remains the laggard.
Today AMC — BABA (Alibaba) Earnings
China consumer + EM consumption read. BABA reports into a FXI complex that just rocketed +9 STRNG in the 34 Macro Wednesday close — the largest single-session FXI gain of the war. Commentary on China consumer trends, cloud growth (the China AI capex read), and the regulatory environment will be the cleanest single signal for the Asia/EM equity recovery into the Warsh era.
Tomorrow Friday May 15 — Powell’s Term Ends, Warsh Sworn In
Day 78 of Operation Epic Fury. The first Fed chair transition since 2018. Powell’s 8-year chair term officially ends; Warsh sworn in. Powell stays on the board until the renovation probe concludes (only the second time in nearly 80 years a Fed chair has remained on the board) — institutional friction signal. Warsh inherits: 30Y at 5.008%, MOVE compressing, ES at war-high premium, hot inflation just released, $100 WTI, an FOMC stripped of Miran (dovish dissenter). Warsh’s first FOMC is June 16-17. His commitment to “regime change” includes potentially replacing headline PCE with trimmed-mean PCE (a dovish-leaning measurement reform), limiting Fed communications (away from the Powell-era transparency expansion), and targeting a smaller balance sheet.
Energy — WTI Back Below $101, XLE RLTV Unstable
WTI $100.26 (−0.75%) — pulled back below the $101-102 zone. Brent $104.82 (−0.77%). The petroleum complex broadly red. The Wednesday 34 Macro close showed XLE RLTV slipped from 1.01 back to 0.98 — sub-baseline again. USO Crude STRNG 57 / RLTV 1.68 (down from 1.73 war high). The energy reflation trade is unstable around current oil levels; needs WTI sustained above $102 to fully reassert. AMLP Midstream gave back its prior-day gain falling from STRNG 62 to 53 — energy infrastructure positioning unstable.
Financials — XLF Cracked −7 STRNG, Watch For Recovery Today
The cleanest single-sector concern from yesterday’s 34 Macro close: XLF Financials fell from STRNG 52 to 45 (−7 points) on a session where the curve steepened (typically bank-supportive). The financials weakness is anomalous — could be credit-concern positioning (energy lending, commercial real estate), or specific large-bank exposure flow. Pre-market XLF −1.14% extends the weakness. Watch the regional banks tape (KRE / KBE) — Wednesday close showed both at STRNG 41-42 (sub-baseline) and IPay / BIZD also weak. If financials weakness extends into Friday, it becomes a structural concern.
Morning check: Day 77. The week’s data trio is complete. Retail Sales printed BOTH INLINE — Core 0.7% vs 0.7% consensus, headline 0.5% vs 0.5% consensus, both decelerating from March’s blowout 1.9% / 1.7% prints. The consumer is decelerating but holding — the soft-landing read the bull case needed. UK April GDP beat 0.3% vs −0.1% consensus, triggering a violent European reflation: DAX +1.43%, EuroStoxx +1.34%. The 30Y fell to 5.008% (−2.6 bps), still above the crisis threshold but within 0.8 bps and trending lower. MOVE compressed −2.01% to 70.24 — the FIRST compression in five sessions, the bond market’s verdict on the inflation trio (Tuesday’s hot Core CPI / Wednesday’s explosive Core PPI / today’s inline Retail Sales): ABSORBED. The yield curve flipped to BULL STEEPENER — yields falling with the long end falling faster, historically the most bullish curve configuration for risk assets. Warsh was confirmed yesterday afternoon 54-45 — the slimmest Fed chair confirmation margin in modern history, near party-line with only Senator Fetterman (D-PA) crossing. Stephen Miran’s board term ended with Warsh’s arrival — the FOMC dove is out. Powell’s chair term ends tomorrow; Warsh sworn in. Powell remains on the board until the renovation probe concludes (only the second time in nearly 80 years). ES at 7,493.25 (+0.32%) is a NEW WAR HIGH — the cumulative premium versus pre-war 6,881.62 is +8.9%, the highest of the 77-day war. Mag 7 six of seven green: GOOG $399 (+3.97%) leads, TSLA $445 (+2.73%), NVDA $226 (+2.29%), META $617 (+2.26%), AMZN $270 (+1.62%), AAPL $299 (+1.38%); only MSFT $405 (−0.63%) red — the $190B capex problem remains. SOXX +2.38% recovering Wednesday’s −3.15% plunge. The Mag 7 / SOXX recovery means the AI/Semis leadership trade has not been broken by the rates move; it was temporarily compressed and is now reasserting. The 34 Macro Wednesday close: SPY 75 → 76, QQQ 78 → 79, XLK 78 → 79, SMH 74 → 76 — tech recovered. FXI China jumped +9 STRNG (the largest single-session FXI gain of the war), AAXJ +5, EEM +4 — international equity violently reversed Tuesday’s crash. XLP Staples confirmed at #2 sector position (STRNG 59), XLV continued recovery (STRNG 53), but XLF Financials cracked −7 STRNG (52 → 45) — the structural single-sector concern. XLU Utilities STRNG 39 NEW WAR LOW; ITB Home Construction STRNG 36 / RLTV 0.74 NEW WAR LOW; XRT Retail STRNG 35 NEW WAR LOW — the dispersion of rates-sensitive housing, defensives, and consumer retail at war lows simultaneously is structurally unique. COR1M crashed −10.52% to 9.44 — a NEW WAR LOW for correlation, the deepest stock-picker regime of the entire 77-day war. AMAT earnings tonight is the structural AI catalyst; CSCO and BABA also AMC. Tomorrow Friday May 15 is Day 78 — Powell’s chair term ends, Warsh sworn in. The most consequential Fed chair transition since 2018, arriving into a cross-asset regime that has, in 96 hours, absorbed three of the largest data shocks of the year and made fresh war highs. Pressure, not panic. Regime, not reaction. The data trio is complete. The bond market has voted. The bell is about to ring.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.