

1. THE QUICK SCAN
Overnight Tape Summary: THE LABOR MARKET ANSWERED. NFP +115K VS 65K CONSENSUS — NEARLY DOUBLE EXPECTATIONS. AVERAGE HOURLY EARNINGS 0.2% MISS — WAGE PRESSURE NOT ACCELERATING. UNEMPLOYMENT 4.3% INLINE. THE GOLDILOCKS LABOR PRINT — STRONG HIRING WITHOUT WAGE ACCELERATION. ES 7,407.00 (+0.60%) — A NEW WAR HIGH PREMIUM AT +7.6% ABOVE PRE-WAR. WTI $94.80 HOLDING AFTER THE FIVE-SESSION CRASH. MOVE 72.24 (+2.27%) STILL SUB-BASELINE. DXY 97.76 SUB-100. FIVE OF SEVEN MAG 7 GREEN — TSLA +3.28% LEADING. SILVER +2.13%, COPPER +2.03% — RISK-ON METALS BIDS. BULL FLATTENER. WARSH TAKES THE CHAIR IN SEVEN DAYS.
Three readings define the morning. First, the labor data: nonfarm payrolls printed +115K against a 65K consensus — a beat of 50K, nearly double the expectation. The prior month was +178K (March, the strongest print since December 2024). Average hourly earnings rose 0.2% month-over-month, missing the 0.3% consensus and matching the prior month — wage growth is decelerating, not accelerating, even as oil sits above $90 and the war enters its tenth week. The unemployment rate held at 4.3%, in line. This is the cleanest possible “labor resilience without wage pressure” combination — exactly what the Fed needs to maintain its data-dependent stance, and exactly what the equity market needs to extend its premium.
Second, the cross-asset response. ES vaulted to 7,407.00 (+0.60%) immediately on the print — a new war high above yesterday’s 7,401.75. The S&P now sits +7.6% above the pre-war 6,881.62 baseline, the highest premium of the entire 71-day war. NQ +0.94% leading, RUT +0.78% confirming small-cap rate-sensitivity, Dow +0.42%. International risk: Nikkei +1.32%, AAXJ implied bid. Yields fell across the curve into the print: 2Y −2.2 bps to 3.889%, 5Y −2.4 bps to 4.013%, 10Y −1.8 bps to 4.366%, 30Y −0.4 bps to 4.959%. The bond market’s reaction is telling — strong jobs print did NOT push yields higher, because the wage miss neutralized the inflation read. DXY −0.40% to 97.76, sub-100 for the second consecutive session.
Third, the commodity tape. WTI $94.80 (−0.01%) is HOLDING — the five-session $15-18 crash from the $108 peak has paused, but the level remains $13+ off the highs. This is stabilization, not reversal. Brent at $100.08 hugging the century mark. Gold $4,734.90 (+0.51%) extending its three-session recovery. Silver $81.89 (+2.13%) — extending the rally, the metals bid is genuine and structural. Copper $6.30 (+2.03%) — copper at risk-on highs confirms the global-demand resilience read. The cross-commodity tape supports the labor-resilience thesis: rising base metals + holding oil + rising precious metals = a soft-landing-with-inflation-tail backdrop, not a recession or crisis configuration.
The Mag 7 reaction is constructive but not euphoric. TSLA +3.28% leading on capex/AI rotation. NVDA +1.77% extending yesterday’s +5.77% explosion. MSFT +1.65% — software regaining bid. META +0.64%. GOOG +0.04% flat. AAPL −0.02% flat. AMZN −1.39% the lone material drag (post-earnings cleanup continuing). Five of seven green confirms breadth. The pre-market sector tape on the DYRH snapshot reads mostly red, but that data appears to be carrying Thursday’s late-session reading rather than reflecting the post-NFP futures move; the underlying ES futures lift is the cleaner read. Note the SOXX print at −2.86% — the semis snapshot is stale; live NVDA at +1.77% argues semis trade green into the open.
The Number That Matters: NFP +115K With AHE +0.2% — The Goldilocks Labor Print. Strong Hiring (78% Above Consensus) Without Wage Acceleration (Below Consensus). The Fed’s “Remove Easing Bias” Caution Is Validated AND The Labor Resilience Thesis Is Confirmed. The Bond Market’s Sub-Baseline MOVE And Front-End Bull Flattener Confirm The Read.
This is the print that defines the war’s endgame. For seventy-one days the question has been: can the labor market absorb $90-105 oil, a hawkish-leaning FOMC, and a Mideast war that is now in “frozen conflict” mode? Today the answer arrived. April hiring was nearly 2x consensus. Wages decelerated. Unemployment held. The labor market is not just intact — it is RESILIENT in a way the recession-hedgers, the stagflation-callers, and the bond-bears did not price. The market’s response — a new war-high ES print, sub-baseline MOVE, sub-100 DXY, all the right risk metals — confirms institutional reading aligns with the data. The Warsh transition arrives in seven days into a labor market that is delivering, an oil market that has stabilized, and a rates complex that has resolved its FOMC-driven crisis.
The Setup: Bull Flattener — Risk-On — Goldilocks NFP Validates Labor Resilience. ES At New War High. Yields Falling. Dollar Weakening. Metals Rallying. The War’s Endgame Regime Is Confirmed. Watch Michigan At 10:00 AM, Trump At Noon, Then The Weekend And A Week Of CPI/PPI/Retail Sales Into The Warsh Handoff.
2. OVERNIGHT SESSION RECAP
Asia — Risk-On With Yen Bid
Nikkei 63,075 (+1.32%) led Asia higher, the strongest single-session move in over a week. TOPIX +0.35% confirming. Asia ex-Japan (AAXJ) implied higher on the 34 Macro tape (yesterday’s close STRNG 71 / RLTV 1.08 — Leaders). The yen at +0.09% is anomalous against the broader risk-on read — JPY strength alongside equity strength suggests carry-trade unwinds rather than a pure risk-off bid; this is consistent with the dollar weakness theme (DXY −0.40%) rather than fear-driven yen demand. China FXI: yesterday’s STRNG 56 / RLTV 0.90 keeps the China complex in Middle but with the weakest relative read among major Asia markets.
Europe — Heavy Despite Risk-On Tone
Europe is the day’s lone divergence. DAX 24,507 (−0.97%) and EuroStoxx 50 5,916 (−0.54%) both red, against a US/Asia risk-on backdrop. The EUR at 1.1797 (+0.23%) is bid against the weakening dollar, which is partially weighing on European equities (FX-translation drag for export-heavy DAX names). The defense-aerospace complex (ITA −0.41% pre-market) appears to be where the European weakness concentrates — defense names led during the war’s acute phase and are now unwinding as the geopolitical regime normalizes. This is a positive sign at the macro level (de-escalation premium fading) even as it pressures European indices.
US Pre-Market — NFP-Driven Lift Across The Board
The 8:30 AM data dump produced the cleanest single-session response of the war. ES 7,407.00 (+0.60%, +44 pts), NQ 28,952 (+0.94%, +269 pts), RUT 2,871 (+0.78%, +22 pts), Dow 49,907 (+0.42%, +207 pts). Ordered by gain: NQ > RUT > ES > Dow — growth-led with small-cap participation, the textbook “rate-cut-sensitivity rewarded” reaction to a Goldilocks labor print. Yields dropped immediately on the AHE miss: 10Y to 4.366%, 30Y to 4.959%. WTI flat at $94.80. DXY −0.40% — the dollar is the cleanest single asset in the morning trade.
Mag 7 Pre-Market — 5 Green / 2 Red
TSLA $411.79 (+3.28%) leading — the capex-discount narrative continues to fade as Tesla’s rebound from the post-earnings $25B capex shock matures. NVDA $211.50 (+1.77%) extending Thursday’s +5.77% explosion — the AI-demand thesis is reasserting against the customer-spending-overhang from MSFT/META capex announcements. MSFT $420.77 (+1.65%) reclaiming altitude. META $616.81 (+0.64%) modest bid. GOOG $395.30 (+0.04%) effectively flat. AAPL $287.44 (−0.02%) flat. AMZN $271.17 (−1.39%) the lone material drag — post-earnings continuation. Aggregate Mag 7 weighting is solidly green, with the leadership concentrated in TSLA, NVDA, and MSFT — a healthier composition than NVDA-only leadership.
Sector Snapshot — DYRH Pre-Market Reading
The DYRH pre-market sector breakdown shows 2/11 green: XLC +0.03%, XLY +0.01%. This snapshot appears to lag the post-NFP futures move (the DYRH timestamp is 8:50 AM ET, twenty minutes after NFP printed; thinly-traded sector ETFs in pre-market do not always reflect headline futures moves immediately). The implied direction from the futures lift is broader green at the open. Watch carefully for XLE behavior — yesterday’s 34 Macro close put XLE in the LAGGERS group at RLTV 0.99 for the first time in the war, after eleven consecutive sessions as the highest-RLTV sector. Today’s XLE pre-market −1.84% suggests the energy-relative-strength regime that defined the war’s first sixty days is ending.
Factor Tape — Defensive Premium In The Snapshot
Pre-market factor tape (1/12 green): USMV +0.31%, with all other factors red, headlined by MTUM −1.76%, SPHB −1.47%, VLUE −1.44%. USMV−SPHB spread positive at +1.78% (defensive premium). However — same caveat as sectors: this snapshot is likely Thursday-close-carry rather than live post-NFP factor performance. The futures lift across ES/NQ/RUT and the small-cap outperformance argue the live factor tape into the open will rotate toward SPHB (high beta) and MTUM (momentum) rather than confirm the defensive read.
Energy & Metals — Holding Range, Metals Bid
WTI $94.80 (−0.01%) is the day’s most important commodity print. After a five-session crash from $108 to $90.54 (peak to Wednesday low of −13.4%), oil has stabilized in the $94 zone for two sessions. This is consolidation, not reversal — the structural premium remains $27.78 above pre-war ($67.02), or +41.5%. Brent $100.08 hugging the century. Heating Oil +0.72%, Natural Gas +0.61% — the petroleum complex finding a floor. Precious metals: Gold $4,734.90 (+0.51%) third consecutive up day. Silver $81.89 (+2.13%) — the metals bid is real. Copper $6.30 (+2.03%) — at year-to-date highs, confirming global-demand strength rather than recession-pricing. Palladium −1.12% the lone metals weak spot.
3. THE PRIOR DAY’S REGIME
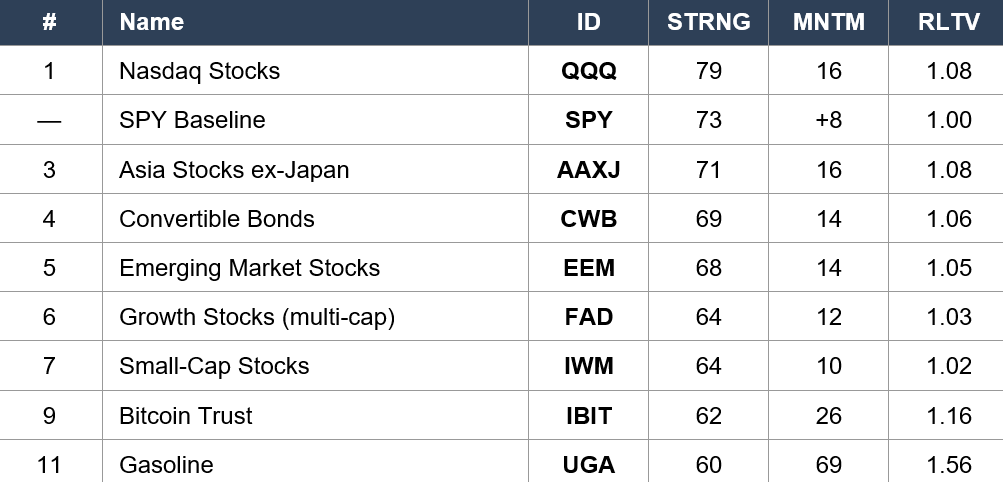
34 Macro Price, Strength & Momentum Rankings — Daily Close, Thursday May 7. SPY Baseline: STRNG 73 | MNTM +8 | RLTV 1.00.
Asset Classes — Leaders
Asset Classes — Oil Stabilizing / Bonds Lagging / Vol Tail
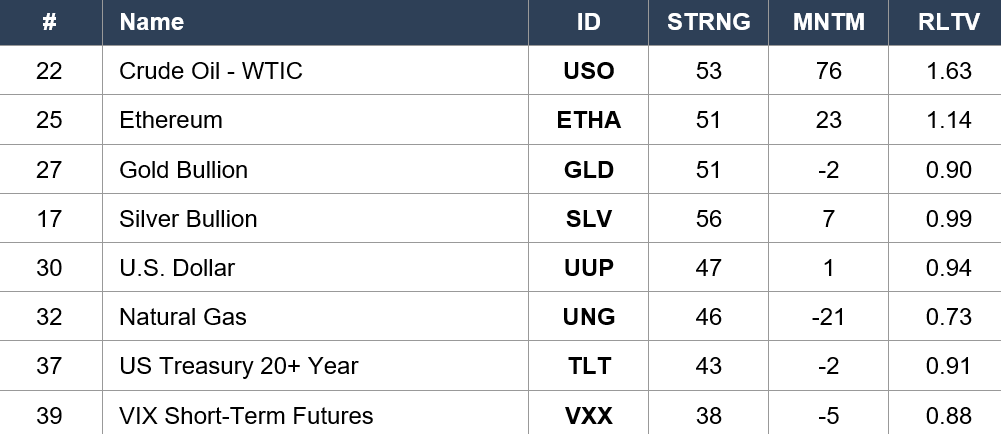
Regime signal: THE EQUITY COMPLEX RECONFIRMED, THE OIL COMPLEX IS MIDDLE, AND THE BOND COMPLEX REMAINS DEEPLY LAGGING. The SPY baseline edged from STRNG 75 (Wednesday close) to STRNG 73 — a slight one-day compression but momentum picked up (+7 → +8). QQQ remains #1 at STRNG 79 / RLTV 1.08, slightly off Wednesday’s war-high 80 — modest cooling, not reversal. Asia (AAXJ STRNG 71) and Convertibles (CWB STRNG 69) hold the second tier. Bitcoin (IBIT) stays Leader-class at STRNG 62 / RLTV 1.16 — crypto is firmly above the SPY baseline and the post-ceasefire BTC rally remains intact. The oil complex is Middle: USO STRNG 53 / RLTV 1.63 (extreme RLTV but middle STRNG — the oil pullback has compressed STRNG without yet breaking RLTV); UGA STRNG 60 / MNTM 69 / RLTV 1.56 (gasoline retains extreme momentum but is normalizing). Silver (SLV) jumped to STRNG 56 / RLTV 0.99 — the war-low RLTV 0.60 is now a memory; metals have rebuilt their strength. Gold (GLD) RLTV 0.90 — improving from war-low 0.82 but still in the LAGGERS section. The bond complex is the war’s most consistent lagging asset class: TLT STRNG 43, IEF STRNG 43, SHY STRNG 41 — all in the bottom five. VXX at STRNG 38 / RLTV 0.88 — fear is structurally extinguished from the data.
Sector ETFs
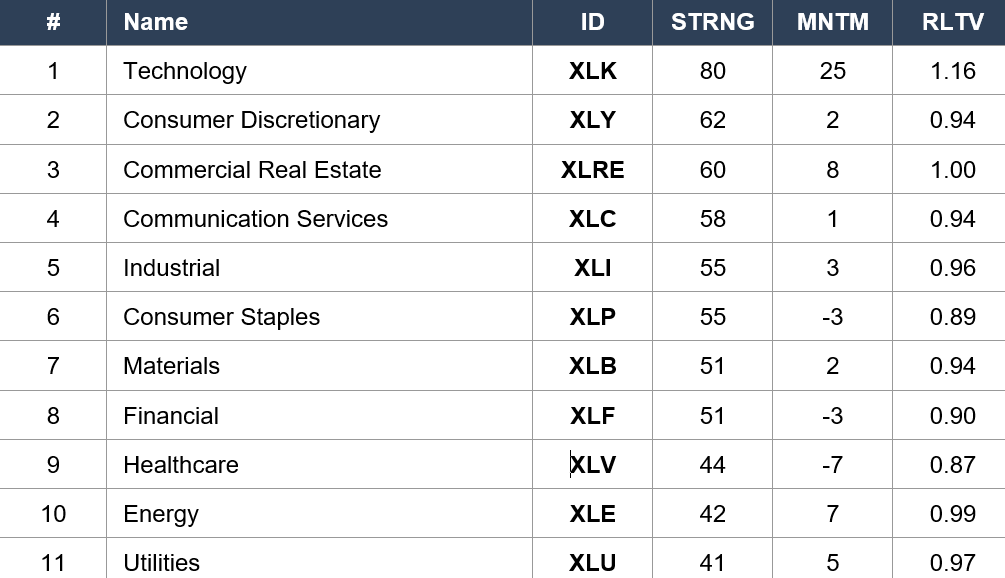
Regime signal: THE WAR’S MOST IMPORTANT SECTOR ROTATION HAS COMPLETED. After eleven consecutive sessions as the highest-RLTV sector — through the air war, the blockade, the ceasefire collapse, the Hormuz re-closure, and the FOMC fracture — XLE Energy has FALLEN OUT OF THE TOP TIER. XLE now sits at #10, STRNG 42 / RLTV 0.99 (below 1.00 for the FIRST TIME in the war series). The Energy-Phoenix relative-strength trade that was the war’s most reliable cross-asset signal is OVER. XLK Tech remains #1 at STRNG 80 / RLTV 1.16 — only mildly compressed from yesterday’s STRNG 81 / RLTV 1.15, this is consolidation at all-time leadership levels. XLY Consumer Discretionary jumped to #2 (STRNG 62) — discretionary leadership in a risk-on regime is a classic late-cycle / soft-landing setup. XLRE Real Estate at #3 (STRNG 60 / RLTV 1.00 exactly) — REITs benefiting from front-end yields falling. XLU Utilities is now the LAGGEST sector at STRNG 41 / RLTV 0.97 — the defensive-rotation trade has fully unwound. XLV Health-Care STRNG 44 — defensive sectors compressed across the board. XLF Financials STRNG 51 / RLTV 0.90 — financials still underperforming despite the curve steepening from prior sessions. The sector tape is the cleanest possible “soft-landing risk-on” configuration: tech leading, discretionary participating, defensives lagging, energy normalizing.
Industry ETFs — Leaders
Industry ETFs — Laggers
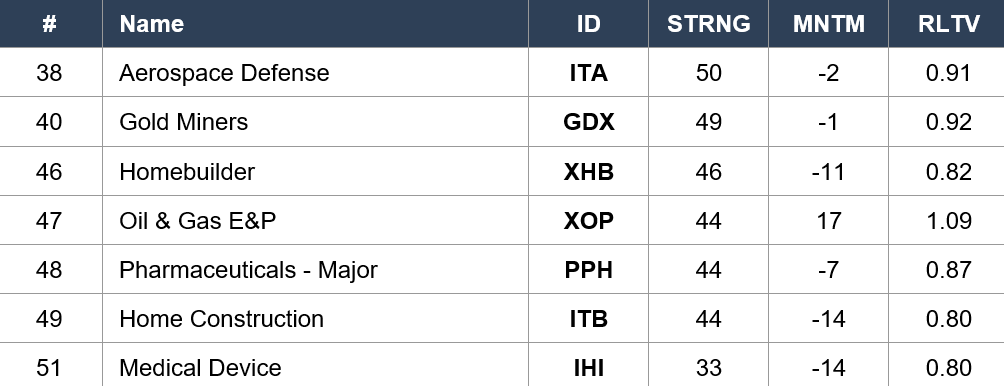
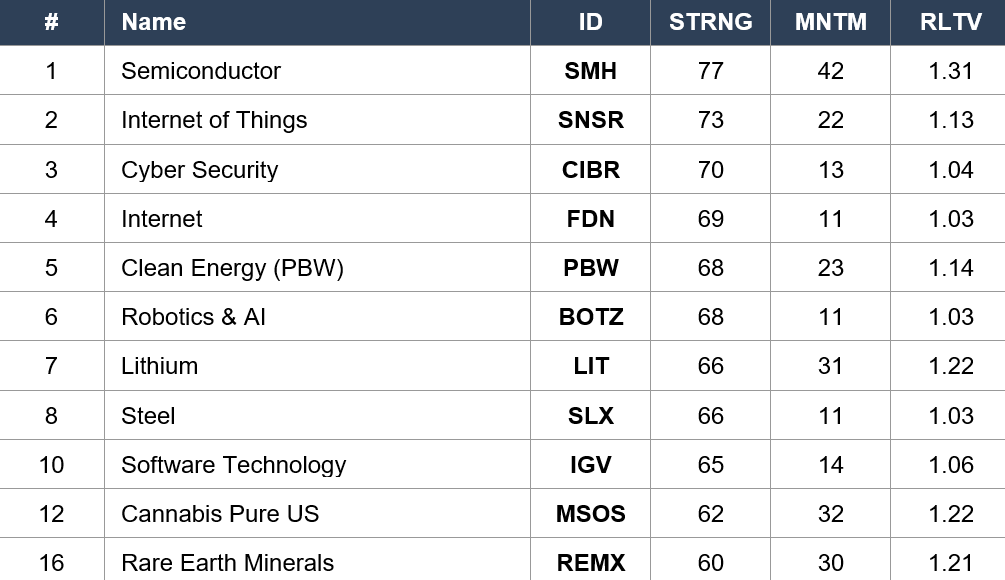
Regime signal: THE INDUSTRY DATA CONFIRMS THE WAR’S CLEAREST STRUCTURAL THEME: AI/SEMIS DOMINANCE WITH SPECULATIVE BREADTH. SMH Semiconductor at STRNG 77 / MNTM +42 / RLTV 1.31 — modestly compressed from yesterday’s war-high 83 / 44 / 1.35 but still the dominant industry by a wide margin. The Top 10 reads as a textbook AI/growth complex: SMH, SNSR (IoT), CIBR (Cyber), FDN (Internet), PBW (Clean Energy), BOTZ (Robotics & AI), LIT (Lithium), SLX (Steel), QCLN (Clean Edge), IGV (Software). Notable speculative additions in the Leaders: Cannabis (MSOS RLTV 1.22), Rare Earth Minerals (REMX RLTV 1.21) — the war’s risk-on tape extends well beyond mega-cap tech into deep speculative names. The Laggers section identifies the war’s losers: Medical Devices (IHI STRNG 33 / RLTV 0.80) at the war-low for the entire industry universe; Home Construction (ITB) and Homebuilders (XHB) deeply lagging on the rates-volatility persistence; Pharma Major (PPH) underperforming; Defense (ITA) rank 38 confirming the de-escalation discount is being applied to defense names; Oil & Gas E&P (XOP) at #47 with MNTM +17 — the upstream complex is still lagging despite the WTI premium. The capital is concentrated in tech, growth, and risk-on speculation; rates-sensitive housing, defensive pharma, and traditional value cohorts are deeply lagging.
4. MORNING DATA REACTION
Non-Farm Payrolls — +115K (BEAT, Consensus 65K)
April nonfarm payrolls printed +115K against a 65K consensus and a 178K prior — a beat of 50K, or 77% above expectations. The payroll add is below the prior month but materially above the bear scenario that recession-callers had positioned for. Cumulative payroll growth across March-April is +293K, suggesting a labor market in measured cooling rather than collapse. The breakdown will be dissected through the morning, but the headline signal is unambiguous: the war and oil shock are NOT triggering the labor capitulation that bond bulls and recession traders have priced. With the unemployment rate steady at 4.3% and wage growth decelerating, the Fed has the cleanest possible “data-dependent” justification to maintain the current stance and let Warsh inherit a non-crisis backdrop on May 15.
Average Hourly Earnings — 0.2% MoM (MISS, Consensus 0.3%)
Wages rose 0.2% month-over-month, a 0.1% miss versus consensus and identical to the prior month’s 0.2%. The wage data is the silent star of the print. Even with WTI at $90+ for ten weeks, ISM Manufacturing Prices Paid at 84.6 (the highest since 2022), gasoline retail spikes, and a war that is now in “frozen conflict” mode — wages did NOT accelerate. This is the most important Fed-relevant detail in the report. A wage miss alongside a payroll beat is the textbook “non-inflationary growth” combination — exactly what the FOMC dissenters (Hammack, Kashkari, Logan) wanted to see before removing the easing bias, and exactly what gives Powell room to hold steady through the May 14 transition. Year-over-year wage growth math will tighten further, but the M/M slowdown is structural, not seasonal.
Unemployment Rate — 4.3% (INLINE, Consensus 4.3%)
The unemployment rate held at 4.3%, exactly in line. The streak of “no upward tick during the war” extends another month — through the entire 71-day Operation Epic Fury, the unemployment rate has not risen above 4.3%. Labor force participation, U-6 underemployment, and household survey detail will be parsed through the day, but the headline tells a clean story: hiring slowing without firing accelerating. This is what a soft landing looks like in real time.
Canada — Employment Change −17.7K (MISS), U-Rate 6.9% (MISS)
North of the border, the Canadian labor data went the opposite direction. Employment fell 17.7K against a 12.9K consensus increase, and the unemployment rate jumped 0.2 points to 6.9% (consensus 6.7%). The CAD weakened to 0.7321 (−0.33%) on the print. The Canadian data adds incremental support to the BoC easing path and reinforces the global theme: the US labor market is the strongest in the G7 by a meaningful margin, supporting the dollar’s structural floor (even with DXY now sub-100 from war-peak levels).
Coming Up Today
10:00 AM ET — Prelim University of Michigan Consumer Sentiment (consensus 49.7, prior 47.6 — the war-low all-time print). A bounce off the all-time low is widely expected; consensus 49.7 would still be the second-lowest print in the survey’s history. Watch the inflation expectations subseries (prior 4.8% one-year). 12:00 PM ET — President Trump speaks (no specified topic; geopolitical or tariff commentary possible). The remainder of the session is data-light heading into a heavy week ahead: CPI Tuesday, PPI Wednesday, Retail Sales Thursday, and the Warsh chair transition Friday May 15.
5. THE DYRH READ
Yield Curve Regime: Bull Flattener
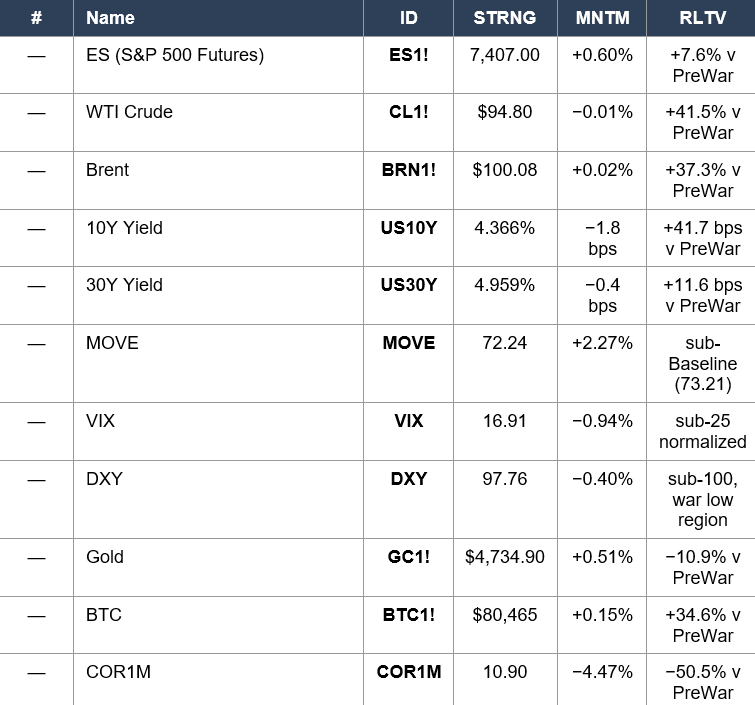
The curve is in a clean BULL FLATTENER configuration, with yields falling at every tenor and the front end falling faster than the long end. 2Y −2.2 bps to 3.889%, 5Y −2.4 bps to 4.013%, 10Y −1.8 bps to 4.366%, 30Y −0.4 bps to 4.959%. The 2s/30s spread is 107.0 bps — wide but stable. The bull flattener is the textbook “rate cuts coming, growth slowing modestly, no recession” curve. The 30Y at 4.959% is now 4.1 bps below the 5.00% crisis threshold — comfortably below after spending five sessions in the danger zone earlier in the week. Cumulatively from pre-war: 10Y +41.7 bps (3.949% → 4.366%), 30Y +11.6 bps (4.843% → 4.959%). The long end is the cleanest long-duration read of the war.
MOVE Index: 72.24 (+2.27%) — Sub-Baseline
MOVE expanded 1.60 points to 72.24 — a +2.27% move that is the day’s only meaningful volatility expansion. CRITICALLY, MOVE remains BELOW the 73.21 pre-war baseline despite the expansion. From the war high of 115.02 (Day 21), MOVE has declined 42.78 points — the bond crisis is structurally over. The MOVE’s recent trajectory: 77.86 (Monday FOMC peak) → 76.78 → 70.63 (Thursday low) → 72.24 (Friday). The bounce off Thursday’s sub-baseline low reflects normal positioning ahead of NFP, not regime change. The reading remains in the “normalized rates vol” zone that the war’s endgame regime requires. As long as MOVE sits below 75, equity multiples have room to expand.
S&P 500: ES 7,407.00 — New War-High Premium At +7.6%
ES at 7,407.00 is +0.60% versus prior close and +7.6% above the pre-war 6,881.62 baseline. This is the highest premium of the entire 71-day war. The cumulative gain of 525.38 ES points has been earned through: an air war, a 17.5%-in-one-session oil crash, a ceasefire announcement, a ceasefire collapse, the Hormuz blockade and re-closure, the Touska seizure, an indefinite-extension diplomatic frame, the most hawkish FOMC in years, the 30Y crossing 5.00%, MOVE above baseline for four sessions, $190B-$145B-$125B Mag 7 capex shocks, GDP Q1 2.0% miss, and the labor market’s test today. Through every shock the equity market has absorbed and recovered. Today’s NFP beat extends the war-high run and confirms the “endgame regime” thesis.
Key Levels & Cumulative War Moves
Volatility & Breadth — Constructive Across Both
VIX 16.91 (−0.94%) sits well below the 25 crisis threshold. VIX1D 12.38 (+6.17%) is the only short-vol expansion — typical pre-NFP positioning that decays through the day. VVIX 93.61 (−0.10%) flat. VXN 23.15 (−1.82%) Nasdaq-vol compressing alongside QQQ’s relative strength. GVZ Gold-Vol 27.03 (+2.62%) — gold-vol expanding alongside gold price is unusual and worth tracking; it suggests the metals bid is not yet “priced in” by options markets. Breadth is structurally constructive: S5TH (S&P 500 above 200D MA) at 70.10 (+2.19%) — long-term trend intact for majority of names; S5FI (above 50D) at 61.30 — intermediate trend healthy; R2TH (Russell above 200D) at 51.20 — small-caps just above neutral on long-term trend, the structural improvement is visible. COR1M at 10.90 (−4.47%) — correlation has crashed to extreme lows, confirming a stock-picker’s tape.
6. THE GAME PLAN
Today: NFP beat (released 8:30 AM, +115K vs 65K). AHE miss (0.2% vs 0.3%). U-rate inline (4.3%). Coming: Michigan Sentiment 10:00 AM (49.7 cons / 47.6 prior all-time low). Trump speaks 12:00 PM. Heavy week ahead: CPI Tue, PPI Wed, Retail Sales Thu. WARSH TAKES THE CHAIR FRIDAY MAY 15 — 7 DAYS AWAY.
The Bull Case
NFP +115K is 77% above consensus — the labor market is RESILIENT, not just stable. AHE 0.2% miss confirms wages are decelerating despite the oil premium. U-rate held 4.3% — no labor cracking. ES at 7,407 = new war-high premium of +7.6% above pre-war. Yields falling across the curve into the print (a strong-payrolls-with-falling-yields combination is a textbook soft-landing signal — wages drove the read, not headline jobs). MOVE 72.24 still sub-baseline. DXY 97.76 sub-100 with the dollar at war-low region. Five of seven Mag 7 green with TSLA +3.28%, NVDA +1.77%, MSFT +1.65%. Silver +2.13%, Copper +2.03% — risk-on metals confirmation. 34 Macro: XLK STRNG 80 / RLTV 1.16 (war-high tier holding), SMH STRNG 77 / RLTV 1.31 (semis dominant), QQQ STRNG 79 / RLTV 1.08 (Nasdaq leadership), Bitcoin RLTV 1.16 (crypto Leader). VXX RLTV 0.88 (fear extinguished further). Speculative breadth: Cannabis MSOS RLTV 1.22, Rare Earth REMX RLTV 1.21, Lithium LIT RLTV 1.22 — risk-on extends well beyond mega-cap tech. If Michigan prints anywhere near consensus 49.7, the entire macro narrative is validated and the rally extends into the Warsh handoff.
The Bear Case
NFP +115K is still WELL below the 178K prior — labor is decelerating, just less violently than feared. The 2/11 sector tape and 1/12 factor tape pre-market may be partly stale, but they reflect Thursday’s late-session distribution where defensive premium re-emerged. MOVE expanded +2.27% — rates vol is not done; another oil reversal or Hormuz incident reignites the rates stress in 24 hours. WTI at $94.80 is still +41.5% from pre-war — the war premium is enormous and any Mideast escalation snaps the oil pullback. XLE fell to RLTV 0.99 — the war’s most consistent leadership trade is now over, and energy investors are unwinding positions that need somewhere to go. The DAX/EuroStoxx red despite US/Asia risk-on hints at international pressure that could spread. Gold and silver rallying alongside equities is anomalous — historically a haven-bid that precedes risk-off shifts. Michigan at 47.6 was an ALL-TIME LOW — even consensus 49.7 leaves consumer sentiment in unprecedented territory; a print BELOW 47.6 would re-engage stagflation fears. Trump at 12:00 PM is an unscheduled-content risk. Ahead: CPI Tuesday is the war’s first post-NFP inflation read with $94 oil in the data, and Warsh inherits a mandate the market has not yet priced.
Regime: Bull Flattener — Risk-On — Goldilocks NFP Validates Labor Resilience. The war’s endgame regime is confirmed by the labor data. Hiring strong, wages decelerating, unemployment held. ES at new war-high premium. Yields falling. Dollar weakening. Metals rallying. Tech leading, energy normalizing, defensives lagging. The structural soft-landing configuration is in place. The remaining tests: Michigan today (10:00 AM), CPI Tuesday (the first post-$94-oil inflation read), and the Warsh handoff Friday May 15. Seven days to a new Fed chair, taking over a market at a war-high premium with the labor market and rates complex both validated.
Watch List
Today 10:00 AM — Prelim Michigan Consumer Sentiment
Consensus 49.7, prior 47.6 (the all-time low set last month). A bounce off the floor is widely expected. Above 50.0 = sentiment recovery confirmed, rally extends. 48.0-49.7 = mild bounce, soft-landing narrative intact. Below 47.6 = NEW all-time low, stagflation fears re-engage. The inflation expectations subseries (prior 4.8% one-year) is the key Fed-relevant detail — anything above 5.0% would be a wage-spiral concern even with today’s AHE miss.
Today 12:00 PM — President Trump Speaks
No specified topic. Possible Iran/Mideast commentary given the “frozen conflict” framework, possible tariff or China commentary, possible Fed/Warsh commentary as the chair transition approaches. Trump’s recent commentary has moved markets meaningfully on each of these vectors. Watch the dollar (97.76 sub-100) for the cleanest read on tariff/policy news.
Tuesday May 12 — April CPI / Core CPI
The week’s most important macro print. April CPI is the first inflation read that fully includes $94+ WTI in the gasoline complex AND captures the post-FOMC easing-bias-removal context. Watch core CPI for any wage-passthrough on the AHE miss; watch headline CPI for energy and gasoline contributions. Earnings: JD.com (BABA-adjacent China consumer read).
Wednesday May 13 — April PPI / Core PPI + Earnings
PPI is the supply-chain inflation read — particularly relevant given ISM Manufacturing Prices Paid at 84.6 (highest since 2022). Earnings: Cisco (CSCO, networking/enterprise tech post-AAPL/MSFT), Alibaba (BABA, China/EM tech bellwether). CSCO is the cleanest networking-AI-capex confirmation; BABA carries the China-consumer signal alongside JD.
Thursday May 14 — April Retail Sales + AMAT Earnings
Retail Sales is the consumer-spending read in a $90+ oil environment. AMAT (Applied Materials) reports — the semiconductor capital-equipment bellwether and the cleanest AI-capex confirmation given SMH’s STRNG 77 / RLTV 1.31 leadership in the 34 Macro data. AMAT’s commentary on China, foundry orders, and DRAM/NAND capex will move SOXX and the broader semis complex.
Friday May 15 — Warsh Takes The Chair
After a 7-day countdown, Kevin Warsh is sworn in as Fed Chair. Powell’s last day was effectively the May 6 FOMC. Warsh inherits a labor market validated by today’s NFP, an oil market that has stabilized in $94 range, MOVE sub-baseline, and an FOMC that is fractured 8-4 between hawks (Hammack/Kashkari/Logan) and doves (Miran). Warsh’s first FOMC is June 17-18. The market’s positioning into the handoff will be defined by next week’s CPI/PPI/Retail Sales prints.
Energy — Will WTI Hold $94 Or Test $90?
WTI stabilized at $94.80 today after Wednesday’s $90.54 low. The five-session decline from $108 to $90.54 has paused. If Mideast diplomacy continues normalizing, WTI tests $87-90 (Goldman pre-conflict range). If any Hormuz incident re-emerges or Iran disrupts shipping again, oil snaps back to $100+ immediately. The energy trade has clarified: XLE at RLTV 0.99 (out of leaders for the first time), USO RLTV 1.63 (still extreme but compressing), Oil & Gas E&P (XOP) at industry rank #47. The energy complex is no longer the war’s leadership trade.
XLE Sector Rotation — The Energy Phoenix Trade Is Over
XLE’s drop to RLTV 0.99 ends an 11-session streak as the highest-RLTV sector. The capital flowing OUT of XLE needs somewhere to go. Yesterday’s 34 Macro data shows XLY (Consumer Discretionary) jumped to sector rank #2 — the rotation of choice. XLK Tech remains the structural anchor at RLTV 1.16. Watch for new leadership emergence in the May 15+ window: Industrial (XLI), Communication Services (XLC), or a quality-driven Mid-cap (IJH) bid as the post-energy rotation matures.
Morning check: Day 71. The labor market answered the question seventy days of war and oil shock had been asking. April nonfarm payrolls printed +115K against a 65K consensus — nearly DOUBLE expectations, with a 50K beat that puts cumulative March-April hiring at +293K. Average hourly earnings rose just 0.2% — a miss on consensus and identical to the prior month, confirming wage growth is not accelerating despite ten weeks of $90+ oil. Unemployment held at 4.3%, the streak of “no upward tick during the war” extending another month. The cross-asset response was the cleanest of the war: ES vaulted to 7,407 — a new war-high premium of +7.6% above pre-war 6,881.62. Yields fell across the curve (10Y −1.8 bps, 30Y −0.4 bps) — the bull flattener intact. DXY −0.40% to 97.76 — sub-100 for the second consecutive session. Silver +2.13% and Copper +2.03% — the metals tape confirms global-demand resilience. MOVE 72.24 expanded but stayed sub-baseline — the rates complex is normalized. Five of seven Mag 7 green with TSLA +3.28% leading. The 34 Macro data shows the sector rotation completing: XLK Tech still STRNG 80 / RLTV 1.16 leading, but XLE Energy fell to RLTV 0.99 — the war’s most consistent leadership trade has ended after eleven straight sessions. XLY Consumer Discretionary jumped to #2. Speculative breadth is broad: Cannabis, Rare Earth, Lithium all in Industry Leaders. The S&P sits at +7.6% above pre-war — the highest premium of the entire 71-day war. Michigan at 10:00 AM, Trump at noon, then a heavy week of CPI/PPI/Retail Sales/AMAT into the Warsh handoff Friday May 15. Pressure, not panic. Regime, not reaction. The endgame is here.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.