

1. THE QUICK SCAN
Overnight Tape Summary: RELIEF SETUP BEFORE THE INFLECTION. WTI CRASHED −2.99% TO $101.04, BRENT −3.10% TO $107.83 — FIRST SIGNIFICANT OIL PULLBACK IN A WEEK. MOVE −0.87% TO 85.32 — FIRST MOVE COMPRESSION IN 3 SESSIONS. BULL FLATTENER REGIME: 30Y −1.6 BPS TO 5.167%, 10Y −2.0 BPS TO 4.647%. BUT TUESDAY’S CASH CLOSE WAS THE WORST YIELDS PRINT OF THE WAR: 30Y CLOSED 5.183% (NEW WAR-CYCLE CLOSE-HIGH). ES +0.44% TO 7,410.50 RISK-ON. RUT +0.68% LEADS — BROAD PARTICIPATION. UK CPI Y/Y 2.8% VS 3.0% CONS — COOLER, GLOBAL DISINFLATION TAIL. TGT CRUSHED: NET SALES $25.4B (+6.7% Y/Y) BIG BEAT, EPS $1.71 VS $1.41-$1.47 CONS, SAME-STORE SALES +5.6% (FIRST POSITIVE COMP IN 5 QUARTERS!), DIGITAL +8.9%, RAISED FY GUIDE TO ~4% (FROM 2%). TGT +3.11% PRE-MARKET. MAG 7 MOSTLY RED DESPITE ES GREEN — AAPL +0.38% ONLY GREEN, MSFT −1.44%, AMZN −2.08%, GOOG −2.09%, NVDA −0.77% (4TH CONSECUTIVE DECLINE PRE-AMC). XLE +1.17%, XLV +1.10%, XLU +0.91% LEAD; XLB −2.35%, XLF −1.24%, XLI −1.18% RED. 34 MACRO TUE CLOSE: SPY 62 (−5 STRNG), USO STRNG 65/RLTV 1.80, XLE TIED WITH XLK AT STRNG 66, CIBR COMPRESSED TO 78. 2PM FOMC MINUTES + 4:30 NVDA + PANW AMC = THE WEEK’S INFLECTION.
The bond market is staging a tactical relief attempt this morning after two of the most violent sessions of the entire 83-day war. The trigger: a significant oil pullback. WTI crashed −2.99% to $101.04 — the largest single-session WTI decline in over a week. Brent collapsed −3.10% to $107.83 — back below $108 for the first time in days. The Brent peak of approximately $112 reached overnight Monday-Tuesday has now been retraced approximately $4 in 36 hours. RBOB Gasoline futures −2.67%. Heating Oil −2.11%. Natural Gas −1.35%. The energy complex pullback is broad-based — this is not a one-contract reversal. The catalyst is the absence of weekend escalation in the Iran situation combined with Trump’s Monday strike suspension being maintained — the geopolitical risk premium that built into the $108-112 Brent range is being unwound. Bond market relief follows: 30Y −1.6 bps to 5.167%, 10Y −2.0 bps to 4.647%, 5Y −2.3 bps to 4.305%, 2Y −1.8 bps to 4.104%. MOVE compressed −0.87% to 85.32 — the FIRST MOVE compression in three sessions. The Bull Flattener configuration is constructive.
But the cleanest macro signal of the past 24 hours is what happened in the Tuesday CASH SESSION. Yesterday morning’s pre-market read had 30Y at 5.152% (already a war-cycle high); Tuesday’s cash close pushed the 30Y to 5.183% — a +3.1 bp INTRADAY MOVE that took the long-end to a NEW war-cycle CLOSE-HIGH. The 10Y closed at 4.667% (vs 4.625% pre-market); 5Y at 4.328%; 2Y at 4.122%. The Tuesday cash session was the worst yields print of the entire 83-day war. Today’s Bull Flattener is essentially a half-retracement of that intraday Tuesday move — yields are back to roughly Tuesday morning’s readings, not back to the pre-Friday baseline. The structural rates-rerating remains fully intact; today’s relief is tactical positioning ahead of the 2PM Minutes / 4:30 NVDA catalysts.
And then TGT crushed the consumer thesis. Target reported BMO with the strongest comp print in five quarters: same-store sales +5.6% (first positive in five quarters), traffic +4.4%, digital +8.9% (driven by 27% growth in same-day delivery via Target Circle 360). Total net sales $25.4B vs $24.51-$24.64B consensus — a clean beat. Adjusted EPS $1.71 vs $1.41-$1.47 cons — a major +30%+ EPS surprise. Most importantly: TGT RAISED FY net sales guidance to approximately +4% growth, DOUBLING the prior +2% guide. FY EPS now expected near the high end of the $7.50-$8.50 range (cons was $8.14). CEO Fiddelke commentary: “Net sales increased in all six of our core merchandising categories” with “broad-based growth across stores and digital.” TGT +3.11% pre-market. Combined with HD’s inline beat Tuesday (revenue $41.77B, +4.8% y/y, EPS $3.43 BEAT, reaffirmed FY guide), the consumer-resilience thesis is structurally intact entering WMT Thursday. The recession-tail-from-housing-complex narrative has been pushed back by two consecutive consumer-retailer beats.
And critically, the UK CPI print at 2 AM ET delivered another disinflation surprise: UK CPI y/y 2.8% vs 3.0% consensus, DOWN from prior 3.3% — a meaningful cooling of UK headline inflation. Combined with yesterday’s Canadian CPI all-four-measures-cooler print, the global headline inflation tape is bifurcating: G10 inflation is generally cooling in May (Canada, UK), but US inflation expectations remain elevated because of the persistent oil pulse + UK wages still hot. The global disinflation tail is REAL but the US is now the outlier — and that explains why the Fed cannot cut while the BoC / BoE can. The 2PM FOMC Minutes will reveal whether Powell’s 8-4 May 6 meeting committee was already pricing this divergence; if dovish dissent was deeper than reported, US yields could compress further today.
The pre-market equity tape is a textbook “broad participation, narrow leadership unwind” rotation. ES +0.44% to 7,410.50, NQ +0.75%, RUT +0.68% — small caps LEADING the bounce. The Mag 7 tape is decisively split: AAPL $298.97 (+0.38%) ONLY green; NVDA $220.61 (−0.77%) fourth consecutive decline ahead of tonight’s 4:30 PM print (cumulative NVDA −6.4% in four sessions); TSLA $404.11 (−1.43%), MSFT $417.42 (−1.44%), META $602.61 (−1.41%), AMZN $259.34 (−2.08%), GOOG $384.90 (−2.09%). The Mag 7 split: 1 green / 6 red. But the ES is +0.44% — meaning the broad participation underneath is overwhelming the Mag 7 drag. That is the cleanest “stealth bullish rotation” signal of the war series — it would normally require Mag 7 to lead, but today is the reverse. SOXX modestly green +0.18% pre-NVDA AMC despite NVDA red — semiconductor de-risk is bottoming.
Sector tape extends the defensive bid with cyclical participation. XLE Energy +1.17% — the FOURTH consecutive day of energy leadership pre-market. XLV Health-Care +1.10% — defensive sector secondary leader. XLU Utilities +0.91% — rate-sensitive utilities ALSO catching the bond relief bid (now joining the green-side after holding war lows). XLRE Real Estate +0.43%, XLP Staples +0.22%. Five defensive sectors green. The cyclical red: XLK Tech −0.64% (NVDA/MSFT drag), XLC Comm Services −0.97%, XLY Cons Disc −1.11%, XLI Industrials −1.18%, XLF Financials −1.24% (Financials giving back Monday’s gain on Bull Flattener), XLB Materials −2.35%. The 5-green / 6-red split with energy LEADING is the cleanest possible “defensive-plus-energy reflation” tape. Factor tape mixed: SPLV +0.16%, VLUE +0.12% modest green; USMV −0.22%, MTUM −0.59%, SPHB −1.37% red. Thematics: SOXX +0.18% notable green pre-NVDA; CIBR −0.64% modest pull-back, ITA −0.87%, DRIV/PAVE −2% red.
The Number That Matters: WTI Crashed −2.99% To $101.04 + Brent −3.10% To $107.83 (First Oil Pullback In A Week) Combined With MOVE Compressing −0.87% To 85.32 (First Compression In 3 Sessions) Is The Bond Market’s Relief Setup. But Tuesday’s Cash Close Was The Worst Yields Print Of The War: 30Y Closed 5.183% (NEW War-Cycle CLOSE-HIGH). The Structural Rates Re-Rating Is Intact; Today’s Tactical Relief Sets Up The 2PM FOMC Minutes / 4:30 NVDA Inflection.
Two binary catalysts today will define the next two weeks of macro tape. FIRST: 2PM FOMC MINUTES — the FIRST WARSH-ERA RELEASE. The May 6 Powell-final-meeting 8-4 vote dissent map will be revealed. If the minutes show the dovish minority (Miran et al, now departed) was already pricing structural inflation concerns from oil + wages, that compresses today’s rates-relief tape and pushes 30Y back to 5.20%+. If the minutes show the 8-member majority was actively considering cuts pre-war shock, today’s relief extends and 30Y could compress to 5.10%. SECOND: 4:30 PM NVDA — cons $78B revenue / $1.77 EPS. NVDA has now compressed −6.4% in four pre-market sessions. The bar has structurally compressed — a clean beat-and-raise (especially the Q2 guide vs Wall Street’s $96.78B model) reignites SMH leadership and the entire AI thesis. A miss or cautious guide on China/hyperscaler demand accelerates SMH compression below STRNG 60 and engages broader equity multiple compression. Both catalysts are in the same six-hour window.
The Setup: Bull Flattener Relief + Oil Crack + TGT Crushed + UK CPI Cooled. ES +0.44% Risk-On With Broad Participation, Mag 7 Mostly Red. XLE 4th Day Leading. CIBR Compressed Modestly Tue Close. NVDA −6.4% In 4 Sessions Into 4:30 PM AMC. 2PM FOMC Minutes Defines Whether 30Y Compresses Back To 5.10% Or Re-Engages 5.20%+. The Week’s Inflection Is Today.
2. OVERNIGHT SESSION RECAP
Asia — Topix Bounces, Nikkei Continues Lag
TOPIX 3,825 (+1.04%) led the Asia tape — second consecutive Topix bounce as broad Japan recovers from the JGB 30Y at 4% absorption. Nikkei 60,465 (−0.36%) red for the fourth consecutive session — the cap-weighted Nikkei continues to bifurcate from the broader Topix, with rate-sensitive exporters remaining heavy. JPY essentially flat. AAXJ Asia ex-Japan Tuesday close STRNG 52 / RLTV 1.00 (DOWN −3 from Monday’s 55) — Asia ex-Japan compressed on the cash session yields move. FXI China STRNG 45 (UP +2 from Monday’s 43) — modest China bounce on dollar plateau.
Europe — DAX Modest Bid On UK CPI Relief
DAX 24,576 (+0.38%) modestly green. EuroStoxx 50 5,904 (+0.70%) — European indices participating in the global bond relief but more muted than yesterday’s +1.52% DAX bounce. The single overnight European signal: UK CPI y/y 2.8% vs 3.0% cons (MISS, cooler than expected). Prior was 3.3%; today’s print is a meaningful 50 bp drop from prior. UK gilt 10Y compressed modestly on the disinflation print. The BoE 9:15 AM Monetary Policy Report Hearings will be the key European catalyst this morning — Bailey commentary on the inflation trajectory and gilt market stress will define European session. EUR 1.1613 (−0.05%) modest, GBP 1.3403 (+0.04%) flat. UK bond market relief on track for the second consecutive session.
US Pre-Market — ES +0.44%, RUT +0.68% Leads, Mag 7 Mostly Red
ES 7,410.50 (+0.44%, +32 pts) — recovering off Tuesday’s lows. The cumulative ES premium vs pre-war 6,881.62 holds approximately +7.7%. NQ 29,140 (+0.75%) heavier green despite Mag 7 red — the lift coming from broad participation underneath. RUT 2,771.90 (+0.68%) LEADING the bounce — small caps catching the rate-relief bid even though they were hit hardest by yesterday’s sell-off. Dow +0.43%. The internal tape: 7 sectors trade green (XLE, XLV, XLU, XLRE, XLP all defensives PLUS the rate-relief in XLU/XLRE), Mag 7 split 1 green / 6 red. The configuration is “broad participation overwhelms narrow leadership unwind” — historically a constructive equity setup when the headline ES is also green.
Mag 7 Pre-Market — AAPL Lone Green, NVDA Continues Slide
AAPL $298.97 (+0.38%) — the ONLY Mag 7 green name, the defensive cash-flow profile catching the bid into a risk-relief tape. NVDA $220.61 (−0.77%) — FOURTH consecutive session of NVDA decline ahead of the 4:30 PM AMC catalyst. Cumulative NVDA move Friday-pre-market to today: $235.74 → $220.61 = −$15.13 / −6.4% in four sessions. SMH has compressed to STRNG 61 (from war-high 82+) on the de-risking. The bar has been substantially compressed. TSLA $404.11 (−1.43%) — Tesla continuing the post-Friday slide, now down through $410. MSFT $417.42 (−1.44%) — Microsoft’s 3-session leadership reversing today; META $602.61 (−1.41%), AMZN $259.34 (−2.08%), GOOG $384.90 (−2.09%). The Mag 7 split: 1 green / 6 red, weighted decline approximately −1.3%. But the ES is +0.44% — broad-based participation is the lift. This split is unusual: when Mag 7 is 6/7 red, the headline typically declines; today’s green ES on a Mag 7 −1.3% basket is a structural breadth signal.
Sectors — XLE 4th Day Leading + XLV/XLU Defensive Bid; Materials Crushed
XLE Energy +1.17% — the FOURTH consecutive day of pre-market energy leadership. With Tuesday close XLE at STRNG 66 / RLTV 1.05 (TIED with XLK at #1/#2 sector position), today’s extension confirms the structural Energy Phoenix engagement. XLV Health-Care +1.10% — Health-Care joining the defensive leadership; XLV bounced from STRNG 49 to 55 on Tuesday close. XLU Utilities +0.91% — utilities catching the rate-relief bid; XLU bounced from war-low 35 to 40 Tuesday. XLRE +0.43%, XLP +0.22% — full defensive cohort green. The cyclical red: XLK Tech −0.64% on NVDA/MSFT drag, XLC −0.97% on GOOG/META drag, XLY Cons Disc −1.11%, XLI Industrials −1.18%, XLF Financials −1.24% (giving back Monday’s +7 STRNG bounce), XLB Materials −2.35% (with XLB at Tuesday close STRNG 34 — NEW WAR LOW for Materials sector). The Materials weakness is the cleanest single negative signal — XLB at war-low STRNG reflects sustained global demand concerns + metals consolidation post-crash.
Factors — Defensives Modestly Green, Reflation Factors Red
SPLV Low-Vol +0.16%, VLUE Value +0.12% — modest defensive/value green. USMV Min-Vol −0.22% (unusual — Min-Vol usually leads with SPLV on defensive tapes), DGRO Dividend Growth −0.34%, VYM High-Dividend −0.46%, QUAL Quality −0.65%. RSP Equal-Weight −0.58%, LRGF −0.61%, MTUM Momentum −0.59% — momentum has bottomed near current levels after the post-Friday 4-session unwind. IJR Small-Cap −0.92%, IJH Mid-Cap −0.97%. SPHB High-Beta −1.37%. The configuration is the cleanest mid-cycle defensive rotation: defensives modestly outperforming but no extreme spread. Today’s factor tape is less polarized than the Friday-Monday-Tuesday sessions — a sign positioning has reached a near-term equilibrium ahead of the 2PM Minutes / 4:30 NVDA inflection.
Thematics — SOXX Modestly Green Pre-NVDA, CIBR Pulls Back Slightly
SOXX Semiconductor +0.18% — modestly green pre-NVDA, the first SOXX green print in four sessions. Pre-NVDA semi de-risking has bottomed. ARKG Genomic +0.04%. The cyber pull-back: CIBR Cybersecurity −0.64% — modest profit-taking after Tuesday close compressed CIBR from war-high 81 to 78, but RLTV 1.14 holds (cyber thesis intact). PANW reports AMC into this configuration. ITA Aerospace Defense −0.87%, FINX FinTech −0.64%, BLOK Crypto −1.03%, ARKW Next-Gen Internet −1.18%, ARKQ Autonomous −1.47%, ICLN Clean Energy −1.59%, PAVE Infrastructure −1.74%, DRIV Autonomous EV −2.05%. The thematic tape is broadly red but with much less extreme dispersion than yesterday — consolidation pattern. The single most important pre-NVDA signal: SOXX green despite NVDA red. That means broader semis are absorbing the NVDA-specific de-risk; the AI thesis at the index level is finding support.
Commodities — Oil Crashed 3%+, Metals Modestly Bid
The headline commodity story of the morning: OIL COLLAPSED. WTI $101.04 (−2.99%) — the largest single-session WTI decline in over a week, down approximately $3.11 from Tuesday’s settle near $104. Brent $107.83 (−3.10%) — back below $108 for the first time in five sessions. Brent’s peak of approximately $112 reached overnight Monday-Tuesday has now retraced $4 in 36 hours. The energy complex selloff is broad-based: RBOB Gasoline −2.67%, Heating Oil −2.11%, Natural Gas −1.35%, Ethanol −0.52%. The catalyst combination: Trump’s Monday strike suspension maintained, no weekend Iran escalation, and Saudi/UAE/Qatar diplomatic intervention continuing. The geopolitical risk premium that built into the $108-112 Brent range is unwinding. METALS modestly bid: Silver +1.11%, Copper +0.65%, Platinum +0.02% — metals catching the relief bid as the dollar stalls and rates compress. Gold $4,505 (−0.14%) flat. Softs mixed: Orange juice +3.54%, Sugar +0.47%; Cotton −1.64%, Cocoa −0.74%. GRAINS mostly red: Corn −1.16%, Soybeans −0.52%, Wheat −0.37%. Lean Hogs −0.61%. The commodity tape is “oil crack, metals relief bid” — a structural reversal pattern.
3. THE PRIOR DAY’S REGIME
34 Macro Price, Strength & Momentum Rankings — Daily Close, Tuesday May 19. SPY Baseline: STRNG 62 | MNTM +7 | RLTV 1.00. SPY −5 STRNG vs Monday — Cash Session Continued The Compression.
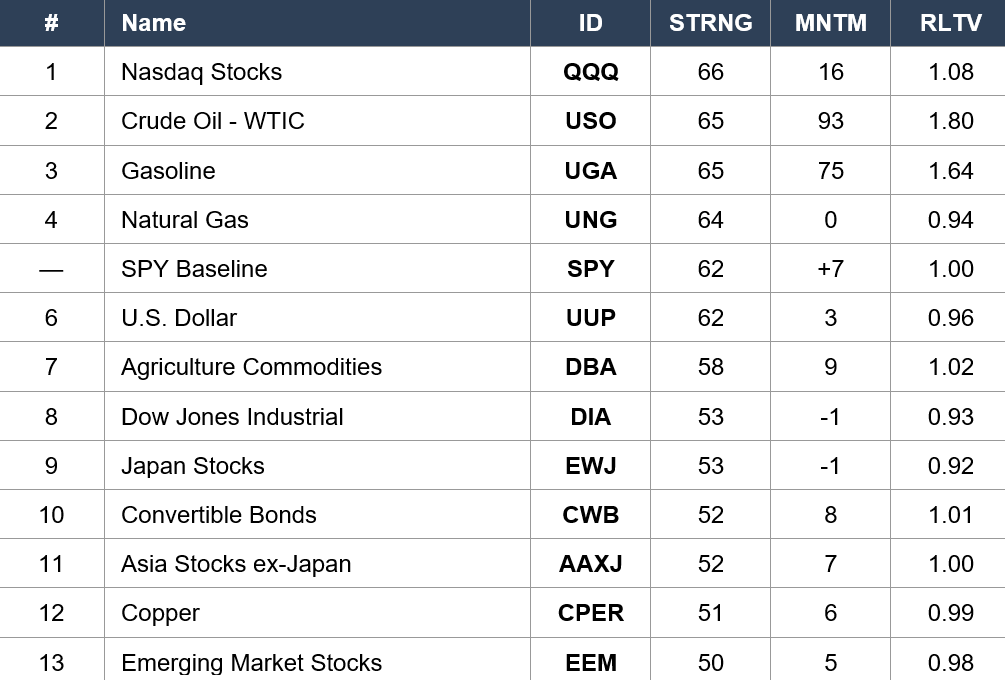
Asset Classes — Leaders (Energy Complex Dominates; USO Holds RLTV 1.80)
Asset Classes — Laggers (Bond Complex Crushed; PPLT Recovers From Anomaly)
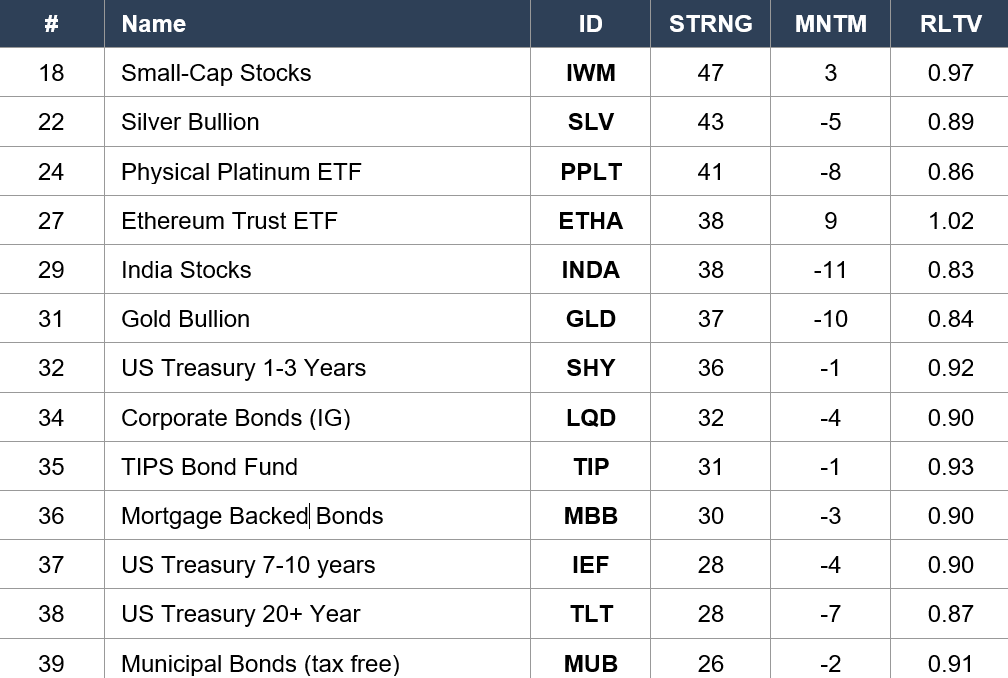
Regime signal: TUESDAY’S CASH CLOSE EXTENDED MONDAY’S COMPRESSION DRAMATICALLY. SPY baseline crashed from STRNG 67 to 62 — an additional −5 STRNG decline on top of the −1 from Friday-Monday. Cumulative SPY STRNG decline Fri-Mon-Tue: 79 → 68 → 67 → 62, a NET −17 STRNG across three sessions, the LARGEST sustained 3-session SPY STRNG decline of the entire 83-day war series. QQQ from 69 → 66. The ENERGY COMPLEX HELD ITS LEADERSHIP: USO Crude STRNG 62 → 65 (+3) — extending the war-high STRNG further with RLTV 1.80 holding. UGA Gasoline held STRNG 65 / RLTV 1.64 (RLTV pulled in from 1.67 on the oil rally peak). UNG Natural Gas JUMPED from STRNG 59 → 64 (+5) — gas catching the oil bid; RLTV 0.94. The DOLLAR STRENGTHENED: UUP STRNG 59 → 62 (+3) on the global flight-to-dollar trade. DBA Agriculture STRNG 57 → 58 marginal extension. The METALS COMPLEX COMPRESSED: SLV Silver STRNG 48 → 43 (−5), CPER Copper STRNG 56 → 51 (−5) with RLTV slipping back BELOW baseline 0.99 (eliminating Monday’s mean-reversion bounce), GLD Gold STRNG 41 → 37 (−4). THE BOND COMPLEX WAS CRUSHED: TLT 20+Y STRNG 31 → 28 (−3, war-low), IEF 7-10Y STRNG 31 → 28 (−3, war-low), LQD Corporate STRNG 36 → 32 (−4), MBB Mortgage STRNG 34 → 30 (−4), MUB Munis STRNG 31 → 26 (−5, deepest read of war), TIP STRNG 36 → 31 (−5). Every duration along the US Treasury curve hit a new STRNG war-low. The PPLT Platinum ETF RECOVERED from Monday’s anomalous STRNG 12 / RLTV 0.09 reading to STRNG 41 / RLTV 0.86 — confirming yesterday’s reading was a data-anomaly, NOT a structural break. International equity compressed: AAXJ STRNG 55 → 52, EEM 53 → 50, DIA Dow STRNG 57 → 53 (−4).
Sector ETFs (XLE Tied With XLK At Top; XLB NEW War Low; XLF Reversed)
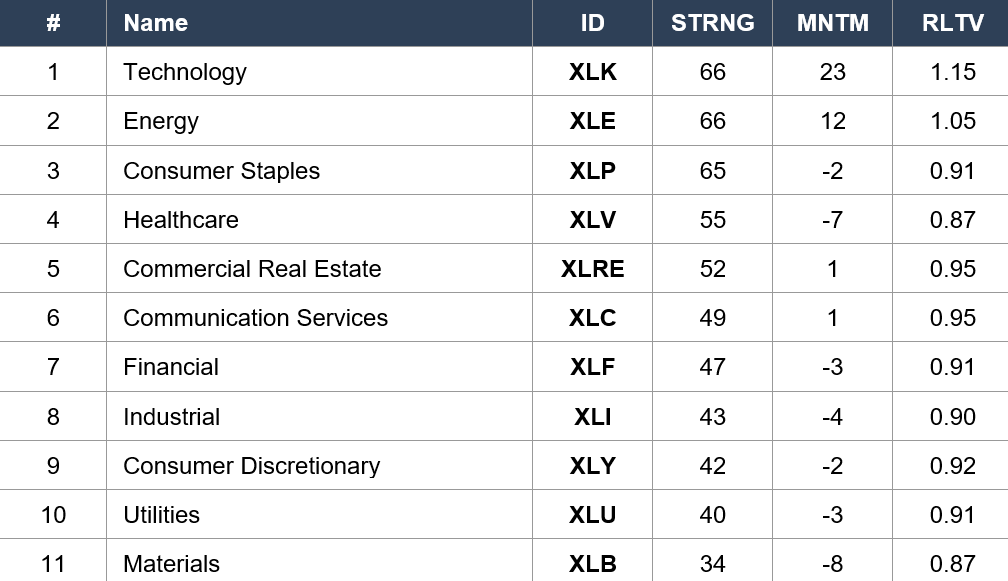
Regime signal: TUESDAY’S SECTOR CLOSE WAS THE CLEANEST “ENERGY PHOENIX FULL ENGAGEMENT” SIGNAL OF THE WAR. XLE Energy SURGED from STRNG 63 → 66 (+3) / RLTV 1.04 → 1.05 — XLE is NOW TIED WITH XLK AT STRNG 66 at the top of the sector rankings. This is the first time since Day 10-15 of the war that Energy has matched Technology at the top of the sector list. RLTV 1.05 is the highest XLE RLTV reading of the entire 83-day war series. XLK Tech compressed from STRNG 68 → 66 (−2) / RLTV 1.16 → 1.15 — tech still holds nominal #1 by alphabetical ordering but XLE has structurally caught up. XLP Consumer Staples HELD #3 at STRNG 65 (+1) — staples leadership extending into TGT/WMT earnings. XLV Health-Care SURGED from STRNG 49 → 55 (+6) — the largest single-session XLV STRNG move in over a month; defensives broadening leadership. XLRE Real Estate up +2 to STRNG 52. XLC Comm Services CRASHED from STRNG 54 → 49 (−5) on GOOG/META weakness. XLF Financials COMPRESSED from STRNG 54 → 47 (−7) — REVERSING Monday’s entire +7 STRNG bounce; the Bear Flattener regime is bad for banks (long-end stable, front-end up = NIM compression). XLI Industrials STRNG 43 (−4). XLY Cons Disc STRNG 42 (−4). XLU Utilities recovered modestly to STRNG 40 (+5). XLB MATERIALS CRASHED from STRNG 41 → 34 (−7) — NEW WAR LOW for Materials sector. The XLB war-low reflects sustained global demand concerns + metals consolidation post-crash. The 7/11 sectors declined Tuesday; only XLK / XLP / XLE / XLV / XLRE / XLU bounced or held.
Industry ETFs — Leaders (CIBR Still #1 STRNG 78; XOP / AMLP Extending)
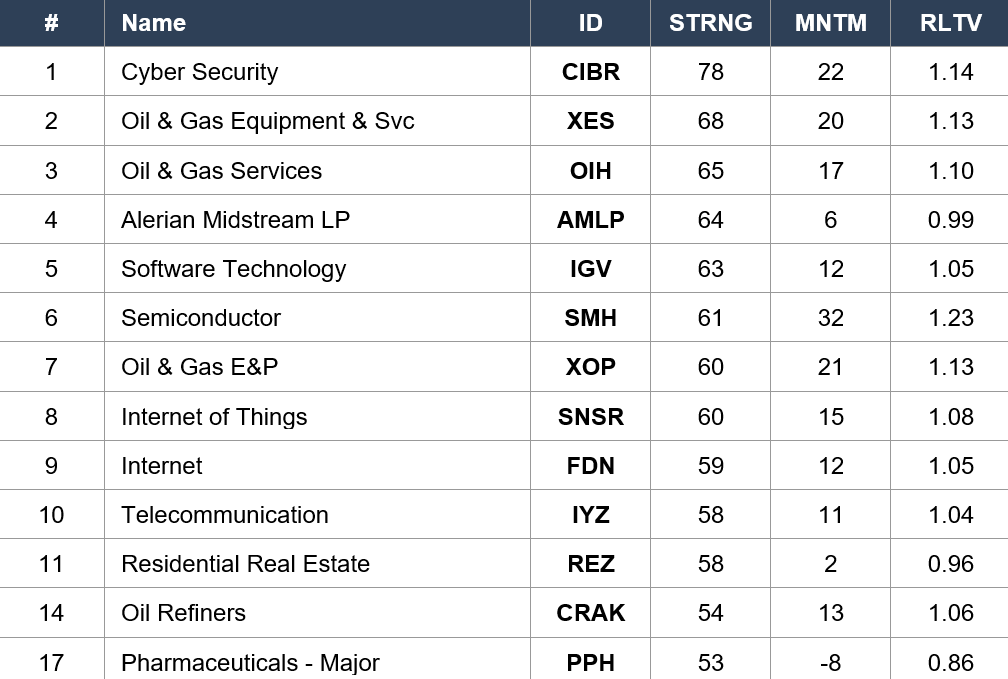
Industry ETFs — Laggers (Housing Re-Engaged At War Lows; ITA Compressed)
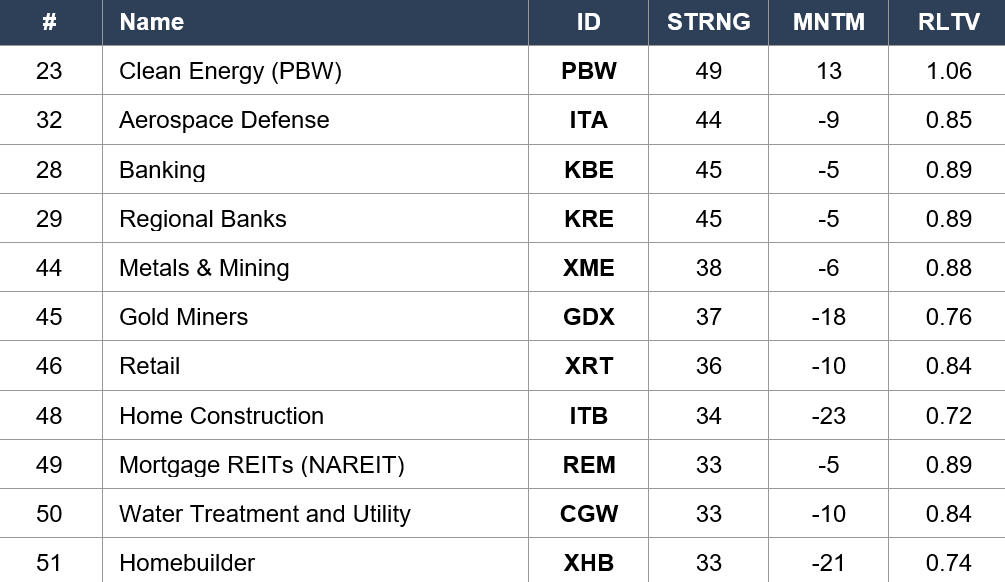
Regime signal: THE INDUSTRY ROTATION ON TUESDAY WAS PARTIAL PROFIT-TAKING IN THE LEADERS, RE-ENGAGEMENT IN THE WAR-LOW LAGGERS. CIBR Cybersecurity COMPRESSED from STRNG 81 → 78 (−3) — pulling back from Monday’s NEW war-cycle high but RLTV 1.14 held intact (cyber thesis structurally maintained). XES Oil Equipment compressed STRNG 71 → 68 (−3) / RLTV 1.13. OIH Oil Services compressed STRNG 68 → 65 (−3) / RLTV 1.10. AMLP MIDSTREAM EXTENDED from STRNG 62 → 64 (+2) / RLTV 0.98 → 0.99 — midstream is now closest-to-baseline of the energy services complex; the energy infrastructure layer is consolidating leadership. XOP OIL & GAS E&P EXTENDED from STRNG 57 → 60 (+3) / RLTV 1.12 → 1.13 — upstream cyclical continuing to extend. CRAK Oil Refiners up STRNG 52 → 54 (+2) / RLTV 1.06 — downstream refining catching the bid. The full energy services / infrastructure / upstream / downstream complex is now positioned in the top 14 industries. IGV Software compressed STRNG 66 → 63 (−3). SMH Semiconductor held STRNG 61-62 zone. PPH Pharma SURGED from STRNG 47 → 53 (+6) — healthcare positioning into XLV strength. The MAJOR REVERSALS: PBW Clean Energy crashed FURTHER from STRNG 55 → 49 (−6) — clean energy complex now AT war-low zone. TAN Solar STRNG 59 → 53 (−6). KBE Banking STRNG 47 → 45 (−2), KRE Regional Banks 47 → 45 (−2) — banks reversed Monday’s gain. THE HOUSING COMPLEX RE-ENGAGED IN WAR-LOWS: ITB Home Construction STRNG 36 → 34 (−2) / RLTV 0.72 — back near war-low zone. XHB Homebuilders STRNG 36 → 33 (−3) / RLTV 0.74 — NEW war-low. CGW Water Treatment STRNG 36 → 33 (−3) — NEW war-low. REM Mortgage REITs STRNG 37 → 33 (−4) — deepest reading. The Monday recovery in housing was fully unwound Tuesday.
4. MORNING DATA REACTION
Already Released — UK CPI Cooled, TGT Crushed
The 2:00 AM ET UK CPI print: y/y 2.8% vs 3.0% cons — MISS, cooler than expected. Prior was 3.3%; today’s 2.8% represents a 50 bp drop in UK headline inflation. Combined with yesterday’s Canadian CPI all-four-measures-cooler print, the G10 disinflation tape is bifurcating: Canada + UK are cooling, while US oil pulse + UK wages (4.1% hot yesterday) keep US/UK wage inflation engaged. UK gilt 10Y compressed modestly. The BoE 9:15 AM Monetary Policy Report Hearings will provide further European session direction; Bailey commentary on cuts will matter. The implication for US Fed: BoE / BoC have room to ease independent of Fed; US is now the relative-tightening outlier. The 2PM FOMC Minutes will reveal whether Powell’s 8-4 Mar/May meeting committee was pricing this divergence already.
TGT Target Earnings (Released BMO) — MAJOR Beat, Raised FY Guide
TGT reported before the bell with a structurally important beat. Net sales $25.4B vs $24.51-$24.64B consensus — MAJOR beat, +6.7% y/y. Adjusted EPS $1.71 vs $1.41-$1.47 cons — clear +30% EPS surprise. Comparable sales +5.6% — the FIRST positive comp print in five quarters. CEO Michael Fiddelke commentary: “Net sales increased in all six of our core merchandising categories” with “broad-based growth across our business.” Traffic +4.4% across stores and digital. Digital comp +8.9% (driven by 27% growth in same-day delivery via Target Circle 360). Non-merchandise sales (Roundel, Target Circle 360, Target Plus) grew ~25%. CRITICALLY: TGT RAISED FY net sales guidance to approximately +4% growth, DOUBLING the prior +2% guide. EPS now expected near the high end of the prior $7.50-$8.50 range. TGT +3.11% pre-market — clean positive reaction. The implications are significant: (1) US consumer is structurally stronger than positioning indicated, (2) the higher-income trade-down narrative + value-orientation has accelerated, (3) Same-day delivery is genuinely working as a moat. Combined with HD’s inline beat Tuesday (Rev $41.77B BEAT, EPS $3.43 BEAT, reaffirmed FY guide), the consumer-resilience thesis is structurally intact. WMT Thursday earnings now sits as the third confirmation point.
Coming Up Today — 2PM Minutes + 4:30 PM NVDA + PANW AMC
The single most consequential trading day of the post-NFP cycle. (1) FOMC MINUTES 2:00 PM — the FIRST WARSH-ERA RELEASE. The May 6 Powell-final-meeting 8-4 vote dissent map. Watch for hawkish-skewed commentary from Hammack / Kashkari / Logan; any signal that the dovish minority (Miran exited with Warsh confirmation) was already isolated would re-engage 30Y above 5.20%. Conversely, if the 8-member majority was actively pricing cuts pre-war shock, that compresses yields. (2) NVDA EARNINGS 4:30 PM AMC — cons $78B revenue / $1.77 EPS. NVDA $220.61 (−6.4% in four sessions), bar significantly compressed. AMAT raised 2026 semi-equipment growth guide to >30% is the floor. NVDA must confirm hyperscaler demand visibility through 2027 and the Q2 guide vs Wall Street’s $96.78B model. (3) PANW AMC — cyber bellwether with CIBR at STRNG 78 (down from war-high 81 but still #1 industry). PANW guide commentary on next-gen security platform demand defines whether cyber thesis extends through Q3.
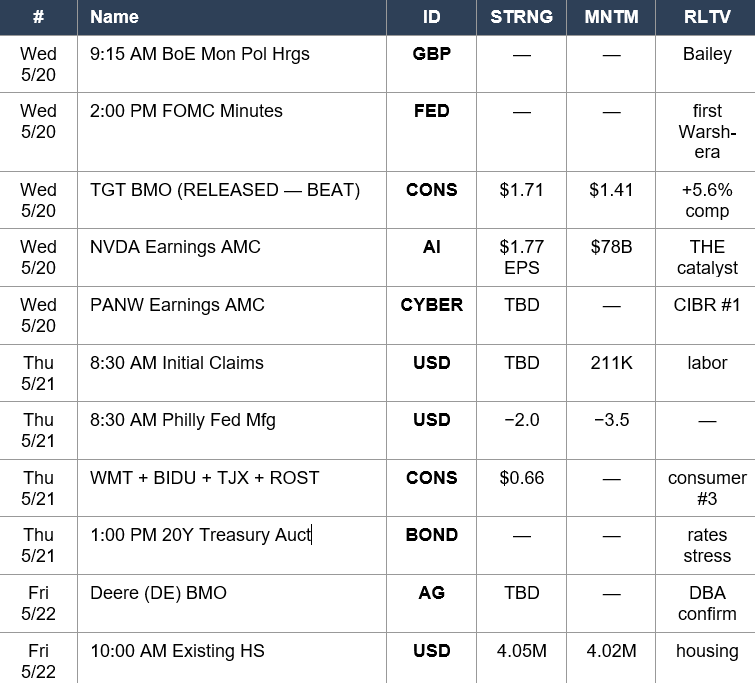
Rest Of Week Calendar
5. THE DYRH READ
Yield Curve Regime: Bull Flattener — Tactical Relief After Tue Cash-High
The curve flipped back to a Bull Flattener overnight: 2Y −1.8 bps to 4.104%, 5Y −2.3 bps to 4.305%, 10Y −2.0 bps to 4.647%, 30Y −1.6 bps to 5.167%. The 2s/30s spread is 106.3 bps. The Bull Flattener (yields falling, front slightly faster than long) is constructive for risk assets. CRITICALLY, the relief is OFF Tuesday’s CASH CLOSE which set new war-cycle highs across the curve: 30Y closed 5.183%, 10Y closed 4.667%, 5Y closed 4.328%, 2Y closed 4.122%. Tuesday’s cash session pushed yields UP from the pre-market levels — a structural intraday move. Today’s pre-market is approximately half-way between Tuesday’s pre-market and Tuesday’s close. The relief is tactical, not structural. The 20-year Treasury auction Thursday 1:00 PM is the true stress test of demand. If today’s tape holds and the FOMC Minutes don’t deliver hawkish surprise, 30Y could compress to 5.10%. If the Minutes are hawkish, 30Y likely re-engages above 5.20% and pushes the 10Y above 4.70%.
MOVE Index: 85.32 (−0.87%) — First Compression In 3 Sessions
MOVE compressed −0.75 points to 85.32 — the FIRST MOVE compression in three sessions after consecutive expansions: 79.87 (Fri) → 86.07 (Tue pre-market peak) → 85.32 today. MOVE remains 12.11 points above the pre-war baseline of 73.21 and 18.07 points above the war-low of 67.25. The compression today is tactical relief on the oil crack; the structural rates-vol re-rating remains intact. The implied volatility premium being priced in Treasury futures options reflects: structurally higher rate path uncertainty, oil supply tail (now partially unwinding), Japanese yield repression end, ~35-40% hike probability priced. MOVE compression to 80 by Friday would signal the bond market has fully digested the new regime. MOVE expansion back above 88 would signal crisis re-engagement. Today’s 85.32 reading is the inflection point.
S&P 500: ES 7,410.50 — Recovering From Tuesday Lows
ES at 7,410.50 (+0.44%, +32 pts) bounces off Tuesday’s test of the 7,400 support. Tuesday’s cash session settled around 7,378 (below the support I flagged), then rebounded into the close on the late-day Iran-strike-suspension narrative. Cumulative ES gain from pre-war 6,881.62 holds at approximately +7.7%. The market has structurally absorbed the Friday-Monday-Tuesday bond shock without breaking below the +7% war-premium zone — a sign of underlying resilience. The technical levels: 7,400 acts as immediate support, 7,380 as the more meaningful structural level. A clean hold above 7,400 today + a no-surprise FOMC Minutes 2PM sets up NVDA AMC into a constructive technical posture. A break of 7,380 on hawkish Minutes + NVDA miss would engage the next leg lower into 7,300.
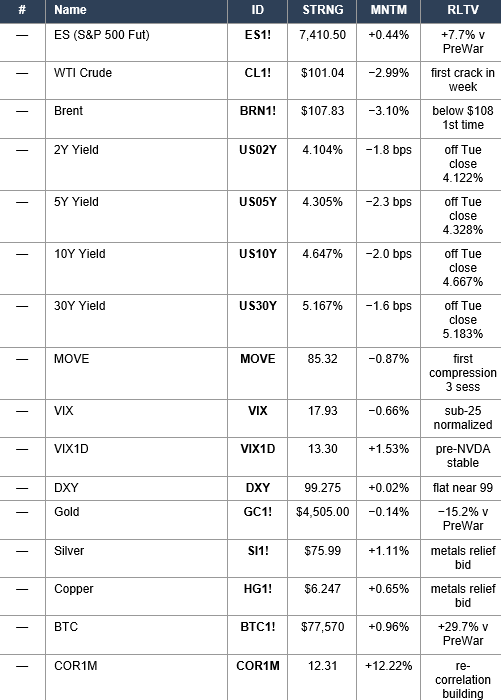
Key Levels & Cumulative War Moves
Volatility & Breadth — VVIX Up 3.76%, COR1M Building Toward 13
The vol read: VVIX +3.76% to 94.61 — the volatility-of-volatility is BID into the 4:30 NVDA. VVIX above 90 reflects elevated tail risk pricing for the NVDA print. VIX 17.93 −0.66% modest. VIX1D 13.30 +1.53% — short-dated equity vol up modestly. GVZ Gold-Vol +1.64%. VXN Nasdaq-Vol −0.50% slight compression. MOVE 85.32 −0.87% — the bond market’s relief signal. The two-tier vol story is unchanged: rates vol structurally elevated, equity longer-dated vol calm. COR1M +12.22% to 12.31 — the post-Friday correlation regime is building; the dispersion-led stock-picker era is meaningfully compressing as macro re-engages. SKEW −2.10% to 135.50 — modest pull-back from yesterday’s level. Breadth holds the constructive read (S5TH 70.10, S5FI 61.30) but stale; Tuesday’s session likely degraded these. The vol + correlation read: pre-NVDA hedging premium is consolidated, not extreme; bond market is delivering tactical relief; equity macro regime is calmly absorbing.
6. THE GAME PLAN
Today: THE INFLECTION DAY. Bull Flattener relief setup after Tuesday cash close set new war-cycle yields highs (30Y 5.183%). Oil crashed −3%. MOVE compressed first time in 3 sessions. ES +0.44% risk-on. TGT crushed earnings + raised guide. UK CPI cooled. Mag 7 mostly red but ES green = broad participation. XLE 4th day leading, XLE TIED with XLK at #1 sector. CIBR pulled back to STRNG 78 Tue close but still #1 industry. 2PM FOMC Minutes + 4:30 NVDA + PANW AMC = binary catalysts.
The Bull Case
Oil cracked 3% overnight — WTI down to $101, Brent down to $107.83 (back below $108 first time in five sessions). The geopolitical risk premium that built into the $108-112 Brent range is unwinding on the Trump-strike-suspension narrative + continued Gulf nation diplomatic intervention. Bond market relief follows: 30Y at 5.167% (off Tuesday’s war-high close 5.183%), 10Y at 4.647% (off Tuesday’s 4.667%). MOVE compressed −0.87% to 85.32 — FIRST MOVE compression in three sessions. Bull Flattener configuration is constructive. UK CPI cooled to 2.8% (vs 3.0% cons) — global disinflation tail is real (Canada cooled Tuesday, UK cooled today). TGT MASSIVE BEAT: +5.6% comp (first positive in 5 quarters!), +30% EPS surprise, raised FY guide DOUBLED to +4%. Combined with HD’s inline beat Tuesday, the consumer-resilience thesis is structurally intact. The structural rotation has positioned: XLK Tech still #1 at STRNG 66 / RLTV 1.15 (AI thesis intact at RLTV level), XLE Energy TIED with XLK at STRNG 66 / RLTV 1.05 (highest XLE RLTV of war), XLP Staples STRNG 65 (defensive bid extending into WMT Thursday), XLV Health-Care STRNG 55 (+6 STRNG Tuesday). CIBR Cybersecurity at STRNG 78 / RLTV 1.14 (still #1 industry, pulled back modestly from war-high 81 but RLTV held). NVDA $220 ahead of 4:30 PM — bar substantially compressed by 4-session slide. SMH at STRNG 61 / RLTV 1.23 still above baseline. ES holds +7.7% above pre-war. Pre-market broad participation: RUT +0.68% LEADING, ES +0.44% on Mag 7 mostly red — the rotation breadth is structurally bullish. If FOMC Minutes show no hawkish surprise + NVDA beats with confident Q2 guide, today’s yields highs become this cycle’s peak and the post-Friday rout becomes a one-week repositioning. If oil continues lower this week, MOVE compresses to 80, NVDA delivers + AMAT-floor confirmation, the structural break narrative dies.
The Bear Case
Tuesday’s CASH CLOSE was the worst yields print of the entire 83-day war: 30Y closed 5.183% (NEW war-cycle close-high), 10Y closed 4.667%, 5Y 4.328%, 2Y 4.122%. ALL FOUR durations at new close-highs simultaneously — the structural rate regime re-rating is intact. Today’s Bull Flattener is tactical, not structural; pre-market yields are roughly Tuesday morning’s levels, not pre-Friday levels. MOVE remains at 85.32 — above pre-war baseline 73.21 by 12.11 points. Markets still pricing ~35-40% rate HIKE probability by year-end. The Mag 7 split is unusual: 1 green / 6 red (only AAPL up), with NVDA −0.77% (cumulative −6.4% in 4 sessions). MSFT/AMZN/GOOG/META all red, suggesting the structural Mag 7 leadership is breaking apart. SOXX is modestly green (+0.18%) but XLB Materials at STRNG 34 — NEW war-low for Materials sector. XHB Homebuilders STRNG 33 / RLTV 0.74 — NEW war-low; CGW Water Treatment STRNG 33 — NEW war-low; ITB Home Construction STRNG 34 / RLTV 0.72 near war-low. Housing recovered modestly Monday but Tuesday cash close PUSHED IT BACK to war-low zone. PBW Clean Energy at STRNG 49 — Clean Energy complex fully compressed (the post-NFP era thematic break extends). XLF Financials gave back ALL of Monday’s +7 STRNG bounce on the Bear Flattener dynamic. KBE Banking STRNG 45 (−2 Mon-Tue), KRE Regional Banks 45 (−2). The FOMC Minutes 2PM is high-tail-risk: if Powell’s 8-member majority was actively pricing structural inflation, the minutes will read as the inflection that confirmed Warsh inherits a hawkish-skewed committee. NVDA 4:30 PM is even higher tail risk: a Q2 guide below $90B (vs $96.78B Wall Street model) compresses SMH below STRNG 55 and accelerates risk-off. China commentary on H20 chip restrictions could also disappoint. Even a clean NVDA beat may not be enough to undo the bond market’s structural repricing — the macro tape is in the bond seat, not the equity seat. Watch ES 7,380 support; a break engages 7,300.
Regime: Bull Flattener — Tactical Relief Off Tuesday Cash War-Highs / Oil Crack / TGT Crushed. Today is THE INFLECTION DAY. The 2PM FOMC Minutes + 4:30 NVDA + PANW AMC will define whether the post-Friday rout was a one-week repositioning or a structural break. Energy continues leading (XLE TIED with XLK at #1 sector). Cyber compressed modestly but holding. Mag 7 mostly red with broad participation lifting ES. Watch 30Y 5.10% (compression target) vs 5.20% (re-engagement), MOVE 80 (resolution) vs 88 (crisis), NVDA close (binary AI tape), ES 7,400 support.
Watch List
TODAY 2:00 PM ET — FOMC Meeting Minutes (FIRST WARSH-ERA RELEASE)
The most consequential Fed communication of the post-NFP cycle. The Powell-final-meeting (May 6) 8-4 vote dissent map will be revealed. Watch for: (1) Composition of the 8-member majority — how broadly was the “cuts later this year” view shared? (2) Hawkish dissent commentary from Hammack / Kashkari / Logan voicing structural inflation / oil-pulse concerns; (3) Discussion of the oil pulse, wage growth, and the global rates regime; (4) Any direct commentary on Warsh’s arrival and policy transition. A hawkish-skewed read pushes 30Y above 5.20% / 10Y above 4.70% and re-engages bond crisis framework. A dovish-skewed read (8-member majority actively considering cuts) compresses 30Y toward 5.10% and gives oxygen to the post-Friday rout being a one-week event. The 20Y Treasury auction Thursday is the bond market’s self-test of the Minutes reaction.
TONIGHT 4:30 PM ET — NVDA Q1 FY27 Earnings (AMC)
The single most consequential single-stock catalyst of the post-NFP cycle. Cons: revenue $78.0B / EPS $1.77. Watch: (1) Q2 revenue guide vs Wall Street’s $96.78B model — a guide above $95B reignites SMH leadership; below $92B engages broader semi compression; (2) Data-center revenue and hyperscaler demand visibility through 2027; (3) China commentary — H20 chip restrictions and broader export-control impact; (4) Gross margin trajectory; (5) Blackwell / Rubin supply commentary. AMAT raised 2026 semi-equipment growth guide to >30% — the structural floor under the thesis. NVDA has compressed −6.4% in four sessions ($235.74 → $220.61), the bar is substantially lower than Monday’s pre-market levels. A clean beat-and-raise with confident commentary likely pulls NVDA +3-5% in AMC and ignites SMH back above STRNG 65. A miss or cautious guide pulls NVDA −5-10% AMC and compresses SMH below STRNG 55 — which would then drag XLK below STRNG 60 Thursday.
TONIGHT — Palo Alto Networks (PANW) AMC
PANW cyber bellwether reports AMC. CIBR Cybersecurity has been the structural leadership story of the war series — STRNG 81 Mon close (new war-high any industry), STRNG 78 Tue close still #1 / RLTV 1.14. PANW guide commentary on next-generation security platform demand, AI-defense capex, federal contracts, and SD-WAN momentum will define whether the cyber structural thesis extends through Q3 — or whether CIBR’s Monday war-high marked the cycle peak. The cyber thesis has been Cyber’s decoupling from broader macro that’s held throughout the Friday-Monday-Tuesday compression; PANW must deliver a clean beat with strong forward guide to sustain that decoupling.
Thursday 5/21 — WMT BMO + Claims + Philly Fed + 20Y Treasury Auction 1PM
WMT Walmart BMO — the third and final consumer barometer of the week; cons EPS $0.66. With HD inline beat Tuesday + TGT MASSIVE beat today, WMT is the structural confirmation. Watch: grocery comp, higher-income trade-down read, Walmart Connect ad revenue, Walmart+ membership trends, gross margin. Initial Claims 8:30 (vs 211K prior). Philly Fed Mfg Index (cons −2.0 vs −3.5). And the 20-YEAR TREASURY AUCTION 1:00 PM — the cleanest stress test of demand at elevated yield levels (30Y at 5.15-5.18%). A tail at the auction pushes 30Y to 5.25%+; strong demand confirms cycle peak. With every duration at war-cycle highs Tuesday close and ~40% hike probability priced, this auction matters more than usual.
Friday 5/22 — Deere (DE) BMO + Existing Home Sales
DE Deere BMO — agricultural-equipment bellwether. DBA Agriculture STRNG 58 Tuesday (still recovered from Friday’s −21 STRNG crash). DE’s commentary on farm income, equipment order trends, and 2026 outlook will define whether DBA structural break is real or one-session positioning unwind. Existing Home Sales (cons 4.05M vs 4.02M prior) — housing confirmation point.
Energy — XLE Tied With XLK At Top; USO STRNG 65 / RLTV 1.80 Holds Despite Oil Crack
The structural Energy Phoenix engagement is the cleanest single positioning signal of the past week. Tuesday close: XLE Energy at STRNG 66 / RLTV 1.05 (highest XLE RLTV of entire 83-day war) — TIED with XLK at the top of sector rankings. USO Crude at STRNG 65 / RLTV 1.80 — extended +3 STRNG even on a session where SPY dropped −5 STRNG. UGA Gasoline held STRNG 65 / RLTV 1.64. UNG Natural Gas SURGED +5 to STRNG 64 / RLTV 0.94. XES Oil Equipment STRNG 68 (rank #2 industry). OIH Oil Services STRNG 65 (rank #3). AMLP Midstream STRNG 64 (rank #4) extending. XOP Oil & Gas E&P STRNG 60 (rank #7) extending. CRAK Oil Refiners STRNG 54 (rank #14) — refining catching the bid. Five energy-services-or-infrastructure industries in the top 14. Pre-market today XLE +1.17% extends the leadership for a 4th consecutive day — even on the oil −3% pullback (telling: energy equities are holding the structural bid even as commodities consolidate). If WMT Thursday is constructive and oil holds above $95, energy could displace tech as #1 sector by Friday close.
AI/Semis — NVDA 4:30 PM AMC Is The Binary Test; Bar Substantially Compressed
NVDA $220.61 (−0.77%) — fourth consecutive session of NVDA decline. Cumulative move from Friday pre-market $235.74: −$15.13 / −6.4%. SMH Tuesday close STRNG 61 / RLTV 1.23 (down from war-high STRNG 82 / RLTV 1.30+, but RLTV still well above baseline). The AI thesis at the index level is being repositioned downward but not broken. NVDA consensus: revenue $78.0B, EPS $1.77. The forward Q2 guide ($96.78B Wall Street model) is the structural read. AMAT raised 2026 semi-equipment growth guide to >30% provides the floor. SOXX modestly green pre-market (+0.18%) despite NVDA red — broader semi positioning has bottomed and is positioning for a beat. A clean beat-and-raise with confident hyperscaler 2027 demand commentary likely pulls NVDA +3-5% AMC and ignites SMH leadership back above STRNG 65. A miss or cautious guide engages SMH compression below STRNG 55, drags XLK below STRNG 60 Thursday, and pulls broader risk-off through Friday.
Cyber — CIBR Still #1 But Pulled Back; PANW AMC Defines The Continuation
CIBR Cybersecurity Tuesday close STRNG 78 / RLTV 1.14 — pulled back −3 STRNG from Monday’s war-cycle high of 81, but RLTV held intact. CIBR remains #1 industry by clear margin (XES #2 at STRNG 68). The cyber structural decoupling from broader macro is the cleanest single thematic positioning signal of the post-NFP cycle. PANW reports AMC into this configuration. Pre-market CIBR −0.64% — modest profit-taking pre-PANW. PANW guide commentary on next-generation security platform demand, AI-defense capex, federal contracts, and SD-WAN momentum will define whether the cyber thesis extends through Q3 — or whether Monday’s STRNG 81 marked the cycle peak.
Bonds — Tue Cash Close New War-Cycle Highs; Today Tactical Relief
Tuesday’s cash session pushed yields to NEW war-cycle close-highs: 30Y closed 5.183%, 10Y 4.667%, 5Y 4.328%, 2Y 4.122%. All four durations at the highest closing levels of the entire 83-day war. Today’s pre-market is roughly Tuesday morning’s levels — about half-way between Tuesday open and Tuesday close. MOVE compressed to 85.32 (still elevated, but first compression in 3 sessions). The 20-YEAR TREASURY AUCTION Thursday 1:00 PM is the bond market’s self-test. A tail engages 30Y above 5.20%; strong demand confirms cycle peak. With ~35-40% Fed hike probability priced for year-end (first time during the war), bond market is pricing structural higher rate path — Warsh’s first FOMC June 16-17 carries real hike tail. Watch the 30Y 5.10% (compression target) vs 5.20% (re-engagement) range.
Morning check: Day 83. THE inflection day arrives with a tactical bond-relief setup. WTI crashed −2.99% to $101.04, Brent collapsed −3.10% to $107.83 (below $108 first time in five sessions) — the first significant oil pullback in over a week. The geopolitical risk premium that built into the $108-112 Brent range is unwinding on Trump’s Monday strike suspension being maintained + continued Saudi/UAE/Qatar diplomatic intervention. Bond market relief follows: 30Y −1.6 bps to 5.167%, 10Y −2.0 bps to 4.647%, Bull Flattener regime. MOVE compressed −0.87% to 85.32 — FIRST MOVE compression in three sessions. But the cleanest macro signal is what happened in Tuesday’s CASH SESSION: yields pushed to NEW war-cycle close-highs across the entire curve — 30Y closed 5.183%, 10Y 4.667%, 5Y 4.328%, 2Y 4.122%. Tuesday’s cash close was the worst yields print of the entire 83-day war. Today’s pre-market relief is tactical, not structural — yields are back to roughly Tuesday morning’s readings, not pre-Friday baseline. TGT crushed earnings BMO: net sales $25.4B (+6.7% y/y BEAT), EPS $1.71 vs $1.41-$1.47 cons MAJOR BEAT, same-store sales +5.6% (FIRST positive comp in five quarters!), traffic +4.4%, digital +8.9%, RAISED FY guide to ~4% (DOUBLED from 2%), EPS now expected near high end of $7.50-$8.50 range. TGT +3.11% pre-market. Combined with HD’s inline beat Tuesday (Rev $41.77B BEAT, EPS $3.43 BEAT, reaffirmed FY guide), the consumer-resilience thesis is structurally intact. UK CPI y/y 2.8% vs 3.0% cons (MISS, cooler) — combined with yesterday’s Canadian CPI all-four-measures-cooler, the global disinflation tail is real. ES +0.44% to 7,410.50, NQ +0.75%, RUT +0.68% LEADING — broad participation lift. The Mag 7 split is striking: 1 green / 6 red (AAPL +0.38% only green; NVDA −0.77% fourth consecutive decline pre-AMC, MSFT/META/TSLA/AMZN/GOOG all red). Despite Mag 7 down approximately −1.3% weighted, the ES is +0.44% — broad participation overwhelming narrow leadership unwind, a structurally bullish breadth configuration. Pre-market XLE +1.17% (fourth consecutive day of energy leadership), XLV +1.10%, XLU +0.91%, XLRE +0.43%, XLP +0.22% — five defensive sectors green. XLB Materials −2.35% (with XLB at Tuesday close STRNG 34 — NEW war-low). XLF Financials −1.24% giving back Monday’s bounce. The Tuesday 34 Macro close compressed SPY baseline from STRNG 67 to 62 — additional −5 STRNG (cumulative −17 STRNG across Fri-Mon-Tue, the LARGEST sustained 3-session SPY STRNG decline of the entire 83-day war series). USO Crude EXTENDED to STRNG 65 / MNTM 93 / RLTV 1.80 — energy thesis fully intact. XLE Energy TIED with XLK at #1 sector position at STRNG 66 / RLTV 1.05 (highest XLE RLTV of war). XLP Staples STRNG 65, XLV +6 to 55, XLU +5 to 40 — defensive bid extending. XLF gave back −7 STRNG to 47. XLB CRASHED to STRNG 34 (NEW war-low). CIBR Cybersecurity compressed −3 to STRNG 78 (still #1, RLTV 1.14 intact). XES Oil Equipment compressed −3 to STRNG 68, OIH −3 to 65, AMLP +2 to 64 (extending), XOP +3 to 60 (extending), CRAK Oil Refiners +2 to 54. Housing complex re-engaged at war-lows: XHB Homebuilders STRNG 33 (NEW war-low), CGW Water Treatment STRNG 33 (NEW war-low), ITB Home Construction STRNG 34. PBW Clean Energy compressed another −6 to STRNG 49. PPLT Platinum recovered to STRNG 41 / RLTV 0.86 — confirming Monday’s 12/0.09 was data anomaly. Today is THE INFLECTION: 2:00 PM FOMC Minutes (first Warsh-era; reveals Powell’s final 8-4 dissent map) + 4:30 PM NVDA earnings AMC (cons $78B / $1.77 EPS; bar substantially compressed by 4-session NVDA slide; Q2 guide vs $96.78B Wall Street model is structural read) + PANW AMC (cyber bellwether). VVIX +3.76% to 94.61 — tail-risk pricing bid into NVDA. COR1M +12.22% to 12.31 — re-correlation building. Watch ES 7,400 support, 30Y 5.10% (compression target) vs 5.20% (re-engagement), MOVE 80 (resolution) vs 88 (crisis), NVDA close, PANW guide. Pressure, not panic. Regime, not reaction. The relief sets up the inflection — today defines whether the post-Friday rout was one-week or one-cycle.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.