

Day 100 of Operation Epic Fury | Generated 9:15 AM ET
1. THE QUICK SCAN
Overnight Tape Summary: DAY 100 — THE UNWIND. THE AI/GROWTH COMPLEX CAPITULATES. DATA NOTE: THE DYRH HEADLINE LABELS THIS “RISK-ON” WITH GREEN INDEX FUTURES (ES +0.83%, NQ +1.57%), BUT THAT PRINT IS CONTRADICTED BY EVERY COMPONENT — THE DYRH ITSELF STATES “MAG 7 IS 0 GREEN / 7 RED.” THE INDEX PRINT IS STALE/ERRONEOUS; THE RELIABLE TAPE IS DECISIVELY RISK-OFF. VERIFICATION: MAG 7 CRASHING — NVDA -6.20% TO $205.10, TSLA -6.56%, META -5.51%, AMZN -3.06%, MSFT -2.66%, AAPL -1.25%, GOOG -0.95% (0/7 RED). SOXX -10.44% TO $539.77 (SEMIS CRASH DOUBLE-DIGITS); XLK -6.66% (WORST SECTOR). ONLY DEFENSIVES GREEN: XLP +1.71%, XLU +0.93%, XLRE +0.68%, XLV +0.61%, XLF +0.21%. FACTORS: ONLY SPLV +1.45% GREEN — MTUM -5.95%, SPHB -5.67%, VLUE -4.16%. THEMATICS ALL DEEPLY RED (ARKG -7.89%, ICLN -7.71%, BLOK -7.29%). VOL DETONATED: VIX1D +171.01% TO 28.70, VXN +31.22% TO 30.47, VVIX +19.00% TO 102.04, MOVE +5.67% TO 75.20. COR1M EXPLODED +110.13% TO 14.52 (FROM THE WAR-LOW OF 5.86 THREE SESSIONS AGO — THE DISPERSION REGIME FULLY COLLAPSED INTO A CORRELATED CRASH). SKEW 152.25. GOLD FAILED TO RALLY (-0.16% TO $4,358 — FORCED-LIQUIDATION TELL). BTC +4.97% TO $63,525 (LONE GREEN). ES LEVEL ~7,462 = CUM +8.44% (COMPRESSED HARD). FRIDAY RESOLVED BEARISH: SPY -21 TO STRNG 49 (LARGEST COLLAPSE OF THE WAR), QQQ -26, SMH BROKE -22 TO RLTV 1.36. HOT CPI WEDNESDAY (CONS 4.2% Y/Y). NO DATA TODAY.
A note on the data, because the discipline matters most on a day like this. The DYRH headline labels this session “RISK-ON” and shows green index futures (ES +0.83%, NQ +1.57%, RUT +1.48%) — but that print cannot be reconciled with anything else on the page, and the DYRH contradicts itself outright, stating two lines later that “Mag 7 is 0 GREEN / 7 RED.” A Nasdaq-100 cannot be +1.57% while its seven largest constituents fall 1-7% and the semis index drops 10%; the index-level print is stale or erroneous. Our process is built to catch exactly this: verify the headline against the underlying tape. The verification is unambiguous, and it is ugly. The Mag 7 are capitulating — NVDA −6.20% to $205.10, TSLA −6.56%, META −5.51%, AMZN −3.06%, MSFT −2.66% (0 green / 7 red). SOXX is −10.44% — semis crashing double-digits, the cap-weight AI leadership breaking violently. XLK Technology −6.66% is the worst sector by a wide margin. This is a risk-off unwind, not a risk-on session.
And it is a textbook de-risking in its internals. The only green on the screen is defensive: XLP Consumer Staples +1.71%, XLU Utilities +0.93%, XLRE Real Estate +0.68%, XLV Health-Care +0.61%, XLF Financials +0.21% — the classic flight to safety. Everything cyclical and growth is red (XLY −2.05%, XLB −1.92%, XLE −1.84%, XLC −1.27%, XLI −1.12%). At the factor level, SPLV Low-Vol (+1.45%) is the lone green factor, while the growth/momentum complex is in freefall: MTUM Momentum −5.95%, SPHB High-Beta −5.67%, VLUE −4.16%, with even equal-weight (RSP −1.42%) and small-caps (IJR −1.84%) red. The thematic tape is a sea of deep red — ARKG Genomic −7.89%, DRIV −7.85%, ICLN −7.71%, BLOK −7.29%, ARKQ −7.12%, ARKW −5.82%, FINX −5.16%, CIBR −4.41% — led by the SOXX −10.44% semi crash. The leadership that drove the entire melt-up (semis, the Mag 7, the AI/growth complex) is the epicenter of the unwind.
The volatility and correlation complex is where the regime change is unmistakable — and it confirms the risk-off read beyond any doubt. VIX1D exploded +171.01% to 28.70 (the one-day vol spiking from 10.59 Friday — a violent event-vol surge), VXN +31.22% to 30.47, VVIX +19.00% to 102.04, GVZ Gold-vol +21.03% to 28.89, and MOVE +5.67% to 75.20 (rates-vol re-expanding back above pre-war). And the single most important signal of the entire two-week arc: COR1M detonated +110.13% to 14.52 — more than doubling in a session, and a 2.5x explosion from the war-low of 5.86 set just three sessions ago (June 3). The record-low single-stock dispersion that powered the melt-up — the regime where stocks moved on idiosyncratic factors and the index ground higher on rotating leadership — has completely collapsed into a correlated crash. This is the regime shift the prior reports flagged as the risk (the COR1M re-coupling: 5.86 → 6.32 → 6.91 → 14.52); it has now fully materialized. When correlation explodes off a record low, the dispersion that masked the index’s fragility is gone, and everything moves together — down. SKEW rose to 152.25 (tail premium surging). A vol spike and correlation detonation of this magnitude occur only in a violent, broad-based selloff.
Friday’s cash close was the bearish resolution that set this up. The NFP came in firm, the hawkish repricing extended, and the market sold off violently: SPY collapsed −21 to STRNG 49 — the largest single-session baseline decline of the entire 100-day war. QQQ crashed −26 to 48 (Tech hardest hit), and critically, the AI/semi anchor finally broke — SMH −22 to RLTV 1.43 → 1.36 (the leadership that held through the entire de-risking week cracked decisively). The dollar surged (UUP +7 to STRNG 69, the new #1 asset), vol spiked (VXX +15), and crypto collapsed (IBIT to 19, ETHA to 16) — but the defensives held (XLV +2 to STRNG 64, the #1 sector; XLRE, XLF, XLP, XLU all green). Today’s pre-market is that selloff accelerating into a Day-100 capitulation. The macro backdrop is the driver: firm labor (Friday’s NFP, Wednesday’s ADP beat, Canada’s blowout), an oil shock that lifted inflation expectations, the 30Y holding at 5.00%, and — critically — a hot CPI expected Wednesday (consensus 4.2% y/y, up from 3.8%; Core 0.5% m/m). The Fed-cut path is collapsing, and the AI/growth complex is de-rating into it. Gold’s failure to rally (−0.16% to $4,358, falling even in the crash) is the forced-liquidation tell — everything sold for dollars. BTC +4.97% to $63,525 is the lone green (an oversold bounce, or part of the stale headline snapshot). The structural read on Day 100: the breakout has fully unwound, the dispersion regime has collapsed into a correlated crash, vol has exploded, and the only leadership is defensive — a capitulation into a hot-inflation week.
The Number That Matters: COR1M Detonated +110% To 14.52 — From The War-Low Of 5.86 Three Sessions Ago. The Dispersion Melt-Up Regime Has Fully Collapsed Into A Correlated Crash. The AI Complex Is Capitulating (SOXX -10.44%, NVDA -6.20%, Mag 7 0/7 Red, XLK -6.66%); Vol Exploded (VIX1D +171% To 28.70, VXN +31%, VVIX +19%). Only Defensives Are Green (XLP, XLU, XLRE, XLV, XLF; SPLV The Lone Green Factor). The DYRH’s Green Index Print Is A Data Error — The Tape Is Decisively Risk-Off. Friday Resolved Bearish: SPY -21 To STRNG 49, SMH Broke To RLTV 1.36. Gold Failed To Rally (Forced-Liquidation Tell). Premium Compressed To +8.44%. Hot CPI Wednesday (Cons 4.2% Y/Y).
This is the unwind, and it arrives on Day 100. The dispersion melt-up that defined the rally — semis and the Mag 7 carrying the index on rotating, idiosyncratic leadership while correlation sat at a record low — has reversed into its mirror image: a correlated crash, with the AI/growth leadership at the epicenter (SOXX −10.44%, the Mag 7 capitulating), vol exploding (VIX1D +171%), and correlation detonating (COR1M +110% to 14.52). The defensives are the only refuge. The discipline now is exactly what the tagline says: read the regime, do not react to the noise — and note that the DYRH’s own headline is the noise today (a green index print contradicted by every component). The macro is hostile (firm labor, a hot CPI Wednesday, the 30Y at 5.00%, the Fed-cut path collapsing), and the market is repricing the AI/growth complex hard. The questions now are whether the capitulation is a flush that finds a floor (the VIX1D spike to 28.70 and SKEW to 152 are capitulation-level readings that sometimes mark washouts) or the start of a deeper de-rating into the CPI — and whether the defensives can hold as the sole leadership. The premium has compressed to +8.44%, the dispersion regime is dead, and the tape is, for the first time in this stretch, decisively and correlatedly risk-off.
The Setup: DAY 100 — THE UNWIND. The AI/Growth Complex Capitulates (SOXX -10.44%, NVDA -6.20%, TSLA -6.56%, META -5.51%, Mag 7 0/7 Red, XLK -6.66%). Vol Explodes (VIX1D +171% To 28.70, VXN +31%, VVIX +19%, MOVE 75.20); COR1M Detonates +110% To 14.52 (The Dispersion Regime Collapses Into A Correlated Crash). Only Defensives Green (XLP / XLU / XLRE / XLV / XLF; SPLV The Lone Factor). NOTE: The DYRH’s Green Index Print Is A Data Error — Verify Against The Tape, Which Is Risk-Off. Gold Fails To Rally (-0.16%, Forced-Liquidation). BTC +4.97% (Lone Green). Friday: SPY -21 To 49, SMH Broke To 1.36. Premium +8.44%. Hot CPI Wednesday (Cons 4.2% Y/Y). No Data Today.
2. OVERNIGHT SESSION RECAP
A data-integrity note for this section: the DYRH’s index-futures block (Nikkei +1.85%, NQ +1.57%, ES +0.83%, RUT +1.48% — all green) is internally inconsistent with the crashing component tape (Mag 7 0/7 red, SOXX −10.44%) and the vol/correlation explosion (VIX1D +171%, COR1M +110%), and appears to be a stale or erroneous snapshot. The recap below leads with the reliable, internally-consistent cross-asset evidence — which is decisively risk-off.
Equities — The AI/Growth Complex Capitulates; Defensives The Only Bid
The reliable equity tape is a violent risk-off unwind. The Mag 7 are crashing — 0 green / 7 red: NVDA −6.20% to $205.10 (below $210, now near $205 — the semi leader capitulating), TSLA −6.56% to $391.00 (below $400), META −5.51% to $593.00 (below $600), AMZN −3.06% to $246.03, MSFT −2.66% to $416.67, AAPL −1.25% to $307.34, GOOG −0.95% to $365.76. SOXX Semiconductor −10.44% to $539.77 — a double-digit semi crash, the cap-weight AI leadership breaking violently. XLK Technology −6.66% is the worst sector. The cumulative ES level (7,462, below Friday’s 7,554 pre-market) reflects the continued decline; the DYRH’s “+0.83% / up” daily-change label is the data error, but the level itself is down. The index-level damage is concentrated in the megacap/Tech/semi complex — exactly the leadership that drove the melt-up — while the defensive sectors provide the only cushion. This is a leadership unwind: the names and themes that led the rally up are leading it down, and the dispersion that masked the concentration has collapsed (COR1M +110%).
Sectors — Only Defensives Green (XLP / XLU / XLRE / XLV / XLF); Tech -6.66%
The sector tape is a clean flight-to-safety. GREEN — the defensives only: XLP Consumer Staples +1.71% (leads), XLU Utilities +0.93%, XLRE Real Estate +0.68%, XLV Health-Care +0.61%, XLF Financials +0.21% — the bond-proxy/defensive complex catching the risk-off bid. RED — everything cyclical and growth: XLI Industrial −1.12%, XLC Communication Services −1.27%, XLE Energy −1.84%, XLB Materials −1.92%, XLY Consumer Discretionary −2.05%, and XLK Technology −6.66% (the epicenter). The configuration — staples/utilities/real-estate/health-care/financials green, Tech crashing, cyclicals red — is a textbook de-risking rotation into defensives. Friday’s cash close had already established this leadership (XLV the #1 sector at STRNG 64, with XLRE/XLF/XLP/XLU green through the selloff); today it intensifies, with the defensive bid the only thing holding. The defensives-as-sole-leadership is both the cushion (they’re absorbing flows) and the warning (it’s a defensive regime, not a broadening).
Factors — SPLV Low-Vol The Lone Green; Momentum / High-Beta Crash
The factor tape confirms the risk-off in the starkest terms: SPLV Low-Vol (+1.45%) is the only green factor on the board. Everything else is red, and the growth/risk factors are crashing: MTUM Momentum −5.95% (the momentum factor — which had been tilted toward the semi/Tech winners — now in freefall as those winners crash), SPHB High-Beta −5.67% (risk fully off), VLUE Value −4.16%, LRGF Multi-Factor −2.51%, IJH Mid-Cap −2.00%, QUAL Quality −1.93%, IJR Small-Cap −1.84%, RSP Equal-Weight −1.42%, VYM High-Dividend −1.35%, USMV Min-Vol −1.06%, DGRO −0.78%. The MTUM −5.95% / SPHB −5.67% crashes are the cleanest expression of the unwind — the high-momentum, high-beta names (the melt-up leaders) are being liquidated. Even the “defensive” factors (USMV, VYM, DGRO) are modestly red — only the purest low-vol (SPLV) holds green. The 1-of-12-green factor tape (vs the broad-green tape of Friday) is a complete reversal — the rotation has become a liquidation.
Thematics — A Sea Of Deep Red; SOXX -10.44% Leads The Crash
The thematic tape is uniformly, deeply red — the speculative-growth complex capitulating. SOXX Semiconductor −10.44% to $539.77 leads (the double-digit semi crash — the AI anchor breaking). The growth/innovation cohort is in freefall: ARKG Genomic −7.89%, DRIV Autonomous & EV −7.85%, ICLN Clean Energy −7.71%, BLOK −7.29%, ARKQ Autonomous −7.12%, ARKW Next-Gen Internet −5.82%, FINX FinTech −5.16%, CIBR Cybersecurity −4.41%. Even the relative “outperformers” are red: PAVE Infrastructure −1.61%, ITA Aerospace & Defense −0.92%. There is no green in the thematic tape. The complex that led the melt-up (semis, clean energy, cyber, autonomous, fintech, genomic) is the epicenter of the crash — a wholesale de-rating of speculative growth. SOXX at −10.44% is the headline: the semiconductor leadership that anchored the entire rally (SMH at a 1.45 RLTV record just five sessions ago) is being liquidated, with SMH having already broken to 1.36 Friday and the broad SOXX crashing double-digits today.
Rates & Commodities — Curve Twist (30Y Holds 5.00%); Gold Fails To Rally; BTC Bounces
The action is in equities and vol, not rates — the curve is relatively calm. Yield Curve: Steepener Twist — small moves, front falling slightly (2Y −0.6 bps to 4.139%, 5Y −0.9 bps to 4.262%), long end rising slightly (10Y −0.4 bps to 4.528%, 30Y +0.3 bps to 5.002%, holding 5.00%). The relative calm in rates (vs the equity crash) is notable — this is an equity/risk-asset de-rating, not a bond-market dislocation, though MOVE +5.67% to 75.20 (above pre-war) shows rates-vol re-expanding. Commodities: Gold −0.16% to $4,358.40 — failing to rally, even falling, in a violent equity crash (the DYRH’s flagged divergence, and a classic forced-liquidation / margin-driven tell: in a sharp deleveraging, everything is sold for dollars, and gold’s haven role is overridden — also consistent with the rising real yields, 30Y at 5.00%). Copper +1.59% (a divergent bid), Platinum −1.41%, Palladium −3.21%. Oil firm: WTI +1.48% to $91.88, Brent +1.91% to $94.87 (crude holding/bouncing — the one cyclical bid). BTC +4.97% to $63,525 — the lone clear green (bouncing off Friday’s $62K oversold low — a divergence from the equity crash, possibly an oversold bounce, possibly part of the stale headline snapshot; either way, crypto is not confirming the equity de-risk this morning). The cross-asset signature — equity/growth crashing, vol exploding, defensives + dollar bid, gold failing to rally (forced liquidation), rates calm — is a leveraged-growth unwind, not a macro-systemic break.
3. THE PRIOR DAY’S REGIME
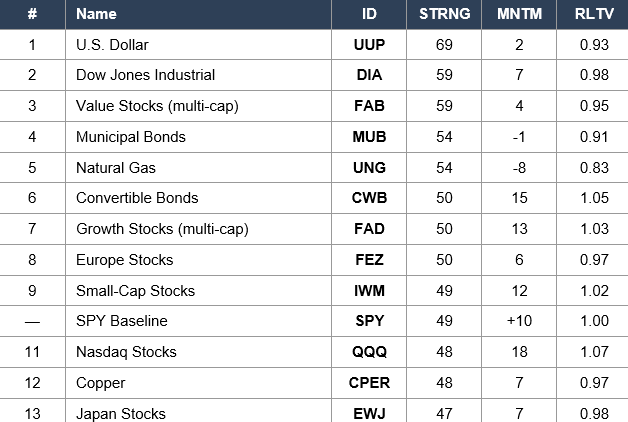
34 Macro Price, Strength & Momentum Rankings — Daily Close, Friday June 5. SPY Baseline: STRNG 49 | MNTM +10 | RLTV 1.00. SPY -21 STRNG — The Largest Single-Session Collapse Of The War; The NFP Resolved Bearish. The AI Anchor (SMH) Broke; Defensives Held.
Asset Classes — Dollar #1 (+7); Value/Dow Held; Growth/International Collapsed
Asset Classes — Vol Spiked (VXX +15); Metals & Crypto Collapsed
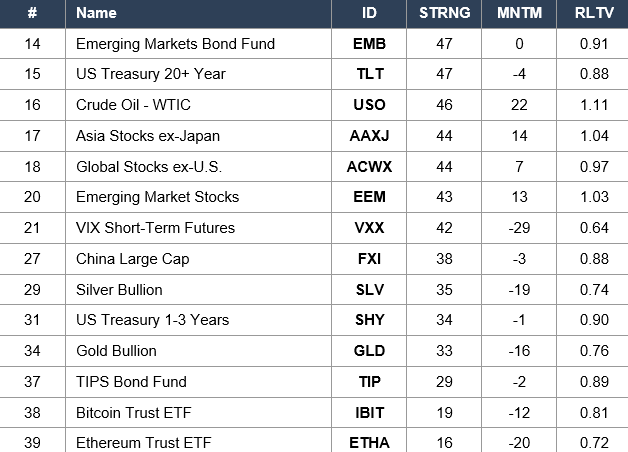
Regime signal: FRIDAY DELIVERED THE BEARISH NFP RESOLUTION — THE LARGEST SINGLE-SESSION BASELINE COLLAPSE OF THE WAR. SPY baseline CRATERED −21 to STRNG 49 (from Thursday’s 70 — the broad market strength collapsed to the neutral line, the largest one-day decline of the 100-day war). The firm jobs read extended the hawkish repricing, and the Tech/growth complex was liquidated: QQQ COLLAPSED −26 to STRNG 48 / RLTV 1.07 (the hardest-hit major — the megacap/Tech unwind), CWB Convertibles −18 to 50, FAD Growth −17 to STRNG 50, ACWX Global −17 to 44. THE INTERNATIONAL/EM COMPLEX COLLAPSED: AAXJ Asia −19 to 44, EWJ Japan −19 to 47, EEM EM −18 to 43, EPP Pacific −13 to 34. IWM Small-Cap −13 to STRNG 49 (the small-cap recovery reversed, though RLTV 1.02 held). The reflation/metals trade collapsed: CPER Copper −10 to 48, GLD Gold −9 to STRNG 33, SLV Silver −10 to 35. The risk-off bid concentrated in the dollar and vol: UUP Dollar SURGED +7 to STRNG 69 (the new #1 asset), VXX VIX Futures SPIKED +15 to STRNG 42. Even the bond complex fell (a broad de-risking, not a flight to bonds): EMB −8, TLT −5, LQD −7, HYG −6, IEF −7, PFF −9, SHY −7. DIA Dow −9 to STRNG 59 and FAB Value −2 to 59 HELD UP BEST among equities (the value relative outperformance). CRYPTO COLLAPSED TO THE BOTTOM: IBIT Bitcoin −3 to STRNG 19, ETHA Ethereum −6 to STRNG 16 (the speculative-risk capitulation). The Friday configuration: a violent, broad risk-off selloff with the dollar and vol the only bids, growth/international/metals/crypto collapsing, and value/Dow holding up relatively — the bearish NFP resolution that set up today’s Day-100 unwind.
Sector ETFs (XLV #1 At 64; Defensives Held; XLK Collapsed -20 To RLTV 1.20)
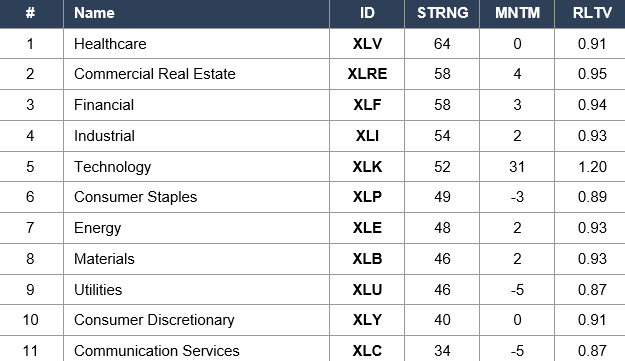
Regime signal: FRIDAY’S SECTOR CLOSE CONFIRMED THE DEFENSIVE ROTATION HELD THROUGH THE COLLAPSE — AND TECH BROKE. XLV Health-Care HELD/ROSE +2 to STRNG 64 — the clear #1 sector (the defensive-growth leadership intact through the selloff, now 15 points above the SPY baseline). XLRE Real Estate +3 to STRNG 58, XLF Financials +1 to STRNG 58 (the rate-sensitives/financials held — the value/defensive rotation persisting even in the broad selloff). XLP Consumer Staples SURGED +9 to STRNG 49, XLU Utilities +4 to STRNG 46 (the defensives bid — the flight to safety). But XLK Technology COLLAPSED −20 to STRNG 52 / RLTV 1.24 → 1.20 (the leadership unwinding hard — Tech’s relative-strength premium compressing as the megacaps broke). The cyclicals fell: XLI Industrial −6 to 54, XLE Energy −6 to 48, XLB Materials −9 to 46, XLY Consumer Discretionary −7 to STRNG 40. XLC Communication Services −5 to STRNG 34 (the weakest sector — the GOOG/META drag). The Friday configuration: the defensives (health-care, real estate, financials, staples, utilities) held or rose while Tech collapsed and cyclicals fell — the value/defensive rotation surviving the selloff intact, confirming the decisive leadership shift from Tech/growth to defensives that began Wednesday. The defensive leadership is the structure carrying into today’s unwind.
Industry ETFs — Leaders (Defensives Led: IYT / MSOS / PPH / KIE; SMH Broke -22 To 1.36)
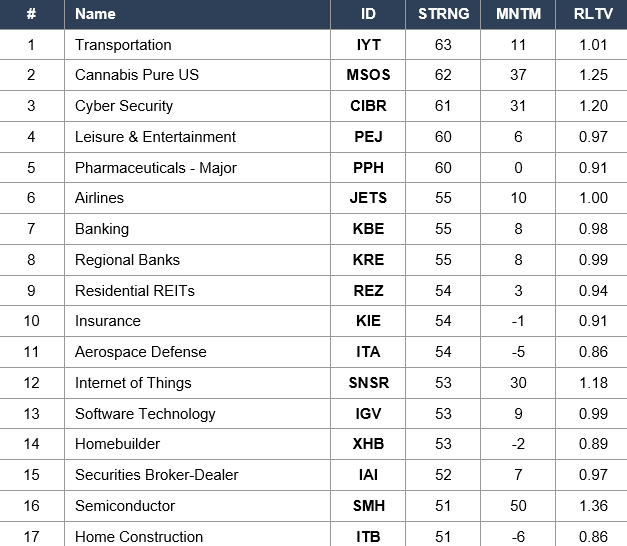
Industry ETFs — Semis/Clean Energy/Cyclicals Collapsed (SMH/QCLN/PBW/COPX/OIH)
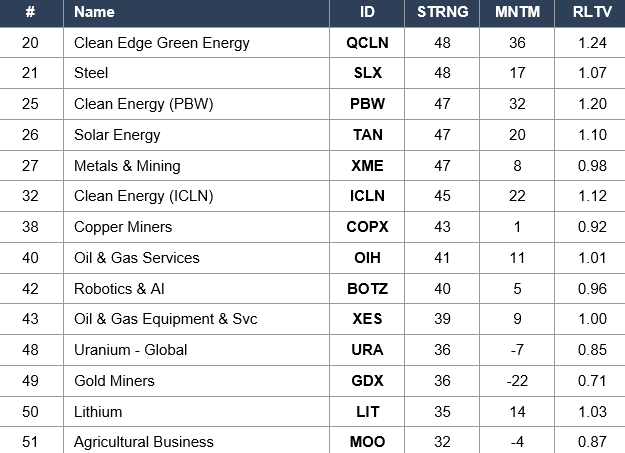
Regime signal: FRIDAY’S INDUSTRY CLOSE SAW THE AI ANCHOR BREAK AND THE GROWTH COMPLEX COLLAPSE, WHILE DEFENSIVES LED. SMH Semiconductor BROKE −22 to STRNG 51 / RLTV 1.43 → 1.36 — the largest single-industry STRNG decline of the day, and the decisive crack in the AI leadership that had held all week (SMH still held the highest RLTV at 1.36, but the break from the 1.45 record was severe — and today’s SOXX −10.44% extends it). The CLEAN-ENERGY COMPLEX COLLAPSED: QCLN −19 to STRNG 48 / RLTV 1.24, PBW −19 to STRNG 47 / RLTV 1.20, ICLN −17 to STRNG 45 / RLTV 1.12, TAN −16 to STRNG 47 / RLTV 1.10, SLX Steel −16 to STRNG 48 / RLTV 1.07, SNSR IoT −19 to STRNG 53 / RLTV 1.18. The CYCLICAL/ENERGY/SEMI-ADJACENT complex collapsed: COPX Copper Miners −15 to 43, OIH Oil Services −15 to 41, XME Metals & Mining −14 to 47, BOTZ Robotics −14 to 40, XES Oil Equipment −12 to 39, IYZ Telecom −12 to 45, SOCL Social Media −13 to 47, FDN Internet −13 to 50, CIBR Cyber −11 to STRNG 61 / RLTV 1.20. But the DEFENSIVES LED: IYT Transport +1 to STRNG 63 (the #1 industry), MSOS Cannabis +5 to 62 / RLTV 1.25, PPH Pharma +2 to STRNG 60, KIE Insurance +12 to STRNG 54, REZ Residential REITs +6 to 54, KBE Banking +1 to 55, KRE Regional Banks held 55 (the health-care/financials/insurance/transport defensives outperforming). The Friday configuration: the AI/semi anchor broke (SMH −22), the clean-energy and growth complex collapsed (−16 to −19), but the defensives (transport, pharma, insurance, banks, REITs) held or rose — the leadership decisively rotated from the broken AI/growth core to defensives, the structure that frames today’s Day-100 unwind.
4. MORNING DATA REACTION
No Data Today (Monday); A Hot-Inflation Week Ahead — CPI Wednesday, PPI Thursday
No Releases Today — The Unwind Is Positioning, Not Data
There are no scheduled US economic releases today — the Day-100 unwind is a positioning/momentum/de-risking event, not a data reaction. The crash is the delayed, compounding reaction to Friday’s firm NFP (which extended the hawkish repricing), the oil shock that lifted inflation expectations, the 30Y holding 5.00%, and — most importantly — the market positioning ahead of a hot CPI on Wednesday. With no data to anchor the tape today, the move is being driven by the unwind dynamics themselves: the correlation explosion (COR1M +110%), the momentum/high-beta liquidation (MTUM −5.95%, SPHB −5.67%), the vol spike (VIX1D +171%), and the forced deleveraging (gold failing to rally). Days like this — a violent, data-less de-risking with vol exploding and correlation detonating — are positioning washouts, and the absence of a data catalyst today means the next directional input is Wednesday’s CPI.
CPI Wednesday (Cons 4.2% Y/Y, Core 0.5% M/M) — The Hot-Inflation Catalyst
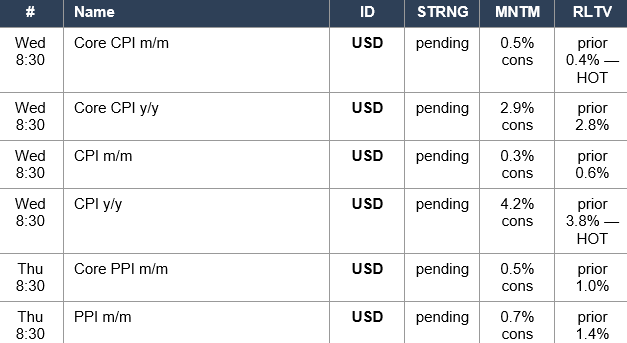
Wednesday’s CPI is the week’s decisive catalyst, and the consensus is hot: headline CPI 4.2% y/y (up from 3.8% prior — a sharp re-acceleration), CPI 0.3% m/m, Core CPI 0.5% m/m (up from 0.4%), Core CPI 2.9% y/y. A 4.2% headline y/y print would confirm the inflation re-acceleration the oil shock signaled — and would validate the hawkish repricing (the 30Y at 5.00%, the Fed-cut path collapsing) that drove Friday’s selloff and today’s unwind. The risk is asymmetric and hostile: an in-line or hot CPI (≥4.2% y/y, ≥0.5% Core m/m) confirms the no-cut/higher-for-longer regime and could extend the de-rating; a soft CPI (a downside surprise) would be the relief the oversold tape needs to find a floor. With the market already capitulating (VIX1D 28.70, COR1M 14.52) ahead of the print, Wednesday’s CPI lands into a fragile, de-risked tape — it will either confirm the unwind (hot) or trigger a violent oversold bounce (soft). PPI follows Thursday (Core 0.5% m/m, PPI 0.7% m/m). The hot-inflation week is the macro gauntlet the market is de-risking into.
The Macro Backdrop — Firm Labor + Hot Inflation = The Fed-Cut Path Collapsing
The macro regime has turned decisively hostile to the AI/growth melt-up. The labor signals are firm (Friday’s NFP, Wednesday’s ADP beat at 122K, Canada’s +87.8K blowout), the inflation signals are hot (the oil shock, the 4.2% CPI consensus Wednesday), and the rates complex reflects it (the 30Y at 5.00%, MOVE re-expanding above pre-war). This is the collapse of the rate-cut thesis that underwrote the equity multiple expansion — and the AI/growth complex (the longest-duration, highest-multiple part of the market) is de-rating hardest into it (SOXX −10.44%, the Mag 7 capitulating). The June 16-17 Warsh FOMC now lands into a firm-labor / hot-inflation backdrop where a cut is increasingly hard to justify. The structural macro read: higher-for-longer is reasserting, and the most-extended part of the market (the AI/semi/growth leadership) is paying the price — exactly the de-rating a hot-inflation, firm-labor regime produces.
5. THE DYRH READ
Data Integrity: The DYRH Index Print Is Erroneous — Verify Against The Tape
Before the rates read, the data-integrity flag: today’s DYRH labels the session “RISK-ON” with green index futures (ES +0.83%, NQ +1.57%, RUT +1.48%) and boilerplate narrative (”clear strength,” “small-cap leadership confirms genuine risk appetite”). This is internally contradicted — the same report states “Mag 7 is 0 GREEN / 7 RED,” shows SOXX −10.44%, every factor red but low-vol, every thematic deeply red, and a vol/correlation explosion (VIX1D +171%, COR1M +110%). A Nasdaq-100 mathematically cannot be +1.57% with those constituents; the index-futures block and the “risk-on” label are stale or erroneous (the boilerplate line claiming semis are “broadening” while SOXX crashes 10% confirms the narrative layer is broken today). Per our process — never trust the DYRH headline alone; verify against the granular cross-asset tape — the reliable signal is the component, volatility, and correlation data, which is decisively and violently risk-off. The index level (7,462, below Friday’s 7,554) is consistent with the selloff; the “+0.83% / up” daily-change label is the error. We report the verified regime: a risk-off unwind.
Yield Curve Regime: Steepener Twist — Rates Calm Relative To The Equity Crash
The curve is a Steepener Twist — small, mixed moves, notably calm relative to the equity crash: 2Y −0.6 bps to 4.139%, 5Y −0.9 bps to 4.262% (front falling slightly — modest cut-probability), 10Y −0.4 bps to 4.528%, 30Y +0.3 bps to 5.002% (long end rising slightly — term-premium/inflation, holding 5.00%). The twist (front down, long up) reflects a market pricing modest near-term easing against longer-run inflation/term-premium concerns. The key observation is the relative calm: while equities crash and equity-vol explodes (VIX1D +171%), the rates curve is barely moving — this is an equity/risk-asset de-rating, not a bond-market dislocation. The 30Y holding at 5.00% (the disinflation milestone failing) is the persistent hawkish anchor, but the absence of a sharp rates move today means the equity unwind is a positioning/multiple event (the AI/growth de-rating), not a rates-driven cascade. This is the ninth distinct curve reading in nine sessions — the curve’s instability continuing, but today as a sideshow to the equity crash.
MOVE Index: 75.20 (+5.67%) — Re-Expanding Above Pre-War; Rates-Vol Returns
MOVE rose +5.67% to 75.1985 — now +1.99 above the pre-war baseline of 73.21, re-expanding back above pre-war after Friday’s brief dip below (71.16). The rates-vol “all-clear” of Friday has reversed — the bond market is re-pricing elevated tail risk into the hot-CPI week and the equity de-risk. MOVE above pre-war is the gravity-weight on equity multiples the DYRH flags, and its re-expansion (alongside the equity-vol explosion) confirms the broad volatility regime has shifted back to elevated. From the war high of 115.02, MOVE has normalized 39.82 points, but the +1.99 above pre-war reading — combined with VIX1D at 28.70, VXN at 30.47, and VVIX at 102 — is a market where volatility is broadly bid across rates and equities. The MOVE re-expansion is the rates-side confirmation of the risk-off: the brief Friday compression (the false “all-clear”) has given way to renewed rates-vol as the inflation/hawkish backdrop and the equity crash drive tail-hedging. Watch whether MOVE accelerates into the CPI (a hot print would push it higher) or stabilizes.
S&P 500: ES ~7,462 — Premium Compressed To +8.44%; The Unwind Deepens
The ES level (7,462, the DYRH’s daily-change sign notwithstanding) is below Friday’s 7,554 pre-market — the cumulative ES premium vs pre-war 6,881.62 has compressed to +8.44%, down from +9.77% Friday and the +10.63% war-high extension of June 1. The breakout extension has now fully unwound — the premium has given back roughly two-thirds of the move from the pre-war level to the peak. Cumulative ES recovery from the Tuesday May 19 low (7,378) to today (7,462): +84 points / +1.14% — the bulk of the post-low recovery has been retraced. The NQ-led damage is far worse (NQ at 29,481 per the DYRH level — testing below 29,500, with SOXX −10.44% and the Mag 7 crashing). Technical levels: ES support at 7,400 (Friday’s reference), 7,378 (the May 19 war-low — the critical level), 7,300; resistance at 7,500, 7,554, 7,604. The 7,378 May 19 low is now the line that matters — a hold there keeps the broader uptrend structure intact (a deep but contained correction); a break below would signal the breakout has fully failed and a new downtrend is engaging. With the premium at +8.44%, the dispersion regime collapsed, and vol exploding, the market is at a genuine inflection — the CPI Wednesday and the 7,378 level will define whether this is a washout or a breakdown.
Key Levels & Cumulative War Moves
Volatility & Breadth — The Capitulation Signature: VIX1D 28.70, COR1M 14.52
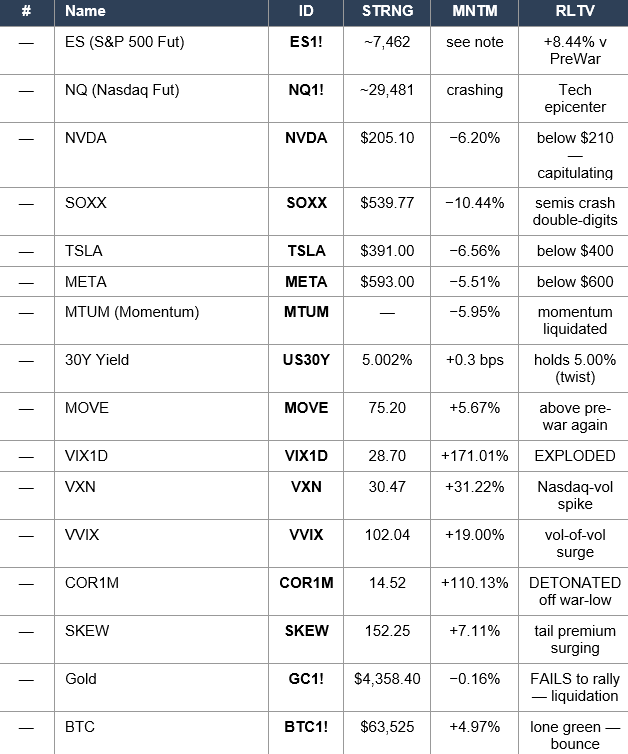
The volatility and correlation complex is the story, and it is a capitulation signature. VIX1D exploded +171.01% to 28.70 — the one-day vol surging from 10.59 Friday, a violent event-vol spike (VIX1D near 29 is a panic-level reading, the kind seen in sharp liquidations). VXN Nasdaq-vol +31.22% to 30.47 (Tech-vol spiking above 30 — the epicenter), VVIX +19.00% to 102.04 (vol-of-vol surging above 100 — demand for vol protection itself), GVZ Gold-vol +21.03% to 28.89, MOVE +5.67% to 75.20 (rates-vol re-expanding). Curiously, the headline VIX shows −12.42% to 18.83 in the DYRH — almost certainly another stale/erroneous print (a −12% VIX alongside VIX1D +171% and VXN +31% is incoherent; the VIX1D/VXN/VVIX explosion is the reliable tell). The defining signal: COR1M detonated +110.13% to 14.52 — more than doubling in a session, a 2.5x explosion from the war-low of 5.86 set June 3. COR3M +38.51% to 12.23, COR6M +22.82% to 13.40. The record-low dispersion that powered the melt-up has fully collapsed into a correlated crash — the regime shift the prior reports tracked (5.86 → 6.32 → 6.91 → 14.52) has now violently completed. SKEW +7.11% to 152.25 (tail premium surging — crash protection bid). The configuration — VIX1D/VXN/VVIX exploding + COR1M detonating + SKEW surging + MOVE re-expanding — is an unambiguous, broad-based capitulation: volatility bid everywhere, correlation at a multi-week high, and the dispersion regime dead. These are washout-level readings; the question is whether they mark a flush bottom (capitulation often does) or the early innings of a deeper de-rating into the CPI.
6. THE GAME PLAN
Today: DAY 100 — THE UNWIND. The AI/growth complex capitulates: SOXX −10.44%, NVDA −6.20%, TSLA −6.56%, META −5.51%, Mag 7 0/7 red, XLK −6.66%. Vol explodes (VIX1D +171% to 28.70, VXN +31%, VVIX +19%, MOVE 75.20); COR1M detonates +110% to 14.52 (the dispersion regime collapses into a correlated crash). Only defensives green (XLP +1.71%, XLU, XLRE, XLV, XLF; SPLV the lone factor). NOTE: the DYRH’s green index print (ES +0.83%) is a data error — the verified tape is risk-off. Gold fails to rally (−0.16%, forced-liquidation); BTC +4.97% (lone green bounce). Friday: SPY −21 to STRNG 49, QQQ −26, SMH broke −22 to RLTV 1.36; defensives held (XLV #1 at 64). Premium compressed to +8.44%. Hot CPI Wednesday (cons 4.2% y/y). No data today.
The Bull Case
This is a capitulation that may mark a washout, not the start of a bear market. The volatility readings are extreme — VIX1D at 28.70 (+171%), VXN above 30, VVIX above 102, SKEW at 152 — and capitulation-level vol spikes frequently mark short-term bottoms (the point of maximum fear and forced selling). The correlation explosion (COR1M +110% to 14.52) is the signature of indiscriminate liquidation, not fundamental repricing — when everything is sold together regardless of merit, the selling is often near exhaustion. Gold’s failure to rally and the broad bond selloff Friday confirm forced deleveraging (margin-driven), which tends to be self-limiting. The structural uptrend is not yet broken: ES at +8.44% above pre-war is a correction of an extended move, not a collapse, and the 7,378 May 19 low has not been tested. The defensive rotation (health-care, financials, real estate, staples holding — XLV the #1 sector) shows capital rotating within equities, not fleeing them entirely. And BTC’s +4.97% bounce hints at risk-appetite stabilizing at the margin. A soft CPI Wednesday (a downside inflation surprise) would be the catalyst for a violent oversold bounce. For the patient: the washout is creating value in the names liquidated indiscriminately. Watch 7,378 (the line that must hold) and the CPI.
The Bear Case
The breakout has failed, the leadership has broken, and the macro is hostile — this may be the early innings of a deeper de-rating. The AI/growth complex that drove the entire melt-up is capitulating (SOXX −10.44%, NVDA −6.20%, the Mag 7 crashing, SMH having broken from its 1.45 record to 1.36) — when the leadership breaks this violently, the move is rarely a one-day event. The premium has round-tripped from +10.63% to +8.44%, and the dispersion that masked the index’s concentration has collapsed (COR1M +110%) — the index can no longer grind higher on rotating leadership because everything now moves together, down. The macro is the driver and it is worsening: firm labor (NFP, ADP, Canada), a hot CPI expected Wednesday (4.2% y/y), the 30Y at 5.00%, MOVE re-expanding, and the Fed-cut path collapsing into the June 16-17 Warsh FOMC. Higher-for-longer is reasserting, and the longest-duration, highest-multiple part of the market (AI/growth) has the most to lose. A hot CPI Wednesday (in-line at 4.2% or above) would confirm the regime and extend the de-rating. The defensives-only leadership is a risk-off regime, not a broadening. Watch ES 7,378 — a break engages 7,300, 7,200, and signals the breakout has fully failed. The capitulation could deepen before it bottoms.
Regime: DAY 100 — THE UNWIND. The Dispersion Melt-Up Has Collapsed Into A Correlated Crash (COR1M +110% To 14.52). The AI/Growth Leadership Capitulates (SOXX -10.44%, NVDA -6.20%, Mag 7 0/7 Red, XLK -6.66%); Vol Explodes (VIX1D +171% To 28.70). Only Defensives Hold (XLV / XLF / XLRE / XLP / XLU; SPLV The Lone Factor). The DYRH’s Green Index Print Is A Data Error — The Tape Is Risk-Off. Friday Resolved Bearish (SPY -21 To 49, SMH Broke To 1.36). Watch ES 7,378 (The Line That Must Hold), CPI Wednesday (Cons 4.2% Y/Y — Hot = De-Rating Extends, Soft = Oversold Bounce), VIX1D 28.70 (Washout Or More?), COR1M (Capitulation Exhaustion?), The Defensives (Holding Or Cracking?).
Watch List
ES 7,378 — The May 19 War-Low; The Line That Defines Washout vs Breakdown
The single most important level now. ES at ~7,462 sits just above the 7,378 May 19 war-low (the intraday low of the entire post-crash recovery). A hold at/above 7,378 keeps the broader uptrend structure intact — framing today as a deep but contained correction of an extended move (a washout). A decisive break below 7,378 would signal the breakout has fully failed and a new downtrend is engaging — opening 7,300, 7,200, and a re-test of lower levels. With the premium at +8.44% and the dispersion regime collapsed, 7,378 is the technical line that separates a capitulation-bottom thesis from a breakdown thesis. Watch it through the CPI: a hold + a soft CPI = the oversold-bounce setup; a break + a hot CPI = the de-rating extends. This is the level to anchor risk around.
CPI Wednesday (Cons 4.2% Y/Y, Core 0.5% M/M) — The Decisive Macro Catalyst
Wednesday’s CPI is the catalyst that resolves the unwind. The consensus is hot: 4.2% headline y/y (up from 3.8%), 0.5% Core m/m (up from 0.4%). The asymmetry into a capitulated, oversold tape: a soft print (downside inflation surprise) would be the relief that triggers a violent oversold bounce (the VIX1D 28.70 / COR1M 14.52 readings are primed for a sharp reversal on good news); an in-line or hot print (≥4.2% y/y) confirms the inflation re-acceleration, validates the hawkish repricing, and extends the de-rating. With the market having already de-risked hard ahead of the print, the CPI lands into maximum fragility — it will either mark the washout bottom (soft) or deepen the unwind (hot). PPI follows Thursday. Position for a high-volatility two-way event Wednesday; the CPI is the macro hinge of the week.
Vol & Correlation — VIX1D 28.70 / COR1M 14.52; Capitulation Or More?
The vol/correlation complex is at capitulation-level readings, and its trajectory will signal the bottom. VIX1D at 28.70 (+171%) and COR1M at 14.52 (+110%) are washout-grade — the kind of fear and forced-correlation that often mark short-term bottoms. Watch for the tells of exhaustion: VIX1D peaking and rolling over (the panic passing), COR1M stabilizing (the indiscriminate selling abating), and SKEW (152) easing (tail-hedge demand satisfied). A peak-and-reverse in VIX1D would be the classic washout signal — particularly if it coincides with a soft CPI. Conversely, if VIX1D stays elevated/rises and COR1M climbs further through the CPI, the de-rating is not done — the correlated selling continues. The vol complex is the real-time barometer of whether this is a flush (reversing) or a regime (deepening). These are the most important secondary signals after the 7,378 level and the CPI.
The Defensives — XLV / XLF / XLRE / XLP / XLU; The Only Leadership; Holding Or Cracking?
The defensives are the only leadership, and their behavior defines the character of the move. Health-care (XLV, the #1 sector at STRNG 64), financials (XLF), real estate (XLRE), staples (XLP), and utilities (XLU) held green today and through Friday’s collapse — the flight-to-safety rotation absorbing flows. As long as the defensives hold, capital is rotating within equities (a risk-off regime, but not a wholesale exit) — and a defensive-led tape can stabilize the index even as Tech de-rates. The warning would be the defensives cracking (XLV/XLF rolling over) — that would signal a broad-based liquidation where even the safe havens are sold (the deepest risk-off). Watch whether the defensive leadership holds (a rotational, contained de-risk) or breaks (a wholesale liquidation). Their resilience is the bull’s evidence that this is a rotation/washout, not a systemic break; their failure would confirm the bear’s deeper-de-rating thesis.
Semis & The Mag 7 — SOXX -10.44% / NVDA -6.20%; The Broken Leadership
The AI/semi/Mag-7 complex is the epicenter of the unwind, and its stabilization is required for any bottom. SOXX −10.44% (a double-digit semi crash), NVDA −6.20% (below $210), the Mag 7 0/7 red — the leadership that drove the entire melt-up (SMH at a 1.45 RLTV record five sessions ago) is being liquidated. Watch for stabilization: NVDA holding $200 (a key psychological/technical level), SOXX finding a floor (the $540 area), and SMH’s RLTV (1.36 Friday) holding rather than collapsing further. The AI/growth complex is the highest-beta, longest-duration part of the market and will move most violently in both directions — its capitulation today is the unwind’s core, and its stabilization (or continued breakdown) will lead the index. A washout bottom requires the semis/Mag-7 to stop falling; continued semi weakness (SOXX below $540, NVDA below $200) would signal the de-rating has further to run. The leadership that led up is leading down — watch it for the turn.
Morning check: Day 100. THE UNWIND — the AI/growth complex capitulates. A data note first: the DYRH headline labels this session “RISK-ON” with green index futures (ES +0.83%, NQ +1.57%, RUT +1.48%), but that print is contradicted by every component — the DYRH itself states “Mag 7 is 0 GREEN / 7 RED” — and is stale/erroneous; our process verifies against the tape, which is decisively risk-off. The verification: the Mag 7 are crashing 0/7 red — NVDA −6.20% to $205.10 (below $210), TSLA −6.56% to $391.00 (below $400), META −5.51% to $593.00 (below $600), AMZN −3.06% to $246.03, MSFT −2.66% to $416.67, AAPL −1.25% to $307.34, GOOG −0.95% to $365.76. SOXX Semiconductor −10.44% to $539.77 (a double-digit semi crash — the AI anchor capitulating); XLK Technology −6.66% (the worst sector by far). Only defensives green: XLP Consumer Staples +1.71%, XLU Utilities +0.93%, XLRE Real Estate +0.68%, XLV Health-Care +0.61%, XLF Financials +0.21%; everything cyclical/growth red (XLY −2.05%, XLB −1.92%, XLE −1.84%, XLC −1.27%, XLI −1.12%). Factors: only SPLV Low-Vol +1.45% green — MTUM Momentum −5.95%, SPHB High-Beta −5.67%, VLUE −4.16%, LRGF −2.51%, IJH −2.00%, QUAL −1.93%, IJR −1.84%, RSP −1.42%, VYM −1.35%, USMV −1.06%, DGRO −0.78%. Thematics all deeply red: SOXX −10.44%, ARKG Genomic −7.89%, DRIV −7.85%, ICLN −7.71%, BLOK −7.29%, ARKQ −7.12%, ARKW −5.82%, FINX −5.16%, CIBR −4.41%, PAVE −1.61%, ITA −0.92%. The volatility/correlation complex DETONATED: VIX1D +171.01% to 28.70, VXN +31.22% to 30.47, VVIX +19.00% to 102.04, GVZ +21.03% to 28.89, MOVE +5.67% to 75.1985 (above pre-war); the headline VIX print (−12.42% to 18.83) is itself stale/incoherent against the VIX1D/VXN explosion. Most importantly: COR1M EXPLODED +110.13% to 14.52 — more than doubling in a session, a 2.5x surge from the war-low of 5.86 set June 3 (the dispersion melt-up regime — 5.86 → 6.32 → 6.91 → 14.52 — has fully collapsed into a correlated crash); COR3M +38.51% to 12.23. SKEW +7.11% to 152.25 (tail premium surging). The curve is a Steepener Twist — calm relative to the equity crash (2Y −0.6 bps to 4.139%, 30Y +0.3 bps to 5.002%, holding 5.00%); this is an equity/risk-asset de-rating, not a bond dislocation. Gold −0.16% to $4,358.40 — failing to rally, even falling, in the crash (the forced-liquidation / real-yield tell; everything sold for dollars). BTC +4.97% to $63,525 (the lone clear green — an oversold bounce off Friday’s $62K, or part of the stale headline snapshot). The ES level (7,462, below Friday’s 7,554) puts the cumulative premium at +8.44% vs pre-war 6,881.62 — compressed hard from the +10.63% June-1 peak (the breakout extension fully unwound). Friday’s cash close was the bearish NFP resolution: SPY CRATERED −21 to STRNG 49 (the largest single-session collapse of the 100-day war), QQQ −26 to 48, and the AI anchor broke — SMH −22 to RLTV 1.43 → 1.36. The dollar surged (UUP +7 to STRNG 69, #1 asset), VXX spiked +15 to 42, even bonds fell (TLT −5, LQD −7, HYG −6), and crypto collapsed (IBIT to 19, ETHA to 16) — but defensives held (XLV +2 to STRNG 64, #1 sector; XLRE +3, XLF +1, XLP +9, XLU +4; IYT/MSOS/PPH/KIE/KBE/KRE leading industries). Today: NO US data (the unwind is positioning, not data). This week: CPI Wednesday (cons 4.2% y/y — up from 3.8% — HOT; Core 0.5% m/m), PPI Thursday (Core 0.5%, PPI 0.7%) — into the June 16-17 Warsh FOMC. The narrative arc: RESOLUTION → EXTENSION → ACCELERATION → CONSOLIDATION → CONFIRMATION → NARROWING → HANDOFF → OIL SHOCK → DE-RISKING INTO THE PRINT → THE ROTATION HARDENS → and now, on Day 100, THE UNWIND. The dispersion melt-up that defined the rally — semis and the Mag 7 carrying the index on rotating, idiosyncratic leadership while correlation sat at a record low — has reversed into its mirror image: a correlated crash, with the AI/growth leadership at the epicenter (SOXX −10.44%, the Mag 7 capitulating), vol exploding (VIX1D +171%), and correlation detonating (COR1M +110% to 14.52). The defensives are the only refuge. The macro is hostile (firm labor, a hot CPI Wednesday, the 30Y at 5.00%, the Fed-cut path collapsing). The questions: is the capitulation a flush that finds a floor (VIX1D 28.70 and SKEW 152 are washout-grade), or the start of a deeper de-rating into the CPI? Watch ES 7,378 (the May 19 war-low — the line that must hold to keep the uptrend intact), CPI Wednesday (cons 4.2% y/y — hot = de-rating extends, soft = oversold bounce), VIX1D 28.70 (a peak-and-reverse would signal the washout), COR1M 14.52 (stabilization = exhaustion; further climb = more to come), the defensives (XLV/XLF holding = rotational de-risk; cracking = wholesale liquidation), and the semis/Mag-7 (SOXX/NVDA stabilizing is required for any bottom). Pressure, not panic. Regime, not reaction. On Day 100, the melt-up’s engine has reversed: the dispersion regime is dead, correlation has detonated, the AI leadership is capitulating, and volatility has exploded — but the discipline holds. Read the regime (a correlated risk-off unwind into a hot-inflation week), do not react to the noise (including the DYRH’s own erroneous green headline). The 7,378 level and Wednesday’s CPI will define whether this is a washout or a breakdown.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.