

1. THE QUICK SCAN
Overnight Tape Summary: THE SEMICONDUCTOR HANDOFF. THE BATON PASSES — NVDA ROARS BACK. ES -0.19% TO 7,598.75 (OFF MONDAY’S NEW HIGH; CUM +10.42% VS PRE-WAR). NQ -0.08% TO 30,541.25 (FLAT). RUT +0.03% GREEN (SMALL-CAPS OUTPERFORM). NVDA +6.26% TO $224.36 — MASSIVE REVERSAL (FAILED-BOUNCE FLIPPED, ROARS OFF MONDAY’S CYCLE LOW). MSFT +2.28% TO $460.52. BUT META -5.07% TO $600.47, TSLA -4.57% TO $415.88, AMZN -3.47% TO $261.26, AAPL -1.84%, GOOG -1.02% CRASHED. CIBR +5.74% TO $94.15 (INTO PANW TONIGHT). SOXX +0.50% GREEN (NVDA). ONLY 2 OF 11 SECTORS GREEN: XLK +2.48%, XLE +1.79%; XLU -2.97% WORST. MONDAY CLOSE: SPY +1 TO STRNG 75 (NEW BASELINE HIGH), LEADERSHIP NEW RLTV RECORDS — CIBR 1.34, SMH 1.35 (RECORD), IGV 1.18, MSOS 1.27, XLK 1.27 — BUT BOND COMPLEX CRASHED: TIP -20, SHY -15, HYG -10, MBB -7, IEF -7. DEFENSIVES/RATE-SENSITIVES CRUSHED: XLU -10, XLRE -9, XLY -10, PPH -10, ITA -9, KRE -7. REFLATION SURGED: CPER +6, USO +7/1.41, UUP +5, XLE +6. MOVE +4.43% TO 73.3327 — BACK ABOVE PRE-WAR BASELINE 73.21 FIRST TIME. CURVE FLIPPED A 5TH TIME — BULL STEEPENER. WTI $91.37; COPPER +1.48%; GOLD +1.05% (HAVEN); BTC -3.49% TO $69,230. VLUE VALUE +1.70% LEADS (CYCLICAL ROTATION). COR1M -4.90% TO 6.02 — NEW WAR-LOW. EUROSTOXX +1.23%, DAX +0.74%. EUR CPI FLASH 5AM (CORE 2.4% / HEADLINE 3.2% — HOTTER). JOLTS 10AM (6.87M). PANW TONIGHT. NFP FRIDAY — CONS CUT TO 85K.
The narrowing has produced its first violent rotation — and the baton has passed. For three sessions the entire market rode on MSFT alone while NVDA broke to a cycle low and the AI-infrastructure trade looked dead. Overnight, that completely flipped: NVDA +6.26% to $224.36 — a massive reversal, roaring back off Monday’s low and reclaiming semiconductor leadership. MSFT +2.28% to $460.52 extends. But the rotation is brutal on the other side: the consumer/internet/social Mag 7 cohort CRASHED — META −5.07% to $600.47, TSLA −4.57% to $415.88, AMZN −3.47% to $261.26, AAPL −1.84%, GOOG −1.02%. The leadership did not broaden; it rotated. The market is still carried by a thin set of names — but the names changed overnight from MSFT-alone to NVDA-plus-MSFT, while four of the other five Mag 7 names are deeply red. ES −0.19% to 7,598.75 reflects the churn beneath the surface: the index pulled back off Monday’s new high (back below 7,600) because the rotation’s losers (META, AMZN, TSLA) outweigh the winners at the index level. Cumulative ES vs pre-war 6,881.62: +10.42%.
Monday’s cash close was the violent repricing that set this up. SPY baseline rose +1 to STRNG 75 (a new war-cycle baseline high — the narrowing melt-up continued), and the leadership cohort printed a stack of new RLTV records: XLK Technology RLTV 1.27 (new high, above 1.25), CIBR Cybersecurity 85 / RLTV 1.34 (new high, above 1.28), SMH Semiconductor 73 / RLTV 1.35 (a new war-cycle record, above 1.34), IGV Software 81 / RLTV 1.18 (new high), FDN Internet 80 / RLTV 1.08, MSOS Cannabis 58 / RLTV 1.27 (new high, exploding). But beneath that, the bond market was destroyed: TIP TIPS −20 to STRNG 36, SHY 1-3Y −15 to 38, HYG High-Yield −10 to 47, MBB −7, IEF −7, PFF −6, LQD −5, MUB −5, EMB −5 — the five-session disinflation bond rally reversed in a single session, the largest fixed-income unwind of the war. And the reflation trade surged: CPER Copper +6 to 62, USO Crude +7 to 49 / RLTV 1.41, UUP Dollar +5 to 58, XLE Energy +6 to 47, CRAK Oil Refiners +6, XOP +5, AMLP +6. The rate-sensitives and defensives were crushed: XLU Utilities −10 to STRNG 32, XLRE Real Estate −9 to 41, XLY Consumer Discretionary −10 to 50, XLV Health-Care −6, PPH Pharma −10, ITA Aerospace −9, REZ −8, KRE Regional Banks −7, XBI −7, IBB −7, REM −7. Monday was a wholesale rotation OUT of duration/defensives and INTO reflation/cyclicals — with the AI/Cyber/Semi leadership riding above it all at new records.
The rates complex confirms the regime is destabilizing. MOVE expanded +4.43% to 73.3327 — back ABOVE the pre-war baseline of 73.21 for the first time (now +0.12 above pre-war), a full round-trip from the war-low of 67.25 and the second consecutive expansion session. The nine-session compression all-clear is decisively over; rates-vol is re-pricing tail risk. And the yield curve flipped AGAIN — now a Bull Steepener (yields falling, long-end faster: 2Y −0.6 bps to 4.027%, 30Y −1.8 bps to 4.953%) — the FIFTH distinct curve regime in five readings (Bull Steepener → Bull Flattener → Bear Flattener → Flattener Twist → Bull Steepener). A curve that cannot hold a regime for two sessions running is the textbook signal of a market with no macro conviction — exactly the backdrop in which leadership rotates violently and dispersion runs to extremes. COR1M compressed further to 6.02 — a NEW war-low (below Monday’s 6.33), the deepest single-stock dispersion of the entire war. The cross-asset signature — MOVE back above pre-war, curve in chaos, correlation at a record low, leadership rotating overnight — is a market in transition, not a market at rest.
And the reflation/haven cross-currents are intensifying. WTI is holding $91.37 (−0.86%, after Monday’s surge through $89) with Brent $94.12; Copper +1.48% to $6.6495 (the reflation trade persists). But Gold +1.05% to $4,553.60 is rallying with silver +1.97%, platinum +1.90%, palladium +1.69% — a precious-metals haven bid that the DYRH explicitly flags as confirming a risk-off undertone. BTC −3.49% to $69,230 (below $70K) is the risk-off tell in crypto. VLUE Value +1.70% leads the factor tape (the cyclical rotation), while SPLV Low-Vol −1.25% is crushed. The catalyst path is dense: EUR CPI Flash printed at 5:00 AM (Core consensus 2.4% vs 2.2% prior, headline 3.2% vs 3.0% — a European inflation re-acceleration that drove EuroStoxx +1.23% and DAX +0.74%); JOLTS Job Openings at 10:00 AM (consensus 6.87M); BOE Governor Bailey speaks at 10:00 AM. PANW reports Q3 FY26 after the close tonight — the binary catalyst for the CIBR 1.34 record. And Friday’s NFP consensus has been CUT to 85K (from 95K). The structural read: the index trend is intact but transitioning, the leadership is rotating rather than broadening, rates-vol has broken back above pre-war, and the market is hedging the concentration through gold and tail-protection.
The Number That Matters: NVDA +6.26% To $224.36 — The Semiconductor Baton Passes. The Failed-Bounce Stock Roars Off Monday’s Cycle Low While META -5.07% / TSLA -4.57% / AMZN -3.47% Crash — Leadership Rotated, Not Broadened. ES -0.19% Off Monday’s New High. Monday Close: SPY +1 To 75, CIBR 1.34 / SMH 1.35 / IGV 1.18 New RLTV Records, But Bond Complex CRASHED (TIP -20, SHY -15, HYG -10) + Defensives Crushed (XLU -10, XLRE -9). MOVE +4.43% To 73.33 — Back ABOVE Pre-War First Time. Curve Flips A 5th Time (Bull Steepener). COR1M War-Low 6.02. PANW Tonight.
This is the handoff session. The market is not breaking and it is not broadening — it is rotating, violently, within an ever-narrow leadership set. NVDA roars back from the dead while META/TSLA/AMZN crash; reflation/cyclicals surge while duration/defensives are destroyed; rates-vol breaks back above pre-war while correlation runs to a record low; gold catches a haven bid while the index makes (and then gives back) new highs. The structural bull thesis remains intact at the index level — SPY at a new baseline high Monday, AI/Cyber/Semi at new records — but the internal regime is in flux: the curve cannot hold a shape, the bond complex was destroyed in a session, and the leadership baton is changing hands overnight. PANW tonight is the binary that either validates the CIBR 1.34 record or triggers the cyber unwind into the most-extended positioning of the war.
The Setup: THE SEMICONDUCTOR HANDOFF. NVDA +6.26% Roars Back As The Baton Passes; MSFT +2.28% / CIBR +5.74% Carry While META -5.07% / TSLA -4.57% / AMZN -3.47% Crash. ES -0.19% Off Monday’s New High; RUT +0.03% Green. Monday Close: SPY +1 To 75, Leadership New RLTV Records (CIBR 1.34, SMH 1.35, IGV 1.18) But Bonds CRASHED (TIP -20, SHY -15) + Defensives Crushed (XLU -10, XLRE -9). MOVE +4.43% Back Above Pre-War. Curve Flips 5th Time. Oil $91 / Copper / Gold Reflation+Haven. COR1M War-Low 6.02. PANW Tonight. JOLTS 10AM. NFP Friday Cons Cut To 85K.
2. OVERNIGHT SESSION RECAP
Asia — Nikkei -0.61% Pulled Back; Topix Flat
Nikkei 66,890 (−0.61%) pulled back after Monday’s +1.52% surge — Japan giving back a portion of the megacap-driven rally as the global tech rotation churned. TOPIX 3,926.50 (+0.06%) roughly flat. The Japan pullback is consistent with the overnight rotation OUT of the consumer/momentum-megacap complex (which dragged the Nikkei Monday) and the broader risk-churn. EWJ Japan Monday close held STRNG 62 / RLTV 0.93. AAXJ Asia ex-Japan SURGED +5 to STRNG 71 / RLTV 1.05 Monday (the strongest Asia ex-Japan reading of the war), and FXI China +4 to 40 — the international/EM complex is catching a strong bid even as US megacaps rotate. The Asia tape: Japan consolidating, but broad Asia/EM strengthening into the global rotation.
Europe — EuroStoxx +1.23% Ripping; DAX +0.74% On EUR CPI Re-Acceleration
EuroStoxx 50 6,101 (+1.23%) RIPPING and DAX 25,212 (+0.74%) strong — European equities surging, outperforming the US sharply. The catalyst: EUR CPI Flash printed at 5:00 AM (Core consensus 2.4% vs 2.2% prior, headline 3.2% vs 3.0% prior — a European inflation re-acceleration). Counterintuitively, the hotter European inflation print drove equities HIGHER — the read is that re-accelerating nominal growth + a still-easing ECB is a reflationary tailwind for European cyclicals/financials, consistent with the global reflation rotation. EUR 1.166 (+0.18%) firmer. GBP 1.3474 (+0.13%) ahead of BOE Governor Bailey at 10:00 AM. FEZ Europe Monday close held STRNG 58 / RLTV 0.92. The European tape is the clearest reflation-rotation beneficiary this morning — value/cyclical-heavy indices ripping on the nominal-growth re-acceleration.
US Pre-Market — ES Off Monday’s High; RUT +0.03% Green (Small-Caps Outperform)
ES 7,598.75 (−0.19%, −14.5 pts) — pulling back off Monday’s new high, back below 7,600 (the rotation’s losers outweighing winners at the index level). NQ 30,541.25 (−0.08%) roughly flat — NQ outperforming ES (NVDA +6.26% + MSFT +2.28% cushioning the Nasdaq even as META/AMZN/TSLA crash). RUT 2,910.50 (+0.03%) GREEN — small-caps outperforming for the first time in weeks (the rotation is, at the margin, broadening down-cap; the DYRH flags this as “genuine risk appetite”). Dow 50,879 (−0.50%) lagging (defensive/industrial-heavy Dow hit by the rotation). Cumulative ES vs pre-war 6,881.62: +10.42% (off Monday’s +10.63% high). Technical levels: ES support at 7,544 (Tue war-high), 7,500, 7,460; resistance at 7,613 (Monday close), 7,650. NQ support at 30,332, 30,000; resistance at 30,565 (Monday close area), 30,750. The index churn masks the violent internal rotation — the headline pullback is mild, but underneath, leadership is changing hands.
Mag 7 Pre-Market — NVDA +6.26% Roars Back; META -5.07% / TSLA -4.57% Crash
THE MAG 7 ROTATION IS VIOLENT — 2 GREEN / 5 RED, but the moves are enormous. NVDA $224.36 (+6.26%) — a MASSIVE reversal, roaring +$13.22 off Monday’s cycle-low close of $211.14; the failed-bounce narrative completely flipped, and NVDA is carrying the semiconductor complex (the AI-infrastructure trade is back from the dead). MSFT $460.52 (+2.28%) — extending above $460 (the AI-software leader continues). But the consumer/internet/social cohort CRASHED: META $600.47 (−5.07%) — the worst Mag 7 name, crashing below $601 (a −$32 single-session drop); TSLA $415.88 (−4.57%) extending its decline (the DYRH flags building idiosyncratic risk); AMZN $261.26 (−3.47%) breaking below $262; AAPL $306.31 (−1.84%) red; GOOG $372.58 (−1.02%) red. The rotation is the story: the AI-infrastructure/hardware cohort (NVDA, and MSFT’s Azure-AI) is bid, while the consumer-internet/advertising/EV cohort (META, AMZN, TSLA, GOOG, AAPL) is being violently sold. This is a leadership baton-pass WITHIN the megacap complex — not a broadening, a rotation. The breadth remains narrow; the names changed.
Sectors — Only 2 Of 11 Green: XLK +2.48% / XLE +1.79%; XLU -2.97% Worst
ONLY 2 OF 11 SECTORS GREEN — the narrow tape persists, now Tech + Energy. XLK Technology +2.48% LEADS (NVDA +6.26% + MSFT +2.28% driving). XLE Energy +1.79% — the reflation-rotation beneficiary (oil holding $91; energy extending Monday’s +6 STRNG surge). The other 9 sectors are RED: XLC Communication Services −0.07% (META −5.07% offset by GOOG/others), XLF Financials −0.29%, XLI Industrial −0.42%, XLB Materials −0.45%, XLP Consumer Staples −1.06%, XLV Health-Care −1.09%, XLRE Real Estate −1.64% (rate-sensitive hit as MOVE expands), XLY Consumer Discretionary −2.22% (AMZN −3.47% + TSLA −4.57% drag), XLU Utilities −2.97% (worst) — the rate-sensitive defensive crushed for a second session as the long-bond repricing and MOVE expansion hammer utility valuations. The sector tape: Tech (semis) + Energy (oil) are the only bids; the rate-sensitives (utilities, real estate), consumer (discretionary), and defensives (staples, health-care) are all selling. The reflation rotation is cleanly visible — cyclicals/energy up, duration/defensives down.
Factors — VLUE Value +1.70% Leads; SPLV Low-Vol -1.25% Crushed
The factor tape is the cleanest reflation-rotation signal of all. VLUE Value +1.70% LEADS decisively — the value/cyclical factor ripping as the reflation trade (oil, copper, rising nominal growth) rotates capital out of growth-duration and into value. LRGF Multi-Factor +0.60%, USMV Min-Vol +0.36%, MTUM Momentum +0.35%, SPHB High-Beta +0.31%, QUAL Quality +0.22%, RSP Equal-Weight +0.18% (equal-weight green — a marginal breadth improvement vs the cap-weight). VYM 0.00% flat. RED: IJH Mid-Cap −0.08%, IJR Small-Cap −0.14%, DGRO Dividend-Growth −0.24%, SPLV Low-Volatility −1.25% (worst) — the low-vol/defensive factor crushed as rates-vol (MOVE +4.43%) expands and the defensive bid unwinds. The VLUE-leads / SPLV-crushed configuration is the textbook reflation rotation: value beats growth, cyclicals beat defensives, and the rate-vol expansion penalizes the low-vol complex. Value leadership without a broad-market melt-up confirms the rotation is defensive-to-cyclical, not a fresh risk-on leg.
Thematics — CIBR +5.74% Explodes Into PANW; SOXX +0.50% Green (NVDA)
CIBR Cybersecurity +5.74% to $94.15 — EXPLODING AGAIN (extending Monday’s +4 STRNG / RLTV 1.34 record to $94; cyber is the single strongest theme into PANW’s report tonight, fully decoupled from the broad-tape weakness). SOXX Semiconductor +0.50% GREEN (NVDA +6.26% driving the semis complex back to green — the AI-infrastructure re-engagement). FINX FinTech +1.33% (financials-adjacent reflation bid), BLOK +1.13% (despite BTC −3.49%), ARKW Next-Gen Internet +0.78%, ARKG Genomic +0.32%. RED: DRIV Autonomous −0.06%, PAVE Infrastructure −0.59%, ARKQ Autonomous −2.09%, ICLN Clean Energy −2.25%, ITA Aerospace Defense −2.35% — the clean-energy and defense complexes pulled back hard (ICLN/ITA reversing as the rotation favors semis/cyber over clean-energy/defense). The thematic tape: CIBR + SOXX + FINX are the bids (cyber/semi/fintech), while clean-energy, defense, and autonomous sold off. Leadership is concentrating into cyber + semis ahead of PANW, rotating away from the clean-energy cohort that led last week.
Commodities — WTI Holds $91; Copper +1.48%; Gold +1.05% Haven Bid; BTC -3.49%
WTI $91.37 (−0.86%) — holding above $91 after Monday’s surge through $89 (the oil shock is sustained; the modest pullback does not reverse the reflation move). Brent $94.12 (−0.91%). Heating Oil −0.51%, RBOB −0.27%; Natural Gas $3.14 (−1.23%). Ethanol +3.78% (recovering from Monday’s collapse). METALS — a broad precious + industrial bid: Copper $6.6495 (+1.48%) — extending higher (reflation persists; copper at a multi-week high). Gold $4,553.60 (+1.05%) — rallying with Silver +1.97%, Platinum +1.90%, Palladium +1.69% — a broad precious-metals haven bid that the DYRH explicitly flags as confirming a risk-off undertone beneath the rotation. The Gold + Copper combination — haven AND reflation simultaneously bid — captures the regime’s contradiction: the market is pricing both inflation risk and tail risk at once. Softs EXPLODING: Cocoa +7.39%, Orange Juice +6.07%, Cotton +0.64%. Grains mostly red (Wheat −0.74%, Soybeans −0.23%). Livestock green (Feeder Cattle +0.90%). BTC $69,230 (−3.49%) — crashing below $70K (the risk-off tell in crypto; down from $72,260 Monday). The commodity tape — oil holding, copper extending, gold/silver/platinum bid, BTC crashing — is the cross-asset signature of a reflation-plus-haven regime: real assets bid, risk-crypto sold.
3. THE PRIOR DAY’S REGIME
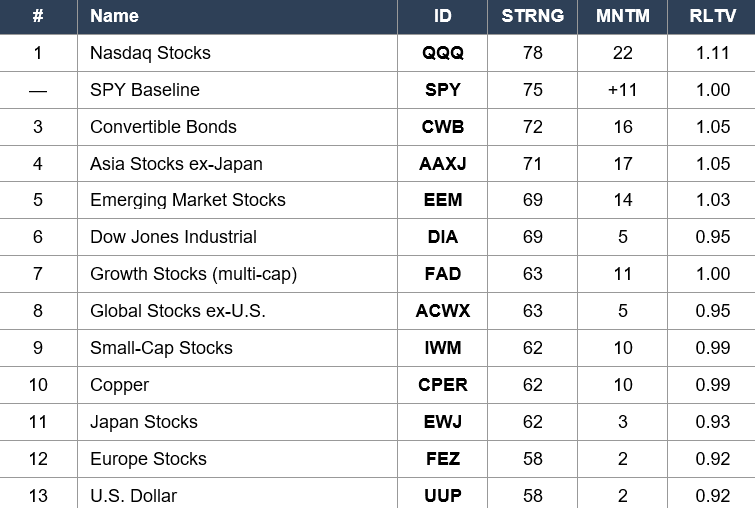
34 Macro Price, Strength & Momentum Rankings — Daily Close, Monday June 1. SPY Baseline: STRNG 75 | MNTM +11 | RLTV 1.00. SPY +1 STRNG (New Baseline High) — Leadership New Records As The Bond Complex Was Destroyed.
Asset Classes — Leaders (SPY +1 To 75; Asia/EM Surged; Copper +6)
Asset Classes — The Bond Complex CRASHED (TIP -20, SHY -15, HYG -10); USO +7
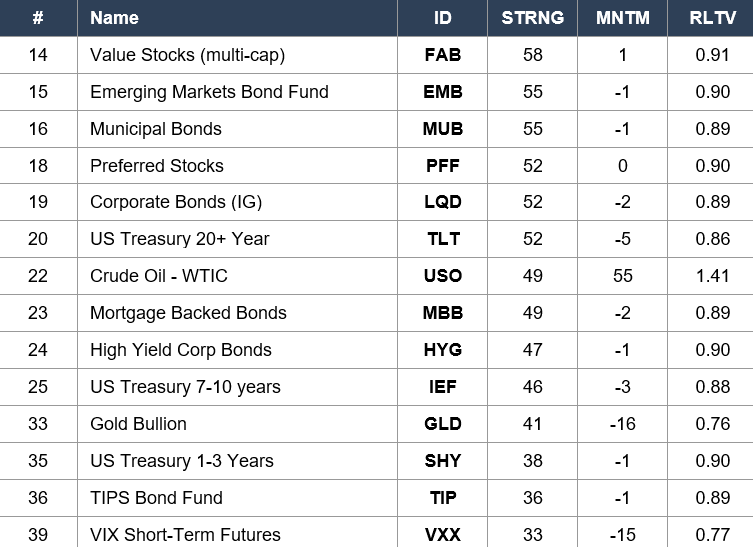
Regime signal: MONDAY DELIVERED A NEW BASELINE HIGH ALONGSIDE THE LARGEST BOND-COMPLEX UNWIND OF THE WAR — A WHOLESALE REFLATION ROTATION. SPY baseline ROSE +1 to STRNG 75 (a new war-cycle baseline high; the narrowing melt-up continued). QQQ +1 to STRNG 78 / RLTV 1.11 (new high). THE INTERNATIONAL/EM COMPLEX SURGED: AAXJ Asia ex-Japan +5 to STRNG 71 / RLTV 1.05 (strongest of the war), EEM EM +4 to STRNG 69 / RLTV 1.03, ACWX Global +2 to 63, FXI China +4 to 40 — the weaker-dollar-plus-reflation tailwind drove ex-US equities. CPER Copper SURGED +6 to STRNG 62 and USO Crude SURGED +7 to STRNG 49 / RLTV 1.41 — the reflation trade exploded. UUP Dollar SURGED +5 to STRNG 58 (the dollar bid on the rate-rise). BUT THE BOND COMPLEX WAS DESTROYED: TIP TIPS CRASHED −20 to STRNG 36 (the single largest asset-class STRNG decline of the war), SHY 1-3Y CRASHED −15 to 38, HYG High-Yield −10 to 47, MBB Mortgage −7 to 49, IEF 7-10Y −7 to 46, PFF Preferred −6 to 52, MUB Munis −5 to 55, EMB EM Bonds −5 to 55, LQD Corporate −5 to 52 — the five-session disinflation bond rally reversed in a single session as the reflation repricing tore through fixed income. GLD Gold −4 to STRNG 41 (gold sold on the rate-rise/dollar-surge, before today’s haven-bid recovery). IWM Small-Cap −2 to STRNG 62 / RLTV 0.99 (small-cap RLTV slipped below 1.00). BKLN Senior Loans +7 to 45 (floating-rate bid in the rising-rate environment). VXX VIX Futures +6 to STRNG 33 (vol bid building into the close). The Monday configuration: equity at a new high, reflation/commodities/dollar surging, the entire bond complex destroyed — the cleanest reflation-rotation session of the war.
Sector ETFs (XLK RLTV 1.27 NEW High; XLE +6; Rate-Sensitives CRUSHED)
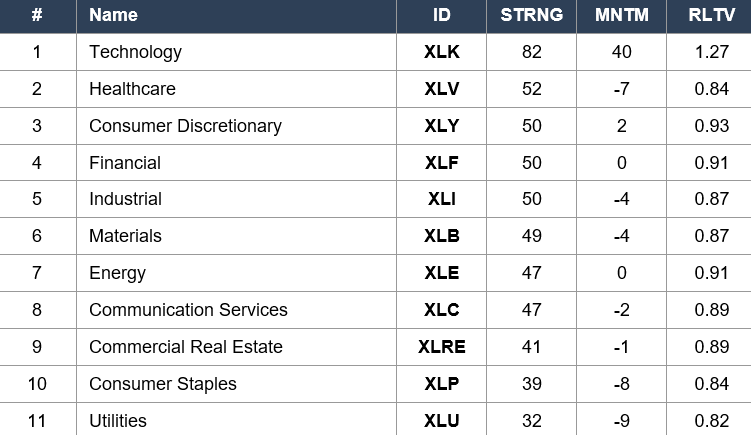
Regime signal: MONDAY DELIVERED THE MOST EXTREME SECTOR NARROWING-PLUS-ROTATION OF THE WAR — XLK ALONE AT A NEW RECORD WHILE THE RATE-SENSITIVES COLLAPSED. XLK Technology EXTENDED +2 to STRNG 82 / RLTV 1.25 → 1.27 — a NEW war-cycle high RLTV (Tech now positioned 27 percentage points above SPY baseline, the highest sector RLTV ever in the war). XLE Energy SURGED +6 to STRNG 47 / RLTV 0.91 — the reflation-rotation beneficiary (oil surge), the second-strongest sector move. But EVERYTHING ELSE FELL HARD: XLY Consumer Discretionary CRASHED −10 to STRNG 50 (a full reversal), XLV Health-Care CRASHED −6 to STRNG 52, XLF Financials −1 to 50, XLI Industrial −2 to 50, XLB Materials −2 to 49, XLC Communication Services −1 to 47, XLRE Real Estate CRASHED −9 to STRNG 41 (rate-sensitive destroyed by the bond unwind), XLP Consumer Staples −4 to STRNG 39 (defensive capitulation continuing), XLU Utilities CRASHED −10 to STRNG 32 (the single largest sector STRNG decline of the war; the rate-sensitive defensive obliterated by the long-bond repricing). The sector configuration: XLK at a record 1.27 standing alone, XLE surging on oil, and a broad-based collapse across rate-sensitives (utilities, real estate), consumer, and defensives. The reflation rotation crushed everything duration-linked while Tech extended its record — the narrowing and the rotation occurring simultaneously.
Industry ETFs — Leaders (CIBR 1.34 / SMH 1.35 / IGV 1.18 NEW Records)
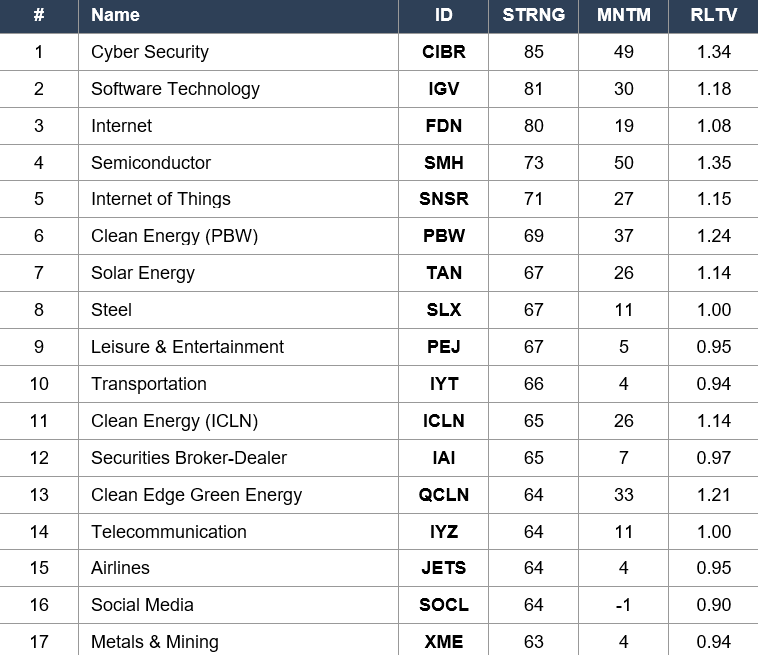
Industry ETFs — MSOS 1.27 / BJK +10 / Energy Bid; Banks & Biotech CRASHED
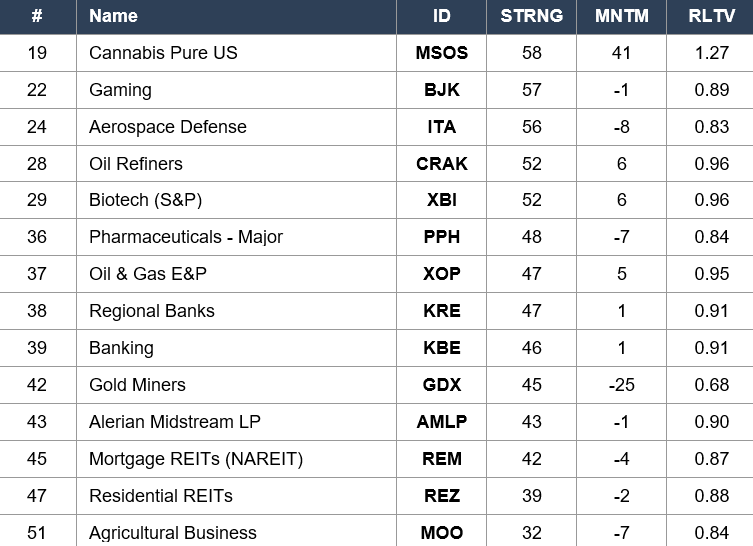
Regime signal: MONDAY DELIVERED NEW INDUSTRY RECORDS IN THE AI/CYBER/SEMI COHORT WHILE THE RATE-SENSITIVE AND HEALTHCARE TAIL CRASHED — THE ROTATION MIRRORED AT THE INDUSTRY LEVEL. CIBR Cybersecurity EXTENDED +4 to STRNG 85 / RLTV 1.28 → 1.34 — a NEW war-cycle record (cyber at unprecedented strength into PANW tonight). IGV Software EXPLODED +5 to STRNG 81 / RLTV 1.13 → 1.18 — a NEW record (the MSFT-driven software surge). SMH Semiconductor EXTENDED +2 to STRNG 73 / RLTV 1.34 → 1.35 — a NEW war-cycle record (the highest single-industry RLTV ever, extending again — the precursor to today’s NVDA +6.26%). FDN Internet +4 to STRNG 80 / RLTV 1.08 (new high). MSOS Cannabis EXTENDED +3 to STRNG 58 / RLTV 1.15 → 1.27 — a NEW high (MNTM +41, exploding). SOCL Social Media +8 to STRNG 64, BJK Gaming +10 to STRNG 57 (risk-on pockets). The energy/reflation complex was bid: CRAK Oil Refiners +6 to 52, XOP Oil & Gas E&P +5 to 47, AMLP Midstream +6 to 43 (recovering off its war-low), OIH +2 to 42, COPX Copper Miners +3 to 60. But THE RATE-SENSITIVE/HEALTHCARE TAIL CRASHED: PPH Pharma CRASHED −10 to STRNG 48, ITA Aerospace Defense −9 to 56, XBI Biotech −7 to 52, IBB Biotech −7 to 49, KRE Regional Banks −7 to 47, KBE Banking −6 to 46, REM Mortgage REITs −7 to 42, REZ Residential REITs −8 to 39 (rate-sensitive REITs and banks destroyed by the bond unwind; healthcare/biotech sold). TAN Solar −10 STRNG to 67 and ICLN −8 STRNG to 65 (clean-energy STRNG fell sharply, though RLTV held 1.14). GDX Gold Miners −4 to 45 (gold sold Monday). The industry tape: AI/Cyber/Semi/Software at new records, energy/cannabis/gaming bid, but a broad crash across REITs, banks, pharma, biotech, and (in STRNG terms) clean-energy — the reflation rotation reshaping the entire board.
4. MORNING DATA REACTION
EUR CPI Flash Printed 5:00 AM (Hotter); JOLTS 10:00 AM; No US Data Pre-8:50 AM
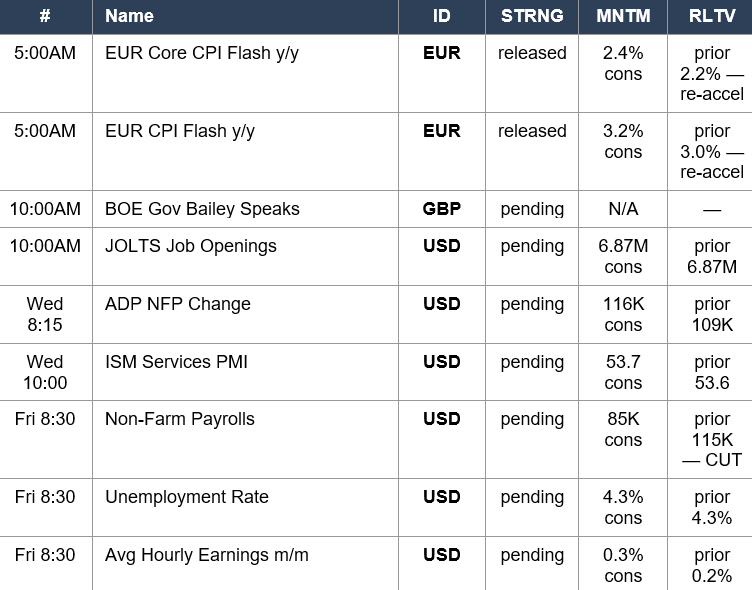
EUR CPI Flash (5:00 AM) — European Inflation Re-Acceleration
EUR CPI Flash printed at 5:00 AM (before the report timestamp): Core CPI Flash y/y consensus 2.4% (vs 2.2% prior) and headline CPI Flash y/y consensus 3.2% (vs 3.0% prior) — a European inflation re-acceleration. Counterintuitively, the hotter print drove European equities sharply HIGHER (EuroStoxx +1.23%, DAX +0.74%) and the EUR firmer (+0.18%). The market read: re-accelerating nominal growth in Europe, combined with a still-easing ECB, is a reflationary tailwind for European cyclicals and financials — the same reflation-rotation dynamic playing out globally. The European inflation re-acceleration is also a cross-current for the global disinflation thesis: if inflation is re-accelerating in Europe and US oil/copper are surging, the synchronized-disinflation narrative that drove the bond rally is under pressure (consistent with Monday’s US bond-complex crash and MOVE back above pre-war).
JOLTS Job Openings (10:00 AM) — Labor-Demand Read Into NFP Week
JOLTS Job Openings at 10:00 AM (consensus 6.87M, unchanged from prior) — the first US labor read of the NFP week. A beat (above 6.87M) signals labor demand re-firming (hawkish, reinforcing the reflation/bear-repricing); a miss (below 6.7M) signals labor-demand cooling (dovish, supporting the rate-cut path). With Friday’s NFP consensus CUT to 85K (from 95K — a more pronounced labor cooling now expected), the JOLTS print sets the tone: a hot JOLTS against a cut NFP consensus would sharpen the data tension into Friday. BOE Governor Bailey also speaks at 10:00 AM — watch for UK/global rate-path signals.
PANW Q3 FY26 Tonight (AMC) — The Cyber Binary Into A 1.34 Record
PANW (Palo Alto Networks) reports Q3 FY26 after the close TONIGHT — the single most important catalyst of the week for the leadership tape. CIBR Cybersecurity printed a NEW RLTV war-record 1.34 Monday and is surging +5.74% to $94.15 this morning — the cohort is at its most-extended positioning of the entire war heading into the print. The asymmetry is sharp: a clean beat + strong forward guide could push CIBR toward RLTV 1.36+ and validate the semi/cyber leadership handoff; a guide-down or any enterprise-spending-deceleration commentary risks a violent unwind from peak positioning (the Wednesday May 27 CIBR −12 single-session crash demonstrated the downside). Watch CyberArk integration, Chronosphere ARR, federal/government contracts, AI-security capex, and net-retention. With CIBR at a record and NVDA roaring back into the semi handoff, PANW tonight is the binary that defines whether the leadership rotation holds or breaks.
This Week — NFP Friday (Cons Cut To 85K) Into The Warsh FOMC
The week’s catalyst path: today JOLTS (10:00) + BOE Bailey. Wednesday: ADP NFP Change (8:15, cons 116K) + ISM Services PMI (10:00, cons 53.7). Friday: the decisive print — Non-Farm Payrolls (consensus CUT to 85K from 95K — a more pronounced cooling now expected), Unemployment Rate (cons 4.3%), Average Hourly Earnings m/m (cons 0.3% vs 0.2% prior). The NFP consensus cut to 85K is notable: the market is positioning for a softer labor print, which would support the rate-cut path — but the AHE wage component (0.3%) against this morning’s reflation surge (oil $91, copper, European CPI re-acceleration) is the inflation cross-current. A cool NFP + hot AHE would be the most confusing outcome into the June 16-17 Warsh FOMC. The reflation rotation + bond crash + MOVE-above-pre-war backdrop means the labor data lands into a market already re-pricing the easing path.
5. THE DYRH READ
Yield Curve Regime: Bull Steepener — The 5th Distinct Regime In 5 Readings
The curve has flipped AGAIN — now a Bull Steepener (yields falling, long-end faster): 2Y −0.6 bps to 4.027%, 5Y −1.8 bps to 4.149%, 10Y −1.6 bps to 4.437%, 30Y −1.8 bps to 4.953%. The long end is falling faster than the front — declining long-run inflation/growth expectations driving the steepening, while the front holds (the Fed-path repricing). This is the FIFTH distinct curve regime in five readings: Bull Steepener (Thu) → Bull Flattener (Fri) → Bear Flattener (Mon AM) → Flattener Twist (Mon close) → Bull Steepener (Tue AM). A curve that cannot hold a shape for two consecutive sessions is the cleanest signal of a market with no macro conviction — the bond market is whipsawing between disinflation-pricing and reflation-pricing day to day. The 2s/30s spread widens to 92.6 bps. Note the contradiction with Monday’s cash close (which destroyed the bond complex): today bonds are bid (yields falling) even as the structural reflation backdrop (oil, copper, MOVE) persists — the daily mean-reversion in a destabilized rates complex. 30Y at 4.953% holds below 5.00% (Day 4).
MOVE Index: 73.33 (+4.43%) — Back ABOVE Pre-War Baseline First Time
MOVE EXPANDED +4.43% (+3.11 points) to 73.3327 — back ABOVE the pre-war baseline of 73.21 for the first time (now +0.12 above pre-war), the second consecutive expansion session. The full round-trip is complete: from the Tuesday May 19 peak of 86.07, down to the war-low of 67.25, and now back through pre-war. The nine-session compression all-clear is decisively over — rates-vol is re-pricing tail risk in earnest. This is the single most important regime signal on the board: the structural-calm bond backdrop that underwrote the equity melt-up (MOVE persistently below pre-war) has ended. Elevated and rising rates-vol historically constrains equity multiple expansion — the gravity-weight the DYRH flags. The MOVE expansion coincides with the bond-complex crash (Monday), the curve chaos (five regimes), the reflation surge (oil/copper), and the gold haven bid — a cross-asset cluster signaling the rates regime has inflected from compression to expansion. Watch whether MOVE sustains above 73.21 (the all-clear is over) or whether this is an overshoot that mean-reverts back below.
S&P 500: ES 7,598.75 — Off Monday’s New High; Rotation Beneath The Surface
ES at 7,598.75 (−0.19%) pulled back off Monday’s new high, back below 7,600 (the rotation’s losers — META, AMZN, TSLA — outweighing the winners at the index level). NQ 30,541.25 (−0.08%) roughly flat (NVDA + MSFT cushioning). RUT 2,910.50 (+0.03%) green — the small-cap outperformance is a marginal breadth improvement. Cumulative ES vs pre-war 6,881.62: +10.42% (off Monday’s +10.63% high). The index-level move is mild, but it masks the violent internal rotation: the leadership baton passed from MSFT-alone to NVDA-plus-MSFT overnight, the consumer/internet cohort crashed, and the reflation/value rotation reshaped the sector and factor tapes. Technical levels: ES support at 7,544 (Tue war-high), 7,500, 7,460; resistance at 7,613 (Monday close), 7,650. The key question: is the rotation (NVDA back, value bid, small-caps green) a healthy broadening that sustains the trend, or a churning top where leadership rotates because no group can hold the bid? PANW tonight + NFP Friday will resolve it.
Key Levels & Cumulative War Moves
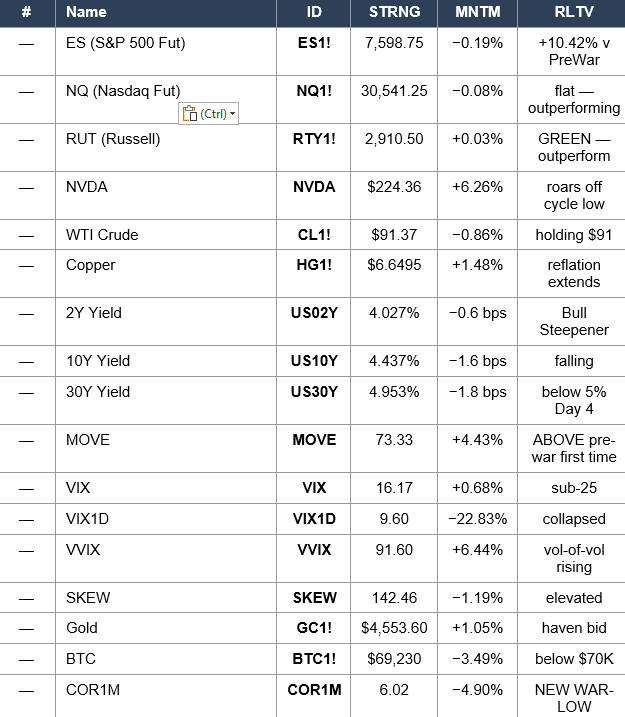
Volatility & Breadth — MOVE Above Pre-War; VVIX Up; VIX1D Collapses; COR1M War-Low
The vol complex is sending mixed but escalating signals. MOVE +4.43% to 73.33 — back above pre-war, the dominant signal: rates-vol has inflected from compression to expansion. VVIX +6.44% to 91.60 — the vol-of-vol rising sharply (the options market is re-pricing the cost of volatility itself; a sign of building hedging demand). VXN +2.66% to 23.18 (Nasdaq-vol rising). VIX +0.68% to 16.17 (modestly higher, still sub-25). GVZ Gold-vol +2.93% to 25.64 (gold-vol rising with the haven bid). But VIX1D COLLAPSED −22.83% to 9.60 — the one-day vol cratered (the immediate-term hedges came off even as longer-dated vol, MOVE/VVIX, expanded); this divergence (1-day vol down, term vol up) signals the market is comfortable today but hedging the medium term — consistent with pricing PANW-tonight and NFP-Friday risk rather than intraday risk. SKEW −1.19% to 142.46 (pulled back slightly from 144 but still elevated — tail-hedges remain on). COR1M compressed to 6.02 — a NEW war-low (below Monday’s 6.33), the deepest single-stock dispersion of the entire war: the violent intra-Mag-7 rotation (NVDA +6.26% vs META −5.07%) is dispersion in its purest form. The combination — MOVE/VVIX expanding (term-risk pricing up) + VIX1D collapsing (intraday calm) + COR1M at a record low (extreme dispersion) + SKEW elevated (tail-hedges on) — is the signature of a market churning through a violent rotation while hedging the upcoming binary catalysts. Trailing breadth (S5TH 70.10) holds, but the regime is destabilizing.
6. THE GAME PLAN
Today: THE SEMICONDUCTOR HANDOFF. The leadership baton passes — NVDA +6.26% to $224.36 roars off Monday’s cycle low while META −5.07% / TSLA −4.57% / AMZN −3.47% crash; MSFT +2.28% / CIBR +5.74% carry. ES −0.19% off Monday’s new high; RUT +0.03% green. Monday close: SPY +1 to 75 (new baseline high), leadership new RLTV records (CIBR 1.34, SMH 1.35 record, IGV 1.18, MSOS 1.27, XLK 1.27), but the bond complex CRASHED (TIP −20, SHY −15, HYG −10) + rate-sensitives/defensives crushed (XLU −10, XLRE −9, PPH −10, KRE −7) as reflation surged (CPER +6, USO +7, XLE +6). MOVE +4.43% to 73.33 — back above pre-war first time. Curve flipped a 5th time (Bull Steepener). Oil $91 / Copper +1.48% / Gold +1.05% haven bid; BTC −3.49%. VLUE Value +1.70% leads (cyclical rotation). COR1M war-low 6.02. PANW tonight AMC. JOLTS 10AM. NFP Friday cons cut to 85K.
The Bull Case
The index trend is intact: SPY at a new baseline high Monday (STRNG 75), ES holding +10.42% vs pre-war, and the AI/Cyber/Semi leadership at new RLTV records (CIBR 1.34, SMH 1.35, IGV 1.18). The NVDA +6.26% reversal is potentially the bullish resolution to the narrowing — the AI-infrastructure cohort, left for dead at Monday’s cycle low, roaring back to rejoin MSFT in leadership broadens the megacap engine from one name to two. SOXX is green again (+0.50%). RUT is green (+0.03%) and the international/EM complex surged Monday (AAXJ +5 to 1.05, EEM +4 to 1.03) — the rotation is broadening down-cap and ex-US. VLUE Value +1.70% leading signals capital rotating into cheaper cyclicals rather than fleeing equities — a healthy rotation, not a liquidation. The reflation trade (oil $91, copper at multi-week highs, XLE surging) supports nominal-growth-sensitive cyclicals and energy. CIBR +5.74% into PANW tonight could deliver the next leg if the print confirms. A cool NFP Friday (cons cut to 85K) would re-engage the rate-cut path. Targets: ES 7,650 / 7,700, NVDA $230+, CIBR RLTV 1.36+.
The Bear Case
The dominant signals are destabilizing. MOVE is back above pre-war (73.33) for the first time — the rates-vol all-clear that underwrote the entire melt-up has ended, and rising rates-vol is the historical headwind to equity multiples. The yield curve has flipped FIVE times in five readings — a market with zero macro conviction, whipsawing between disinflation and reflation daily. Monday destroyed the bond complex (TIP −20, SHY −15, HYG −10) — the largest fixed-income unwind of the war — and crushed every rate-sensitive (XLU −10, XLRE −9, KRE −7, REZ −8). The leadership is rotating, not broadening: NVDA +6.26% is offset by META −5.07%, TSLA −4.57%, AMZN −3.47% — the index pulled back off its high because the rotation’s losers dominate. A market where leadership changes hands overnight, no sector can hold the bid (2 of 11 green again), and correlation runs to a record low (COR1M 6.02) is a churning, distribution-phase tape. Gold + silver + platinum are catching a haven bid (the DYRH flags risk-off), BTC crashed −3.49%, and VVIX +6.44% signals rising hedging demand. PANW tonight is a binary into the most-extended cyber positioning of the war — a guide-down repeats the May 27 CIBR −12 crash from a 1.34 record. The reflation surge (oil, copper, European CPI re-acceleration) pressures the disinflation/rate-cut thesis right as the cumulative +10.42% war premium sits at cycle extremes. Watch ES 7,544 (Tue war-high) — a break with the bond complex destroyed and MOVE rising engages 7,500 / 7,460 fast.
Regime: THE SEMICONDUCTOR HANDOFF — Leadership Rotates Violently (NVDA +6.26% vs META -5.07%), Not Broadens. ES Off Monday’s New High; SPY At 75 With Leadership Records (CIBR 1.34, SMH 1.35) But Bonds CRASHED + Rate-Sensitives Crushed. MOVE Back ABOVE Pre-War — The All-Clear Is Over. Curve Flips A 5th Time. Reflation (Oil/Copper) + Haven (Gold) Both Bid. COR1M War-Low 6.02. The Index Trend Holds But The Rates Regime Has Inflected. Watch PANW Tonight (Cyber Binary At A 1.34 Record), NVDA $224 (Handoff Confirm), ES 7,544 Support, MOVE 73.21 (Sustained Above = All-Clear Over), JOLTS 10AM, NFP Friday 85K.
Watch List
NVDA — The Baton Passes; +6.26% Roars Off Cycle Low; $230 Next
NVDA +6.26% to $224.36 is the session’s defining move — the failed-bounce stock that broke to a cycle low Monday roared +$13.22 overnight, reclaiming semiconductor leadership and dragging SOXX back to green. The AI-infrastructure trade is back from the dead. This is the bullish path for the narrowing: if NVDA can hold $224 and push toward $230, the megacap engine broadens from MSFT-alone to NVDA-plus-MSFT, and the SMH RLTV 1.35 record gets a fundamental anchor. The risk: a +6.26% gap that fades intraday would signal the reversal is a short-squeeze, not a trend change. Watch NVDA $224 (gap hold) → $230 (next resistance) vs a fade back below $218 (squeeze failure). NVDA is the single most important name on the board today.
PANW — Reports Tonight AMC; CIBR At A 1.34 Record; The Binary
PANW reports Q3 FY26 after the close tonight — the binary catalyst for the most-extended cyber positioning of the war. CIBR printed a NEW RLTV record 1.34 Monday and is +5.74% to $94.15 this morning. The asymmetry: a clean beat + strong guide validates the semi/cyber handoff and could push CIBR toward 1.36+; a guide-down triggers a violent unwind from peak positioning (the May 27 CIBR −12 crash is the template). Watch CyberArk integration, Chronosphere ARR, federal contracts, AI-security capex, net-retention rate. Position into the print with the awareness that CIBR is at a record and the downside is sharp. PANW is the week’s single largest leadership-cohort risk.
Mag 7 Rotation — META -5.07% / TSLA -4.57% / AMZN -3.47% Crash; Watch For Contagion
The consumer/internet/social Mag 7 cohort crashed: META −5.07% (−$32), TSLA −4.57%, AMZN −3.47%, AAPL −1.84%, GOOG −1.02%. This is the other side of the semi handoff — capital rotating OUT of advertising/EV/consumer-internet and INTO AI-infrastructure. Watch whether this stays a clean rotation (NVDA/MSFT absorb the flows, index holds) or becomes contagion (the selling spreads and NVDA/MSFT can’t hold the index alone). META below $600 and TSLA below $415 are the levels to watch — a break could accelerate the consumer-megacap unwind. The Mag 7 dispersion (NVDA +6.26% vs META −5.07% = an 11-point single-session spread) is the purest expression of the COR1M war-low 6.02.
Rates & Bonds — MOVE Above Pre-War; Curve Chaos; The All-Clear Is Over
MOVE back above pre-war (73.33) is the regime signal of the week: the rates-vol compression that underwrote the melt-up has ended. The curve has flipped five times in five readings (now Bull Steepener). Monday destroyed the bond complex (TIP −20, SHY −15, HYG −10). Today bonds are modestly bid (yields falling) — the daily mean-reversion in a destabilized complex. Watch MOVE 73.21 (sustained above = the all-clear is definitively over; a constraint on equity multiples), 30Y 5.00% (Day 4 below; a re-break above signals the reflation/disinflation fight resolving hawkish), and whether the curve can finally hold a regime for two sessions. The rates complex is the master variable — equity leadership rotations and dispersion extremes are downstream of the bond-market whipsaw.
Reflation vs Haven — Oil $91 / Copper Bid AND Gold/Silver Bid; The Contradiction
The commodity tape captures the regime’s central contradiction: reflation AND haven simultaneously bid. WTI holding $91.37, Copper +1.48% to $6.6495 (reflation/nominal-growth), while Gold +1.05% to $4,553.60, Silver +1.97%, Platinum +1.90% (haven/risk-off). The market is pricing inflation risk and tail risk at the same time — the signature of a destabilizing regime. XLE +1.79% (energy the cyclical bid); GDX was sold Monday (−4) but gold itself rallying. Watch oil $90 (a sustained hold extends the reflation/inflation tail at war-premium equity highs) and gold $4,560+ (a haven-bid acceleration would confirm the risk-off undertone is winning). BTC −3.49% below $70K is the risk-off tell. The reflation-plus-haven combination is the hardest backdrop to position — it argues for energy/value cyclicals AND gold/tail-hedges simultaneously.
Breadth & Rotation — RUT Green / Value Leads / International Surged; Healthy Or Churning?
The rotation has constructive elements: RUT +0.03% green (small-caps outperforming for the first time in weeks), VLUE Value +1.70% leading (capital rotating into cyclicals), AAXJ Asia +5 / EEM +4 surging Monday (ex-US broadening), RSP equal-weight green. The bearish read: the rotation is defensive-to-cyclical churn (SPLV crushed, duration destroyed) within a 2-of-11-green sector tape, and the index pulled back off its high. Watch whether the value/small-cap/international bid is a durable broadening (bullish — the melt-up’s leadership widens) or a one-session reflation reflex that fades. A second session of RUT/value/ex-US outperformance would confirm broadening; a reversal back to MSFT/NVDA-only leadership would confirm churning. This is the swing question for whether the trend sustains or tops.
Morning check: Day 96. THE SEMICONDUCTOR HANDOFF — the leadership baton passes as NVDA roars back. ES −0.19% to 7,598.75 (off Monday’s new high, back below 7,600; cumulative +10.42% vs pre-war 6,881.62). NQ −0.08% to 30,541.25 (flat — outperforming). RUT +0.03% to 2,910.50 GREEN (small-caps outperforming for the first time in weeks). The Mag 7 rotated violently: NVDA +6.26% to $224.36 — a massive reversal, roaring +$13.22 off Monday’s cycle-low close of $211.14 (the failed-bounce narrative flipped; NVDA reclaims semiconductor leadership and drags SOXX +0.50% green). MSFT +2.28% to $460.52 extends. But the consumer/internet/social cohort CRASHED: META −5.07% to $600.47 (−$32, worst), TSLA −4.57% to $415.88, AMZN −3.47% to $261.26, AAPL −1.84% to $306.31, GOOG −1.02% to $372.58. CIBR Cybersecurity +5.74% to $94.15 — exploding into PANW tonight (extending Monday’s 1.34 record). Only 2 of 11 sectors green: XLK +2.48% (NVDA + MSFT), XLE +1.79% (oil/reflation); XLU −2.97% worst, XLY −2.22% (AMZN/TSLA drag), XLRE −1.64%, XLV −1.09%, XLP −1.06%. VLUE Value +1.70% leads factors (cyclical rotation); SPLV Low-Vol −1.25% crushed; RSP equal-weight +0.18% green. FINX +1.33%, SOXX +0.50%; but ICLN −2.25%, ITA −2.35%, ARKQ −2.09% (clean-energy/defense pulled back). The curve flipped a FIFTH time in five readings — now Bull Steepener (yields falling, long-end faster): 2Y −0.6 bps to 4.027%, 5Y −1.8 bps to 4.149%, 10Y −1.6 bps to 4.437%, 30Y −1.8 bps to 4.953% (Day 4 below 5.00%). The sequence Bull Steepener → Bull Flattener → Bear Flattener → Flattener Twist → Bull Steepener signals zero macro conviction. MOVE +4.43% to 73.3327 — back ABOVE the pre-war baseline 73.21 for the first time (+0.12; second expansion session; the nine-session compression all-clear is decisively over). VVIX +6.44% to 91.60 (vol-of-vol rising); VXN +2.66% to 23.18; VIX +0.68% to 16.17; but VIX1D −22.83% to 9.60 (one-day vol collapsed — intraday calm, term-risk pricing up); SKEW −1.19% to 142.46 (elevated). COR1M −4.90% to 6.02 — NEW war-low (below Monday 6.33; deepest single-stock dispersion of the war — the NVDA +6.26% vs META −5.07% spread in its purest form). WTI holding $91.37 (−0.86%, after Monday’s surge through $89); Copper +1.48% to $6.6495 (reflation extends); Gold +1.05% to $4,553.60 (haven bid) with Silver +1.97%, Platinum +1.90%, Palladium +1.69%; BTC −3.49% to $69,230 (below $70K, risk-off tell); Cocoa +7.39%, Orange Juice +6.07% (softs exploding). EuroStoxx +1.23%, DAX +0.74% ripping (EUR CPI re-acceleration); Nikkei −0.61% pulled back. Monday cash close: SPY +1 to STRNG 75 (new baseline high — narrowing melt-up continued); leadership at NEW RLTV records — XLK 1.27 (above 1.25), CIBR 85/1.34 (above 1.28), SMH 73/1.35 (record, above 1.34), IGV 81/1.18 (above 1.13), FDN 80/1.08, MSOS 58/1.27 (above 1.15); SOCL +8 to 64, BJK +10 to 57. But the BOND COMPLEX CRASHED: TIP −20 to 36 (largest asset-class STRNG decline of the war), SHY −15 to 38, HYG −10 to 47, MBB −7 to 49, IEF −7 to 46, PFF −6 to 52, MUB −5 to 55, EMB −5 to 55, LQD −5 to 52. Reflation surged: CPER Copper +6 to 62, USO Crude +7 to 49/1.41, UUP Dollar +5 to 58, XLE Energy +6 to 47, CRAK +6 to 52, XOP +5 to 47, AMLP +6 to 43, COPX +3 to 60. Rate-sensitives/defensives crushed: XLU −10 to 32 (largest sector STRNG decline of the war), XLRE −9 to 41, XLY −10 to 50, XLV −6 to 52, PPH −10 to 48, ITA −9 to 56, XBI −7 to 52, IBB −7 to 49, KRE −7 to 47, KBE −6 to 46, REM −7 to 42, REZ −8 to 39. GLD Gold −4 to 41 (sold Monday, recovering today); IWM Small-Cap −2 to 62/0.99; VXX +6 to 33; AAXJ Asia +5 to 71/1.05, EEM +4 to 69/1.03 (ex-US surged). EUR CPI Flash printed 5:00 AM (Core cons 2.4%/prior 2.2%, headline 3.2%/prior 3.0% — re-acceleration, drove EuroStoxx +1.23%). JOLTS Job Openings 10:00 AM (cons 6.87M); BOE Gov Bailey 10:00 AM. PANW Q3 FY26 reports TONIGHT AMC — the cyber binary into a 1.34 record. This week: Wed ADP (cons 116K) + ISM Services (cons 53.7); Fri NFP (consensus CUT to 85K from 95K), Unemployment (4.3%), AHE m/m (0.3%) — into the June 16-17 Warsh FOMC. The narrative arc: RESOLUTION → EXTENSION → ACCELERATION → CONSOLIDATION → CONFIRMATION → NARROWING → and now THE HANDOFF. The index trend holds (SPY new baseline high Monday, leadership at records) but the regime has inflected: leadership rotating violently rather than broadening (NVDA back, META/TSLA/AMZN crashed), the bond complex destroyed Monday, MOVE back above pre-war (the all-clear over), the curve in chaos (five regimes in five reads), reflation AND haven both bid, and correlation at a record war-low (6.02) that will re-couple violently. Watch PANW tonight (cyber binary at a 1.34 record), NVDA $224/$230 (handoff confirm) vs $218 (squeeze fail), ES 7,544 (Tue war-high) support, MOVE 73.21 (sustained above = all-clear definitively over), JOLTS 10AM, NFP Friday 85K, the RUT/value/international broadening (healthy) vs reversal to MSFT/NVDA-only (churning). Pressure, not panic. Regime, not reaction. The baton has passed — NVDA roars back, but a market that rotates leadership overnight while rates-vol breaks above pre-war is a market in transition, not at rest.
The bell rings at 9:30. You’re ready.
— 34 Macro
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34 Macro.