

1. The Regime
Risk-on, extending — a fresh high, an orderly digestion, and a resolution back to new highs by Friday.
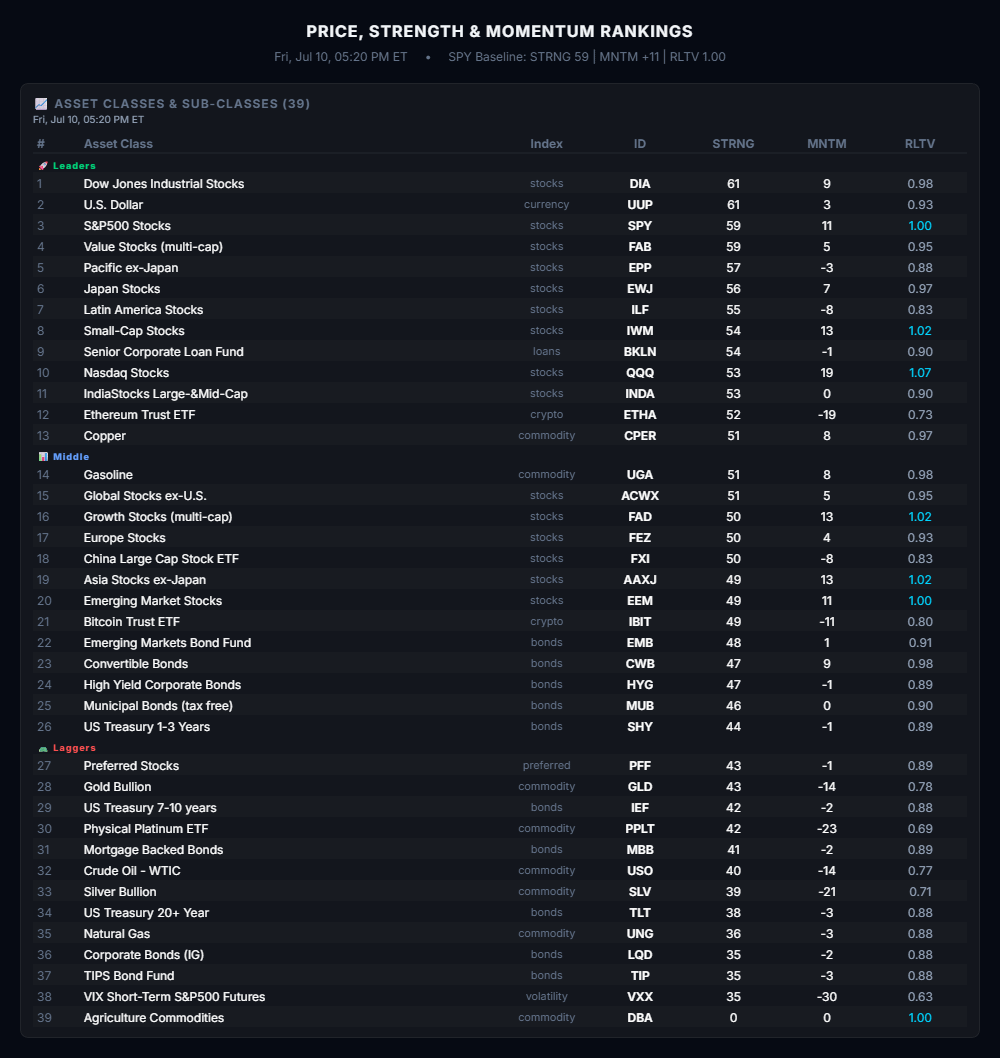
This was a week that tested the advance and passed cleanly. It opened with the baseline ripping to a fresh high of 58 on Monday, spent three sessions digesting that gain in a measured pullback to 53, then bounced off support and closed the week at a new high of 59. The baseline arc tells the whole story: 58 → 55 → 53 → 57 → 59. A push to new highs, a controlled three-day give-back, support holding exactly where it should, and a resolution back to fresh highs. Every give-back came on positive momentum, the dollar sat near the top all week on flat momentum (never once accelerating), and VIX was crushed every single session — including through the pullback. There was not one session of rising fear across the entire week. This is the signature of a healthy, trending market digesting gains, not a market under any distribution.
The one-line takeaway: The market made a new high, took a three-day breather that held support perfectly, and closed the week at fresh highs — a textbook consolidation-and-continuation that proved the advance is durable.
2. The Week’s Arc
Monday 7/6 — The fresh high. Coming out of the long holiday weekend, the baseline jumped to 58 (+5), a fresh high for the entire move, resolving the prior week’s pre-holiday drift decisively to the upside. Cyclicals and small-caps led, the dollar sank down the board on flat momentum, and VIX stayed crushed. Risk-on re-accelerated to new highs.
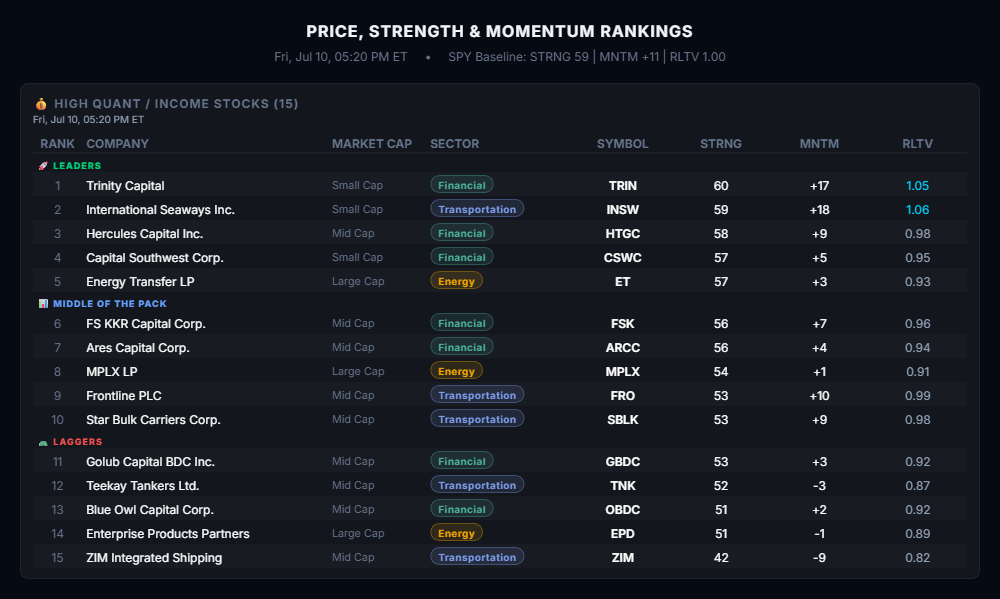
Tuesday 7/7 — Digestion begins; the High Quant layer debuts. The baseline eased to 55 (−3), beginning an orderly digestion of Monday’s push. This was the session the new High Quant single-stock screen was added to the workflow, and it immediately flashed a valuable tell: the screen had rotated hard from a screaming growth-momentum leaderboard (ENVA/PANW/HUM/NEO at +80 to +139 the prior week) into low-momentum income names (BDCs, MLPs, shipping) with the roster shrinking from 20 to 16 — a vivid single-stock confirmation of the broad momentum cool. SMH’s post-blow-off reversion continued.
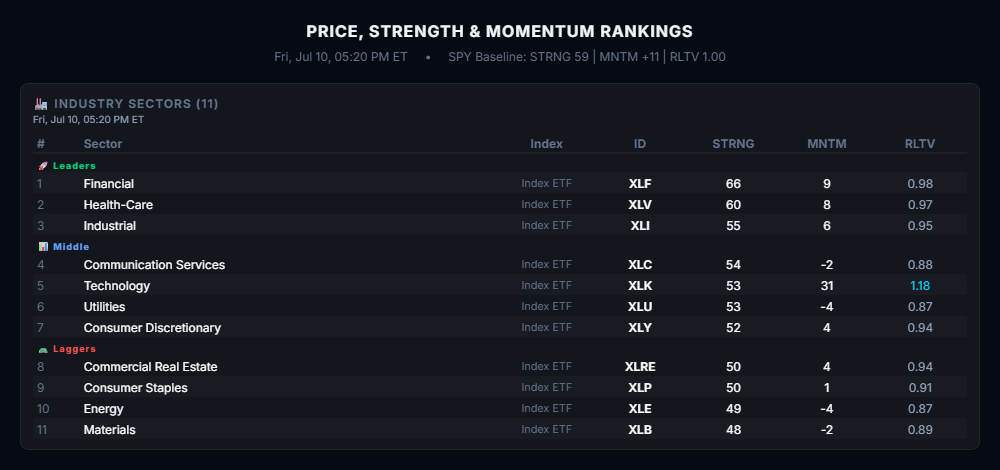
Wednesday 7/8 — Digestion deepens; the trim wire re-arms. A third cooling day to 53 on a compressed, low-energy board. The sector board wobbled mildly defensive — Health-Care retook the #1 sector from Financials — which fired the Industrials-trim wire’s condition. Per the consecutive-confirmation discipline, this was logged as day 1 of 3 (WATCH), no action, with the explicit note that it could reset if a cyclical retook #1.
Thursday 7/9 — Support holds, the bounce begins, the wire resets. The baseline firmed to 57 (+4), bouncing off the 53 support test — the digestion found its floor. And the trim wire reset cleanly: Financials retook the #1 sector, so the condition went false and the streak zeroed. Day 1 never became day 2 — the book never moved through the one-day defensive wobble. SMH began basing (strength 48→50), and the held cannabis position firmed back above the market.
Friday 7/10 — Fresh highs. The baseline pushed to 59 (+2), a new high for the move, completing the round trip. Financials held #1 for a second session, biotech held the top tier, SMH’s base firmed for a third session, and the held cannabis position firmed its relative strength to 1.05. The week closed at its strongest point.
What we got right this week: Reading the mid-week pullback as digestion rather than distribution — support held at 53 and the market made new highs. Holding the Industrials overweight through the one-day trim-wire fire (the wire reset within a session, the book never moved — the second time in three weeks the consecutive-confirmation logic saved a needless round trip). Respecting the SMH blow-off rather than chasing it — the reversion found a floor and the name is now basing constructively. And integrating the new High Quant layer as an immediate value-add — it flagged the single-stock momentum cool vividly and confirmed the advance is quality-led.
What we’re watching: Whether the advance broadens back into high-beta — the High Quant roster shrinking to 15 even as the baseline made new highs is a subtle non-confirmation, signaling single-stock momentum breadth remains narrow. If the baseline keeps extending, watch for the roster to expand and growth-momentum names to reappear (broadening) or for it to stay narrow and income-led (a quality-led advance with thinner participation). And whether SMH completes its base and re-engages as leadership.
3. The Leadership Map
🟢 Leading
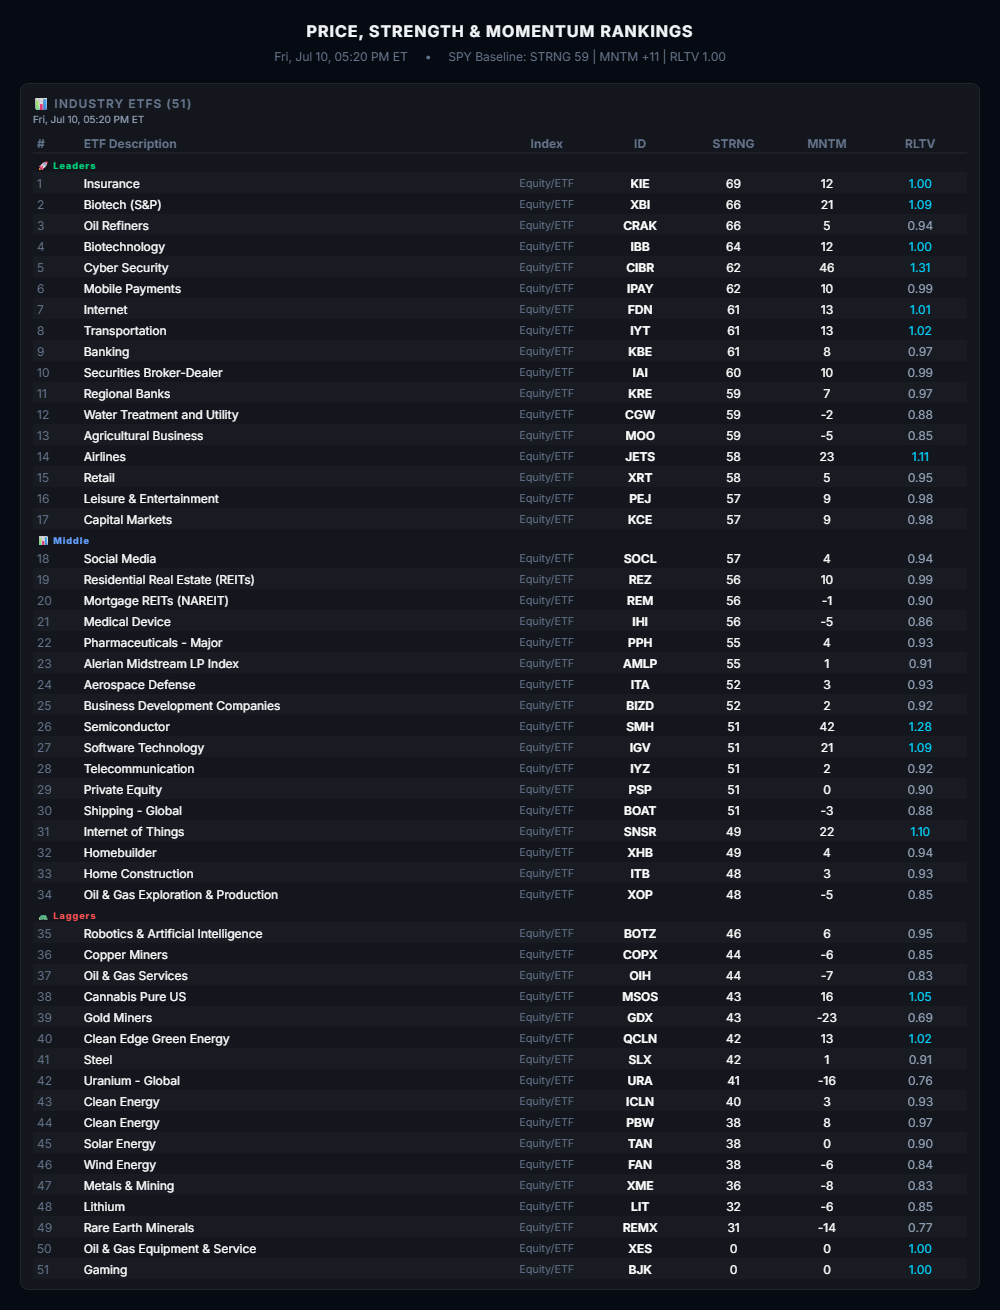
Biotech (XBI / IBB) — the standout of the week and the most durable leadership of the entire move: commanded the outright #1 ETF spot for five straight sessions before a mild Friday give-back to the top tier. It did not cede ground through the whole three-day consolidation. The anchor of the tape.
The financial complex (insurance, banking, regional banks, transportation) — owned the top tier all week under the #1 Financials sector (which held or retook the top four of five sessions). Insurance (KIE) took the #1 ETF spot Friday. The banks wobbled mid-week with the sector rotation but recovered by Thursday — the durable confirmation trade, firm.
Cyber Security (CIBR) — carried the board’s highest momentum all week (+40 to +46) with RLTV 1.24–1.31, the tech-momentum flag, and gained sector support as XLK re-strengthened.
🟡 Emerging
Semiconductors (SMH) — the week’s redemption story: from the tail of a parabolic blow-off reversion at the start, to a three-session floor-and-recovery (strength 45→48→50→51) by Friday. Basing constructively with strong momentum, setting up to potentially re-engage.
Growth / small-caps (Nasdaq, Growth, IWM) — climbed back up the board as the baseline bounced and made new highs, holding above-market relative strength. The risk complex confirming the advance.
Income / value single-stocks (TRIN, INSW) — via the new High Quant screen: BDCs and shipping names firming to beat the market, the narrow but strengthening single-stock leadership.
🔴 Lagging
Energy (commodity and equity) — dead-last-to-weak all week, unchanged in character. The persistent laggard.
Crypto & precious metals — the speculative and inflation-hedge corners bore the weakness all week (crypto’s momentum among the worst on the board, metals uniformly deeply negative), while equities made new highs. The benign profile.
High-beta growth single-stocks — the screaming momentum cohort (ENVA/PANW/HUM/NEO) that led the High Quant screen in late June stayed absent all week — the single-stock momentum that deflated and hasn’t returned.
📸 The Tape at Friday’s Close
Where the four rankings stood at week’s end. The daily posts carry the day-to-day; this is the snapshot the weekly call is built on.
4. The Macro Read
The “why” underneath the tape: this week was a healthy, quality-led continuation of the risk-on advance — and the character of the leadership is the most important observation.
The advance made new highs, but it did so without the froth. The clearest evidence is the divergence between the broad index and the single-stock momentum screen: the baseline pushed to a fresh high of 59 led by durable, broad leadership (biotech, the financial complex, insurance), while the High Quant screen showed narrow income/value single-stock leadership with the roster actually shrinking to 15. In a euphoric, late-stage melt-up, you’d see the opposite — a wide field of hot high-beta momentum names screening at extreme readings. Instead, the highest-octane individual momentum (the growth cohort that peaked in late June) has stayed deflated, and the market made new highs anyway, carried by quality leadership. That’s a healthier advance than a momentum-driven one, even if it’s less exciting — it’s less vulnerable to the kind of blow-off reversion that SMH just experienced.
The sector rotation reinforces the constructive read. Financials leading the sector board most of the week — a cyclical, rate-sensitive leader — is the market pricing a benign rate backdrop, not a defensive crouch. The one mid-week wobble toward Health-Care lasted exactly one session before cyclicals retook the top, confirming there was no genuine flight to defensives. And the bond complex staying fully unwound at the bottom of the board, with VIX crushed throughout, says there was no residual risk-off bid anywhere. The digestion was a healthy pause in a cyclical-led, rate-friendly advance.
The one thing to keep honest about is breadth. The narrow single-stock momentum participation — the shrinking High Quant roster — is a subtle non-confirmation. It’s not bearish; the broad leadership is genuinely durable. But an advance carried by a handful of broad leaders and a narrow field of income/value single-stocks is a different animal from a broadly participatory one. If the roster expands and growth-momentum names reappear as the baseline extends, that’s the signal the advance is broadening and strengthening. If it stays narrow, the advance is durable but thinner than the new-high headline suggests. The read into the weekend: a healthy, quality-led risk-on advance at new highs, with breadth the one metric to watch for confirmation or caution.
5. How I’m Positioned — The Pudding
The proof is in the pudding, so here’s the book at theme level.
Industrials: overweight — held through another trim-wire fire, vindicated again. This week delivered the second live test of the trim-wire discipline in three weeks, and it passed identically. My Industrials-overweight book trims if Industrials loses the #1 sector rank to a defensive — and mid-week, Health-Care briefly retook #1, firing the condition. Per my consecutive-confirmation standard, I logged it as day 1 of 3 (a WATCH), held the overweight, and noted it would reset if a cyclical retook the top. It reset the very next session — Financials retook #1, the streak zeroed, and the book never moved. Had I trimmed on that one-day defensive print, I’d have sold into the mid-week low and been re-buying as the cyclical-led board reasserted and the market made new highs. The overweight is intact and well-positioned at fresh highs. One day never makes a portfolio decision; this week proved it for the second time.
No financials in my book. The financial complex — insurance, banking, regional banks — was the deepest leadership cluster on the board again this week under the #1 Financials sector. I read it openly because it’s the clearest signal out there. But it’s not in my book, and I don’t chase it mid-advance. I note the strength; I stay in my lane.
Semis: market-weight, by hard-won lesson — and this week vindicated it twice over. Semiconductors entered the week still unwinding from the parabolic +81 blow-off, and by Friday had built a constructive three-session base (strength 48→50→51). Holding market-weight through the whole arc — refusing to chase the blow-off peak two weeks ago, and refusing to panic-cut the reversion — is exactly the discipline. The name is now basing with strong momentum and may set up to re-engage. Had I chased the peak, I’d have ridden the reversion down; had I cut the reversion, I’d have sold the base. Market-weight, patient, was correct.
The cannabis position: held full-size at conviction throughout — worked through a soft patch, relative strength now firming. I’ve held this position full-size continuously — the thesis never broke, so the position never moved. This week tested that conviction: the strength rank slipped into a soft patch (sub-50 for five sessions) and mid-week the relative strength briefly dipped to market-level. But my thesis-break bar requires a sustained break with momentum rolling negative, and momentum stayed positive every single session — so the bar was never met, and I held. By Friday the position had firmed its relative strength back to a comfortable above-market 1.05, beating the market for a third straight session with firming momentum. Holding conviction through the soft patch — rather than flinching at a weak strength rank and manufacturing an exit — is what kept the position in place as its relative performance reasserted. The thesis determines the position, the bar defines the exit, and neither was breached.
6. The Bottom Line
This week was a healthy, quality-led continuation of the risk-on advance — a fresh high, a textbook three-day digestion that held support at 53, and a resolution back to new highs at 59, with VIX crushed and no session of rising fear all week. The leadership is durable and broad (biotech anchoring for five sessions, the financial complex deep under the #1 sector) rather than frothy, which is a healthier advance even if the narrow single-stock momentum breadth is the one metric to watch. My Industrials overweight was vindicated by holding through a second one-day trim-wire fire (the wire reset within a session), my market-weight semis discipline was vindicated as the blow-off based constructively, and my full-size cannabis conviction held and worked as its relative strength firmed back above the market. The new High Quant layer proved an immediate value-add, flagging the single-stock momentum cool and confirming the quality-led character of the advance. Into next week I’m watching one thing above all: whether breadth broadens — the High Quant roster expanding and growth-momentum names reappearing — to confirm the advance, or stays narrow and income-led.
This report is a synthesis of the week’s daily Price, Strength & Momentum reads. For informational and educational purposes only; not investment advice. Positions and views are my own and may change without notice.
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34.