

CALLED IT — the July-close tech-strength question, answered in real time
“Tech momentum re-fired into the close (CIBR +36, four of the screen’s top six turned tech) — the key watch into next week is whether tech STRENGTH follows the momentum.” That question closed the July monthly and the prior weekly, framed as the thing to watch into August. This week answered it — yes. Monday, internet/software/cyber climbed into the ETF leaders on strength (63–66), and ten-plus screen names carried strength 54–68. Tuesday it deepened — Technology jumped to the #3 sector with the board’s best RLTV, the cohort to strength 61–85. The momentum-without-strength trap that caught the mid-month MXL spike did not repeat: this time strength confirmed. The question was posed in advance and answered in the affirmative within two sessions — the application-layer tech rotation is real, strength-backed, and now a durable leadership leg.
GATE 1 — THE CLOCK
State: OPEN RUNWAY — no heavyweight catalyst; a clean trend-following week.
The read: with the FOMC-plus-PCE cluster behind us (last week), this week had no comparable heavyweight event on the calendar — an open runway for the post-catalyst trend to express itself. And express it did: a powerful four-session advance, an orderly two-day digestion, and a close back at the highs, all without an external catalyst forcing the action. Trust level for this week’s signals: HIGH. In a clean, catalyst-light week, the tape’s action is the signal — the advance, the broadening leadership, and the benign consolidation are all endogenous trend behavior, not positioning around a known event. What the tape did this week is what the trend wanted to do.
GATE 2 — THE FEAR VARIABLE
Verdict: FEAR ABSENT. Every single session. Through the advance AND the consolidation.
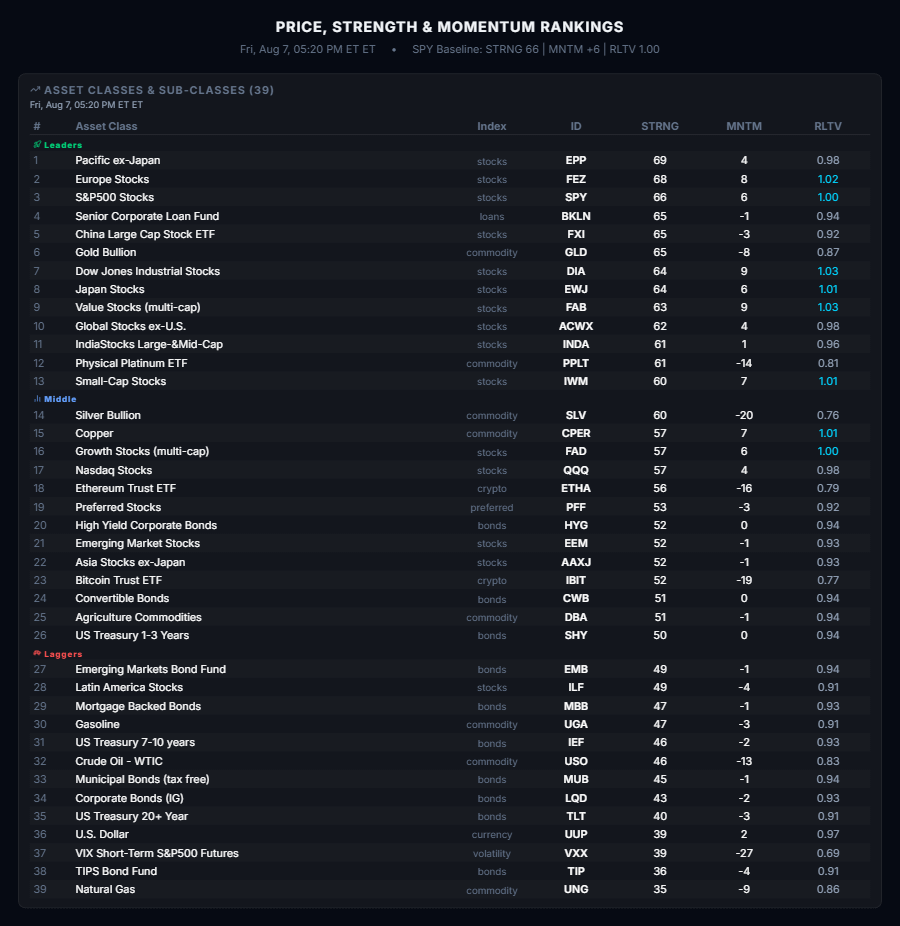
The fear signature was crushed the entire week, and — critically — stayed crushed through the midweek pause. VIX (VXX) momentum sat in the −26 to −29 zone all five sessions, reaching its deepest reading of the entire stretch (−29) on Wednesday’s first down-day — vol sold harder as price paused. Bonds never once caught a safety bid: the entire duration complex (TLT, IEF, LQD, TIP) sat pinned at the bottom of the asset board all week, making no move for safety on the run up, the digestion, or into the close. The dollar stayed weak throughout. The single most important tell of the week: when the advance paused midweek, fear went down, not up. A consolidation accompanied by record vol-selling and no bond bid is benign digestion, not distribution — and that read, established Wednesday, was confirmed Friday when the pause resolved right back to the highs.
GATE 3 — THE PHASE
Phase: BROADENING ADVANCE — a hard run, an orderly digestion, a close at the highs.
The baseline arc across the week: 59 → 66 → 65 → 64 → 66. A powerful two-session run to a fresh stretch high (59 → 66, with momentum accelerating +5 → +7), an orderly two-day digestion (66 → 65 → 64, two one-point ticks), and a resolution right back to the 66 high into the close. Net: +7 on the week, closing at the high. This is the reset-and-resolve thesis — which began at the 7/29 FOMC low (39) — maturing into a multi-week, broadening advance now in full control.
The read carried in the daily notes all week held: the pause was digestion, not distribution. When the baseline ticked down Wednesday and again Thursday, the daily read stayed constructive — the fear signature (vol sold harder than ever, no bond bid) said benign consolidation, and the leadership held its character. Friday confirmed it: the pause resolved right back to the high. (Stated callback from the daily chat notes across the week, not a published post — not a link.)
Default posture from this phase: HOLD — the trend is intact and at its highs. The one thing that would have argued for trimming risk — the midweek pause turning into a genuine rollover with fear entering — never materialized. Fear stayed absent, the pause resolved up, and the leadership broadened rather than narrowed. This Conclusion is not provisional: the advance is in control, and the read carries into next week intact.
EXTERNAL CORROBORATION — THE FOLLOW-THROUGH DAY
An independent framework confirmed the same regime call, on the same dates: William O’Neil’s Follow-Through Day fired 8/4.
This week’s advance wasn’t only confirmed by our own gates — it was independently confirmed by a decades-old institutional framework that measures something completely different. William O’Neil’s Follow-Through Day (FTD), the canonical IBD/CANSLIM bottom-confirmation signal, looks for a major index to post +1.25%+ on volume greater than the prior day, on day 4–7 of a rally attempt. On real, verified QQQ data (sourced from S&P Global Market Intelligence), that’s exactly what happened — and the dates map onto our own read one-for-one:

Why this matters. These are two genuinely independent frameworks: one is a price-and-volume Wall Street staple watched by a large institutional cohort (on QQQ/Nasdaq); the other is our strength/momentum in-house model (on SPY). They share no inputs — one keys on daily percentage change and volume, the other on 52-week range position and day-over-day momentum. And they marked the same bottom (7/29), the same turn (7/30), and the same confirmation (8/4). When two methods that measure different things on different instruments converge this precisely, the regime call is far less likely to be noise — it’s genuine triangulation, and it tells us a real institutional cohort is confirmed long alongside our read.
How we treat it. Our six gates remain the engine — they’re what we compute from the board. The FTD is an external overlay we monitor, not a seventh gate (our dashboard carries no volume field, so we can’t generate an FTD ourselves — we track the public count). And we hold it with the same honesty the framework itself demands: an FTD is confirmation, not a guarantee — many fail — which is the same “confirm the bottom, don’t predict it” stance our own model takes. As of this week’s close the FTD count is intact (QQQ never undercut the 673.30 Day 1 low), corroborating our confirmed-uptrend read. Going forward this overlay stays dormant as a one-line status until a new FTD-relevant event — a count-resetting break of the confirmed trend, or the next correction-and-rally-attempt cycle. The highest-value moment for this cross-check is still ahead: the session the two frameworks disagree. That divergence — whenever it comes — will be a signal worth acting on.
GATE 4 — LEADERSHIP CONFIRMATION
Grade: CONFIRMED (high conviction) — and broadening all week, from a two-engine base to a genuinely wide, multi-theme leadership.
The week’s leadership story is broadening. It began as a two-engine advance (rate-sensitive plus the newly-strengthening tech) and widened, session by session, into a genuinely broad, multi-theme leadership by the close.
The tech rotation — the week’s headline — confirmed and deepened. The July-close question (does tech strength follow the momentum?) was answered yes on Monday and deepened all week: internet/software/cyber climbed into the ETF leaders on strength (Monday, strength 63–66), Technology jumped to the #3 sector with the board’s best RLTV (Tuesday), and the single-stock cohort built to strength 61–85. This is application-layer tech (software, internet, cyber) — a genuine, strength-backed leadership leg, distinct from the momentum-only spike that failed mid-July.
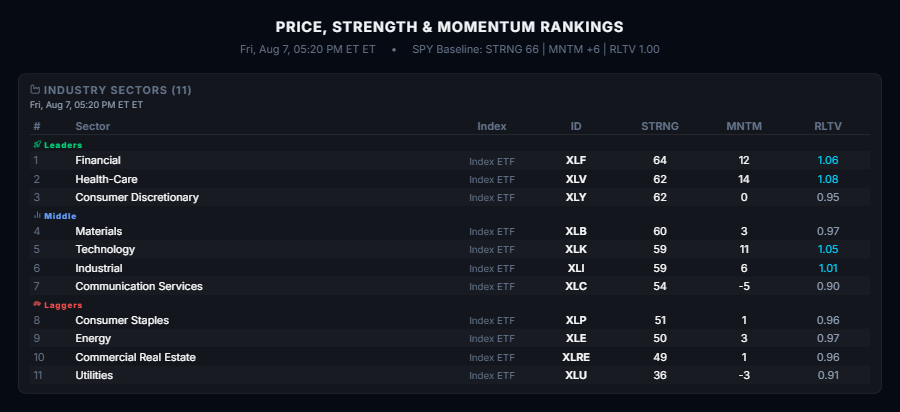
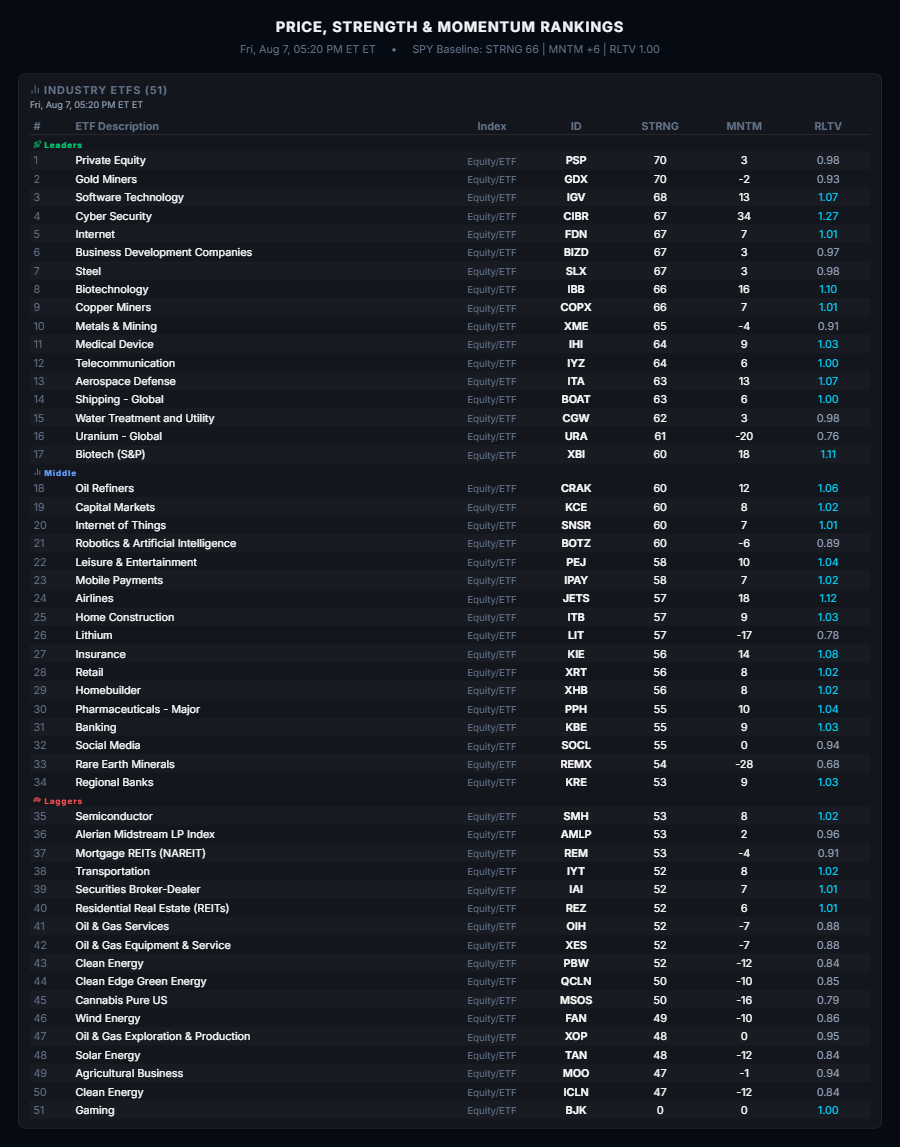
The quality leg re-asserted into the close. After Health-Care eased to the #8 sector early in the week as the advance broadened, the quality leg firmly re-asserted through the consolidation — #5 Wednesday, #2 Thursday, #2 Friday with the board’s best RLTV (1.08) — and broadened into biotech into the close (IBB RLTV 1.10, XBI 1.11). Quality catching a bid on the consolidation is classic benign-pause behavior, and it deepened from the quality/pharma names into higher-beta biotech.
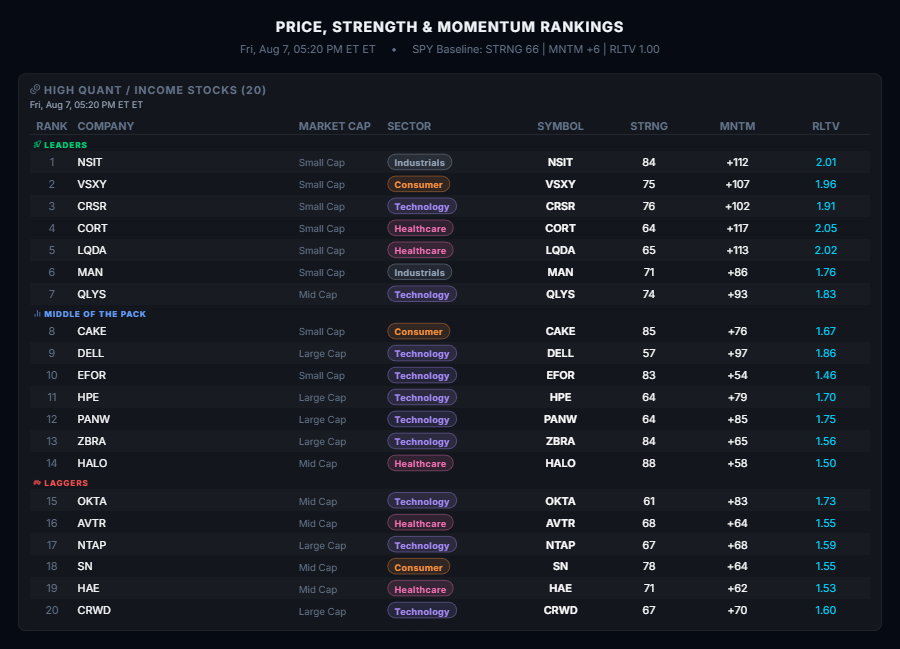
Two new legs joined into the close: metals/miners and a broad single-stock screen. The reflationary-metals theme strengthened into the close (gold miners #2 on the ETF board, copper miners, steel, metals all in the top ten), a distinct leg tied to copper. And the single-stock screen became the widest of the stretch — industrials (NSIT #1), tech, healthcare quality (HALO at strength 88, the highest on the board), and consumer all represented at high strength, with fresh leaders rotating in (VSXY, CRSR, HALO, SN). Leadership widened all week.
The semis thread — honest and unresolved. The one leadership question that didn’t resolve cleanly: whether the tech rotation would broaden from application-layer to semiconductors. It teased on Tuesday (SMH strength 44→51, RLTV above market), stalled Wednesday–Thursday (flat at 50, RLTV back below market), and firmed again Friday (50→53, RLTV back above market). Net across the week: choppy but modestly higher (44→53), still lagging on rank. The chip catch-up is grinding, not clean — real but unconfirmed, and the honest read is that it carries into next week as a live watch rather than a resolved leg.
GATE 5 — THE WIRE & THE BAR
Trip wire: DORMANT all week (and read correctly through Health-Care’s climb). MSOS exit bar: REDUCE HELD — the both-halves discipline kept the position out of a strength-bounce trap.
The Industrials trim wire — dormant all week, with the Health-Care read handled correctly. The wire requires a defensive at #1 with fear present. All week, a cyclical (Financials) held the #1 sector and fear was absent — so the wire stayed dormant. The one nuance worth addressing: Health-Care climbed to and held the #2 sector across the back half of the week. Under old logic, a defensive climbing the board might read as caution. But the wire is fear-gated, and with fear crushed every session, Health-Care’s climb reads as a no-fear quality bid — a flight to quality within risk-on, not a flight to safety — the same framing that applied when Health-Care took #1 on the FOMC-day break (and reversed within a session). Health-Care never took #1, fear never appeared, and the overweight (Industrials, top-6 all week) was never threatened. No action, correctly.
The cannabis exit bar — the reduce held, and the both-halves discipline earned its keep this week. The bar requires both sub-50 strength and negative momentum; re-entry requires both momentum-positive and strength-above-50. This week was a live test of that both-halves logic on the re-entry side. MSOS strength churned in a 39–50 range all week — bouncing to 47 Tuesday, reversing to 39 Wednesday, back to 49 Thursday, reaching exactly 50 Friday — while momentum stayed pinned negative every single session (−10 to −20, five straight, never turning positive once). Twice the strength bounce looked tempting; both times momentum refused to confirm. Had the re-entry been triggered on either strength bounce, it would have been chasing a move momentum never backed — and the Wednesday reversal, and the persistently negative momentum into Friday, would have caught it. Holding the both-halves line kept the position correctly reduced through a full week of strength head-fakes. Reduce held. No action.
GATE 6 — THE ROUTED DECISION
BROADENING ADVANCE (a hard run, an orderly digestion, a close at the highs), Fear Absent every session (including deepest-of-stretch vol-selling on the down-days), leadership CONFIRMED and broadening from a two-engine base to a wide multi-theme leadership (tech rotation confirmed and deepened, quality leg re-asserted and broadened into biotech, metals/miners and a broad single-stock screen joining), trip wire dormant / cannabis reduce held → HOLD the book; the trend is intact and at its highs. The reset-and-resolve thesis is now a multi-week broadening advance in full control.
This Conclusion becomes next week’s Observation. The week resolved every question it opened except one. The tech-strength question (carried from July’s close) resolved yes — application-layer tech is a confirmed, strength-backed leadership leg. The midweek-pause question resolved benign — it was digestion, and it resolved back to the highs. The quality-leg question resolved into a firm re-assertion and a broadening into biotech. The one live thread carried into next week: whether the semis catch-up — grinding higher but choppy (SMH 44→53 on the week, still lagging on rank) — converts into a genuine chip leadership leg, or stalls out. That’s the single thing to watch first. Everything else points to a strengthening, broadening risk-on trend at its highs.
HOW I’M POSITIONED — THE PUDDING
Industrials: overweight — held all week, participating in a broadening advance. The overweight held top-6 at the sector level all week (eased in rank from #2 Tuesday to #6 Friday only because leadership broadened, not because Industrials weakened — it held above market with positive momentum throughout), with aerospace (ITA) carrying RLTV 1.07 and the single-stock screen showing broad industrials strength (NSIT #1 both Thursday and Friday, MAN top-six). The trim wire stayed dormant all week. The overweight is being rewarded in a broad advance.
Long TRIN and MAIN (calls). The rate-sensitive/financial complex held the #1 sector (Financials) all week — the most durable leadership on the board — with insurance (KIE, RLTV 1.08), capital markets, aerospace, and the banks firm throughout. Direct exposure through Trinity Capital and Main Street Capital call options, core to the BDC/income cohort. The complex led every session of a week that closed at the highs.
Semis: market-weight — grinding higher, still the honest watch. The chip catch-up teased, stalled, and firmed across the week (SMH strength 44→53, RLTV closing back above market), but remains choppy and lagging on rank. Market-weight stays the right posture: the broadening-to-chips is real but unconfirmed, and I want strength to hold above market for more than a session before treating semis as a leadership leg. If it converts, the sizing revisits; for now, market-weight with a live watch.
Cannabis: REDUCED — held through a week of strength head-fakes. The both-halves re-entry discipline earned its keep this week: strength churned 39–50 while momentum stayed negative every session, and holding the line (no re-entry until momentum-positive and strength-above-50) kept the position out of a strength-bounce trap that momentum never backed. No re-entry until both halves confirm — neither did this week.
THE BOTTOM LINE
The first week of August closed exactly as the framework would want. A powerful advance to a fresh stretch high, an orderly two-day midweek digestion, and a resolution right back to the high into the close — +7 on the week, with fear crushed every single session and, tellingly, crushed hardest on the down-days. The midweek pause was digestion, not distribution; it resolved up, and the reset-and-resolve thesis that began at the FOMC low is now a multi-week broadening advance in full control.
The week’s defining move was the confirmation of the tech rotation — the July-close question, answered yes: application-layer tech (software, internet, cyber) is now a genuine, strength-backed leadership leg, the momentum-without-strength trap of mid-July decisively not repeated. And leadership broadened all week — the quality leg re-asserted and deepened into biotech, metals/miners surged in, and the single-stock screen became the widest of the stretch. Two disciplines held quietly and correctly: the trim wire stayed dormant (Health-Care’s climb read correctly as a no-fear quality bid, not defensive flight), and the cannabis reduce held through a full week of strength head-fakes that momentum never confirmed.
The read into next week: a strengthening, broadening risk-on trend at its highs, with leadership wide and healthy. The one live thread to watch first — whether the semis catch-up (grinding higher but choppy) converts into a genuine chip leadership leg, or stalls. Everything else points higher.
GET THE CALLS FIRST
The daily notes carry the day-to-day reads — the baseline arc session by session, the wire and bar checks in real time, the single-stock screen shifts. The weekly is the recap; the calls land in the chat first (this week: the tech-strength question, posed at July’s close, answered yes by Monday; the midweek pause read as benign digestion in real time and confirmed Friday). Subscribe for the daily feed.
This report is a synthesis of the week’s daily Price, Strength & Momentum reads. For informational and educational purposes only; not investment advice. Positions and views are my own and may change without notice.
Pressure, not panic. Regime, not reaction.
Cross-asset macro research and education — built for the everyday person.
The information on this website/Substack is for information purposes only. It is believed to be reliable, but 34 Macro does not warrant its completeness or accuracy. The information on the website/Substack is not intended as an offer or solicitation for the purchase of stock or any financial instrument. The information and materials contained in these pages and the terms, conditions and descriptions that appear, are subject to change without notice. Unauthorized use of 34 Macro websites and systems including but not limited to data scraping, unauthorized entry into 34 Macro systems, misuse of passwords, or misuse of any information posted on a site is strictly prohibited. Your eligibility for particular services is subject to final determination by 34 Macro and/or its affiliates. Investment services are not bank deposits or insured by the FDIC or other entity and are subject to investment risks, including possible loss of principal amount invested. Your use of any information which is proprietary to 34 Macro or a third-party information provider shall only be used on individual devices without any right to redistribute, upload, export, copy, or otherwise transfer the information to any centralized interdepartmental or shared device, directory, database or other repository nor to otherwise make it available to any other entity/person/third party, without the prior written consent of 34.